Page 1: identifying information
Items A to C, the filer on line 1, the foreign trust on line 2, any U.S. agent on line 3, and a U.S. decedent on lines 4a to 4f.
3520
Annual Return To Report Transactions With Foreign Trusts and Receipt of Certain Foreign Gifts
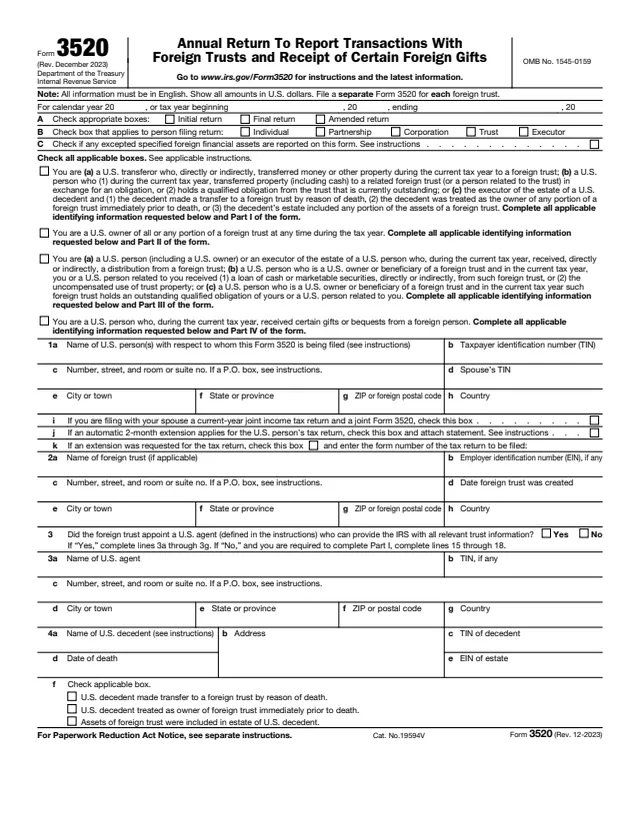
Form 3520 is the annual return U.S. persons, and executors of estates of U.S. decedents, file with the IRS to report certain transactions with foreign trusts, ownership of foreign trusts under the rules of sections 671 through 679, and receipt of certain large gifts or bequests from certain foreign persons. A separate Form 3520 is filed for each foreign trust.
The form has four parts: transfers to a foreign trust (Part I), a U.S. owner of a foreign trust (Part II), distributions from a foreign trust (Part III) and gifts or bequests from foreign persons (Part IV). The filer completes the identifying information on page 1 and the parts that apply. The form says all information must be in English and all amounts in U.S. dollars.
The instructions say Form 3520 is generally due on the 15th day of the 4th month after the end of the filer's tax year, a date that may differ from and is not tied to the income tax return due date. You can fill out Form 3520 free in your browser on this page and download the result without an account.
Items A to C, the filer on line 1, the foreign trust on line 2, any U.S. agent on line 3, and a U.S. decedent on lines 4a to 4f.
Lines 5 to 19, with Schedule A for obligations of a related trust, Schedule B for gratuitous transfers and Schedule C for qualified obligations outstanding.
Lines 20 to 23: the trust owners, where the trust was created, whether the trust filed Form 3520-A, and the gross value of the portion you are treated as owning.
Lines 24 to 53: distributions, loans and use of trust property, beneficiary statements, the default or actual calculation, and the interest charge.
Lines 54 to 56: gifts or bequests from nonresident aliens or foreign estates, gifts from foreign corporations or partnerships, and a nominee or intermediary question.
The filer signs under penalties of perjury with title and date. A paid preparer completes the Paid Preparer Use Only section.
Fill in the calendar year, or the fiscal year dates, at the top. Check initial, final or amended return in item A, the filer type in item B, and item C only when Form 8938 counts this form.
Enter the filer's name, TIN and address. Joint filers list names and TINs in the order used on Form 1040 or 1040-SR and check line 1i. Lines 1j and 1k cover a 2-month extension or an extended tax return.
Enter the foreign trust's name, EIN, address and creation date. On line 3, answer whether the trust appointed a U.S. agent. If No and Part I applies, lines 15 to 18 are completed too.
Complete only the parts that apply. On line 22, a U.S. owner attaches the Foreign Grantor Trust Owner Statement, or a substitute Form 3520-A if the trust did not file Form 3520-A.
On line 54, list each gift or bequest over $5,000 when the total from nonresident aliens or foreign estates is over $100,000. The instructions say gifts from related donors are added together.
An individual or fiduciary signs; a partner or LLC member signs for a partnership, and an authorized officer for a corporation. The instructions say e-signatures are accepted.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Generally the 15th day of the 4th month after the tax year ends; with an income tax return extension, no later than the 15th day of the 10th month. Certain individuals abroad have until the 15th day of the 6th month (June 15), with a statement.
Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The instructions say only a complete Form 3520, including all required attachments, is considered timely filed.
Generally the greater of $10,000 or 35% of property transferred (Part I) or distributions received (Part III), or 5% of the gross value owned (Part II). No penalty applies with reasonable cause and not willful neglect.
For foreign gifts not reported on time, the instructions describe a penalty of 5% of the amount of the gifts for each month the failure continues, not to exceed a total of 25%.
The instructions say a filer may also need FinCEN Form 114 (FBAR) and Form 8938. Items treated differently from the trust's Form 3520-A are reported on Form 8082.
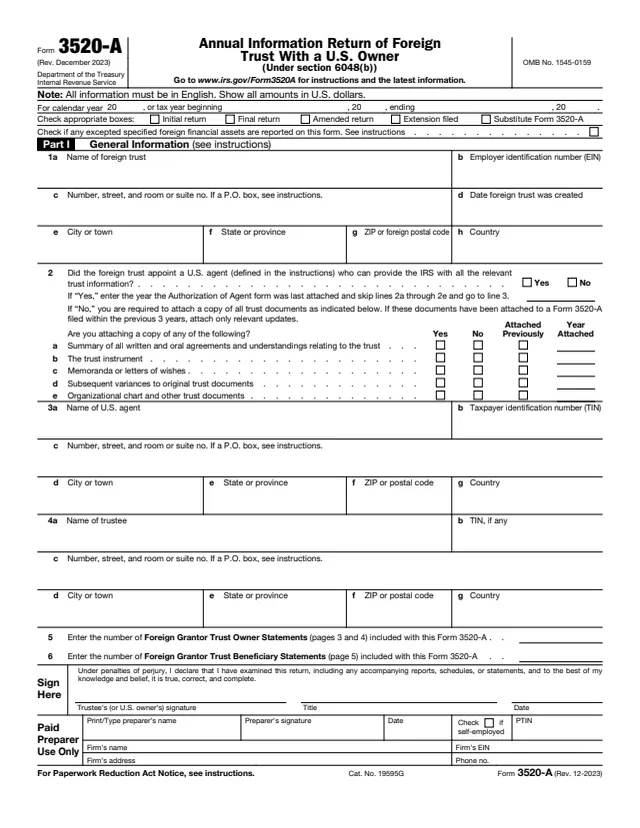
3520-A
386 fields, 5 pages
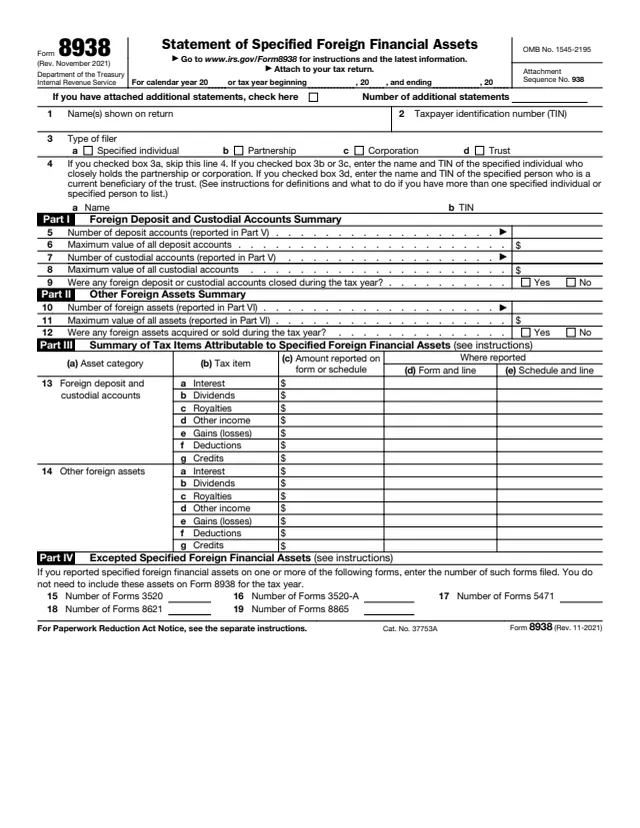
8938
131 fields, 2 pages
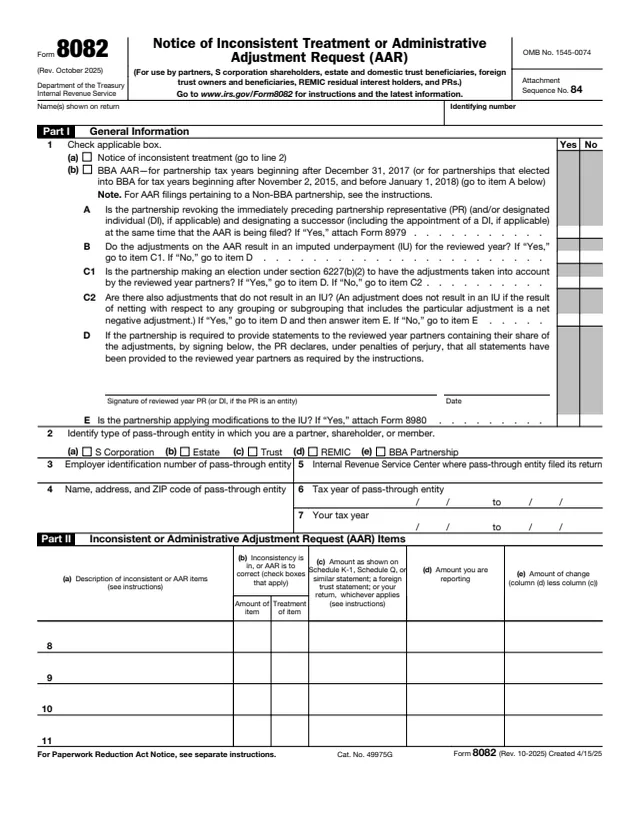
8082
59 fields, 2 pages
4970
63 fields, 2 pages
708
1,044 fields, 10 pages
709
1,851 fields, 10 pages
The instructions list four situations, and any one of them is enough. Line B shows the filer type: individual, partnership, corporation, trust or executor.
No tool matches that search.
The instructions give a separate address, the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409, and say the Form 3520 due date may differ from and is not tied to the income tax return due date.
Part IV covers more than $100,000 treated as gifts or bequests from a nonresident alien or foreign estate, or more than the section 6039F threshold from foreign corporations or partnerships. The instructions point to IRS.gov/InflationAdjustment for that threshold.
Columns (a) to (c) of line 54 are completed for each gift or bequest over $5,000. If none exceeds $5,000, the instructions say to enter "No gifts or bequests exceed $5,000." in column (b) of the first line.
Form 3520 is filed by U.S. persons. Form 3520-A is the foreign trust's annual information return. A U.S. owner attaches the trust's owner statement to Form 3520, or a substitute Form 3520-A if the trust did not file.
The instructions list transfers to, ownership of and distributions from a Canadian RRSP, a Canadian RRIF, or other Canadian retirement plans within section 3 of Rev. Proc. 2014-55 among the exceptions to filing.
Yes, if they file a joint income tax return and are both transferors, grantors or beneficiaries of the same foreign trust. They check the box on line 1i.
The instructions describe penalties under section 6677 for the trust parts and section 6039F for foreign gifts, plus more penalties if noncompliance continues over 90 days after an IRS notice. No penalty applies with reasonable cause and not willful neglect.