Name and identifying number
The name or names shown on the return and the identifying number.
8082
Notice of Inconsistent Treatment or Administrative Adjustment Request (AAR)
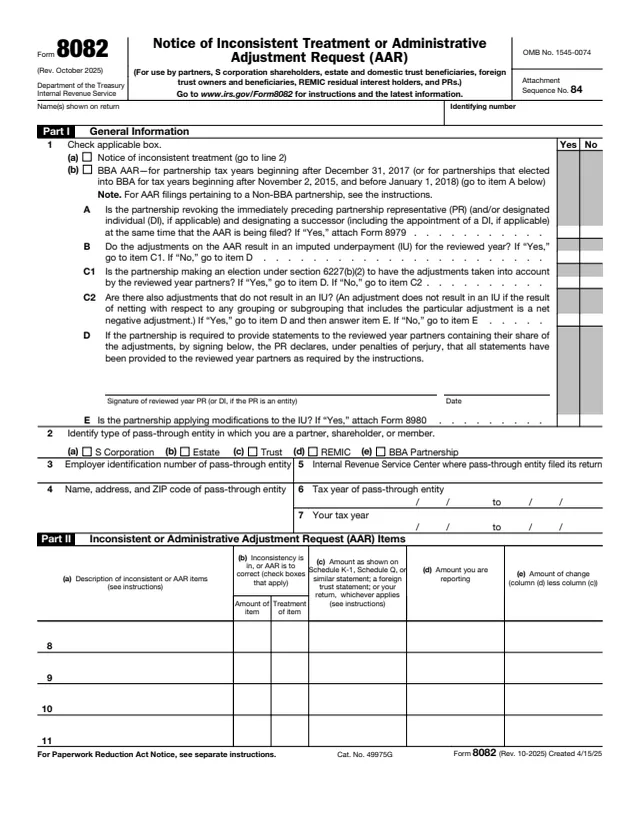
Form 8082, Notice of Inconsistent Treatment or Administrative Adjustment Request (AAR), has two uses. The form says it is for use by partners, S corporation shareholders, estate and domestic trust beneficiaries, foreign trust owners and beneficiaries, REMIC residual interest holders, and partnership representatives (PRs).
As a notice of inconsistent treatment, it tells the IRS that an item is being reported differently from the way a pass-through entity reported it on Schedule K-1, Schedule K-3, Form 8986, Schedule Q or a foreign trust statement, or that one of those statements was not received by the due date of the return. As a BBA AAR, it is filed by the PR, or by the designated individual (DI) when the PR is an entity, to request an administrative adjustment correcting a previously filed partnership return under the centralized partnership audit regime of the Bipartisan Budget Act of 2015 (BBA).
You can fill out the PDF free in your browser on this page and download it without an account.
The name or names shown on the return and the identifying number.
Box (a) for a notice of inconsistent treatment, or box (b) for a BBA AAR, followed by items A through E about a PR change, an imputed underpayment (IU), the section 6227(b)(2) election, the PR's signature and modifications to the IU.
The type of pass-through entity (S corporation, estate, trust, REMIC or BBA partnership), its EIN, name and address, the IRS service center where it filed, its tax year, and your tax year.
Up to four items, each with a description, whether the amount or the treatment is inconsistent or being corrected, the amount as shown on the statement or return, the amount being reported, and the change.
Page 2 holds the explanations, each starting with its Part II item number. The form says to show how the IU was calculated and how modifications were applied.
Check box (a) for a notice of inconsistent treatment and go to line 2. A BBA partnership filing an AAR checks box (b) and answers items A through E. The instructions say the PR manually signs under item D, and that Form 8979 is attached for a PR change and Form 8980 for IU modifications.
The instructions say this information can generally be found on Schedule K-1, Form 8986, Schedule Q or the foreign trust statement.
In column (a), enter the line number and description shown on the statement received, or a full description if none was received. In column (b), check amount of item, treatment of item, or both. The instructions say columns (d) and (e) are skipped when only treatment is checked.
Column (c) is the amount on the statement received, or zero if no statement was received, the entity filed no return, or the item was omitted. Column (d) is the amount being reported as correct. Column (e) is the difference, with negative amounts in parentheses.
Explain how each item should be treated and why. The instructions give set wording for missing items, such as "Schedule K-1 (Schedule K-3, Schedule Q, and/or foreign trust statement) not received."
For a notice of inconsistent treatment, complete a single copy, attach it to your tax return and file it with the original return. A BBA AAR goes with Form 1065, plus Forms 8985 and 8986 when they apply.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say "Don't file Form 8082 by itself." A notice of inconsistent treatment is attached to the tax return, and the instructions say a BBA AAR's Form 8082 should be attached as a PDF to Form 1065.
A separate form for each pass-through entity. Part II has four lines, so more than four monetary items from one entity need additional Forms 8082.
The instructions say generally within 3 years after the later of the date the entity's return was filed or its last filing day (excluding extensions). A BBA partnership that has received a notice of administrative proceeding may not file an AAR.
The instructions say that if the IRS is not notified of an inconsistent item, a deficiency from making it consistent with the entity's return may be assessed immediately.
The instructions say disregarding the filing requirements may bring the accuracy-related penalty under section 6662 or the fraud penalty under section 6663.
An AAR requesting an electronically deposited refund of $1 million or more attaches Form 8302.

1065
440 fields, 6 pages
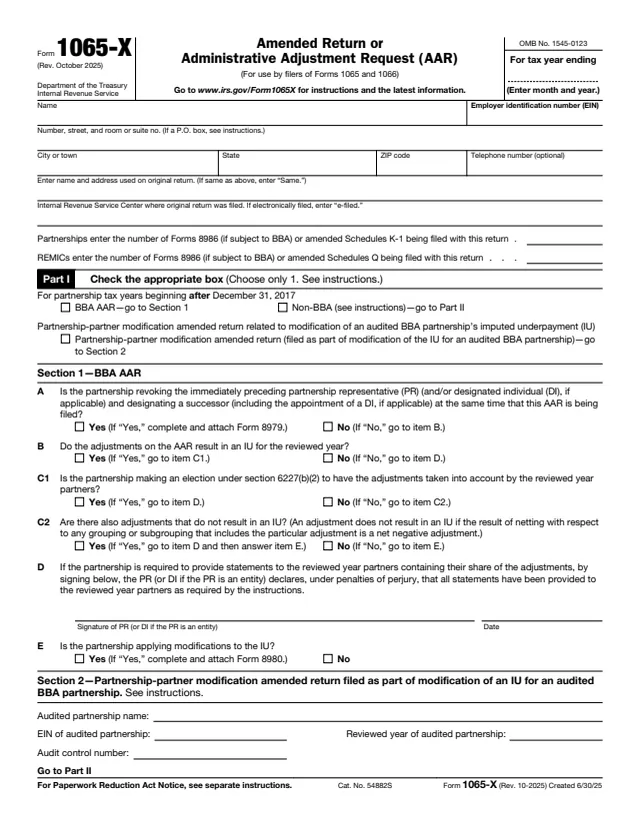
1065-X
227 fields, 4 pages
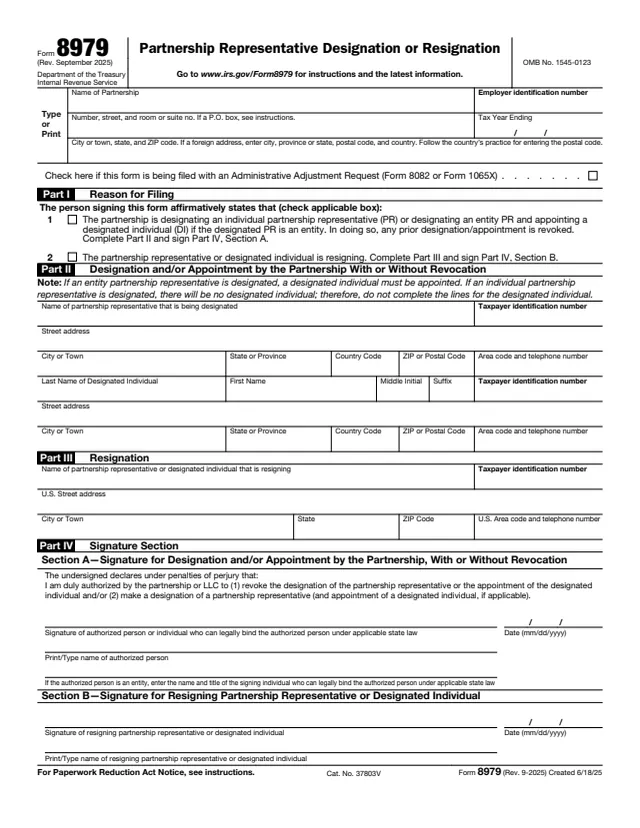
8979
45 fields, 1 page

1065
111 fields, 1 page
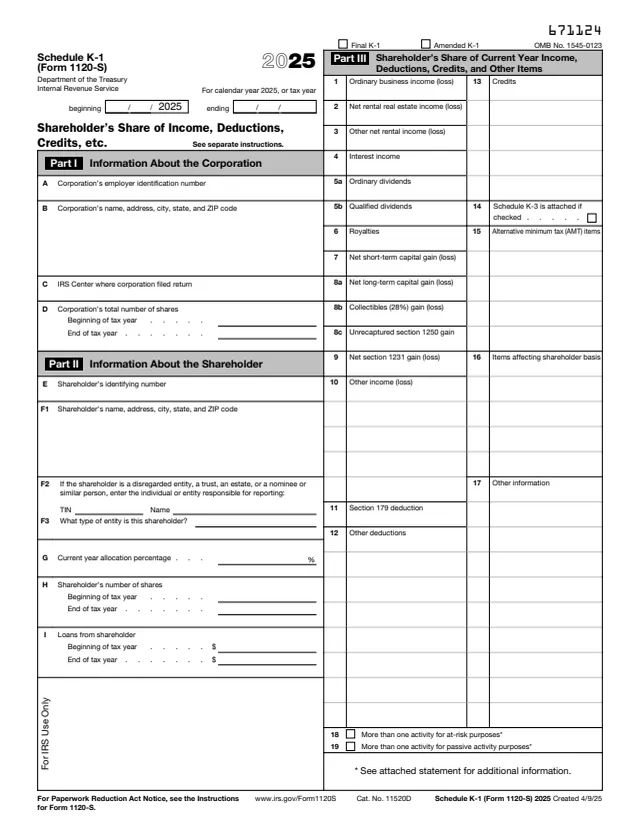
1120-S
114 fields, 1 page
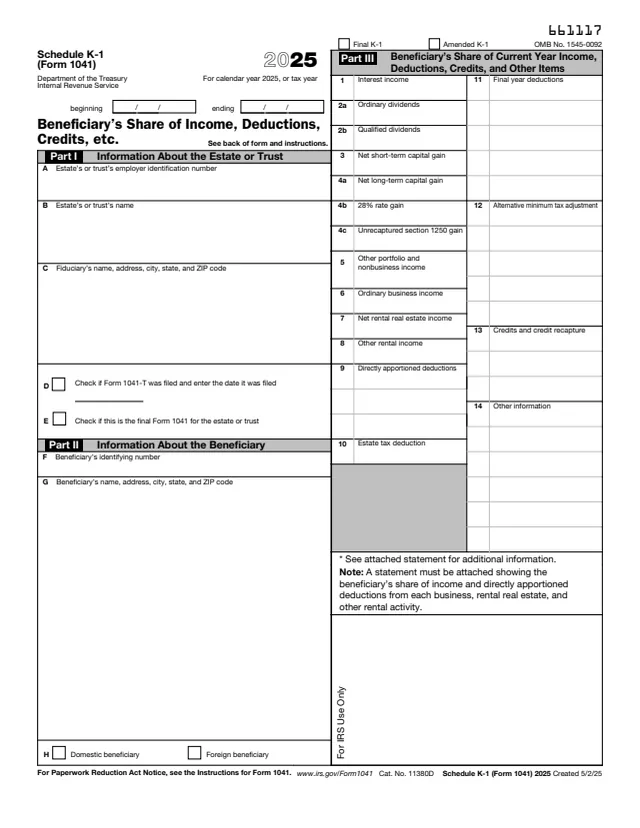
1041
74 fields, 2 pages
Owners and beneficiaries of pass-through entities use it as a notice of inconsistent treatment. A BBA partnership's PR uses it to file an AAR.
No tool matches that search.
It tells the IRS that you are treating an item differently from the way the partnership, S corporation, estate, trust or REMIC reported it on your Schedule K-1, Schedule K-3, Form 8986, Schedule Q or foreign trust statement.
The instructions say Form 8082 is also used when a Schedule K-1, Schedule Q or foreign trust statement was not received by the return's due date. Parts I and II are completed to the best of your knowledge.
The partnership representative, or the designated individual when the PR is an entity, on behalf of a BBA partnership correcting a previously filed partnership return.
No. The instructions say a shareholder cannot use it to request an administrative adjustment to correct S corporation items and files an amended income tax return instead.
No. The instructions say not to file it by itself. It goes with your tax return, or with Form 1065 for a BBA AAR.
Part II has four lines. The instructions say to use additional Forms 8082 for more than four monetary items, and a separate form for each pass-through entity.