Partnership information
Name of partnership, employer identification number, address, tax year ending date, and a box to check when the form is filed with an administrative adjustment request on Form 8082 or Form 1065-X.
8979
Partnership Representative Designation or Resignation
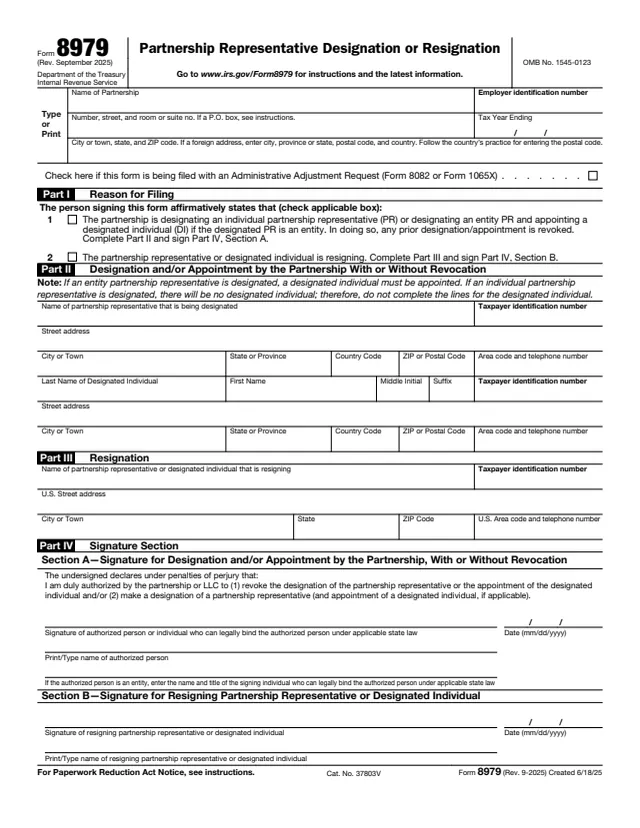
Form 8979 is the IRS form a partnership uses to designate a partnership representative (PR) and, when the PR is an entity, to appoint a designated individual (DI) who acts for that entity. The same form is used by a PR or DI to resign. The instructions say a valid designation automatically revokes an existing PR designation and DI appointment.
The form belongs to the centralized partnership audit regime of the Bipartisan Budget Act of 2015. The instructions call partnerships under it BBA partnerships and say all partnerships with tax years beginning after 2017 are BBA partnerships unless they make a valid election out. The PR is first designated on the partnership's return for the tax year. Form 8979 is for the later situations the instructions list, such as an IRS exam or an administrative adjustment request (AAR).
This page covers the September 2025 revision, which the instructions say was retitled and cut to two reasons for filing. You can fill out the PDF free in your browser on this page and download it without an account.
Name of partnership, employer identification number, address, tax year ending date, and a box to check when the form is filed with an administrative adjustment request on Form 8082 or Form 1065-X.
Two boxes. Line 1 is a designation of an individual PR, or of an entity PR with an appointed DI, which revokes any prior designation. Line 2 is a resignation by the PR or DI.
Name, taxpayer identification number, street address, city, state or province, country code, ZIP or postal code and phone number for the PR being designated, then the same lines for the designated individual.
Name, taxpayer identification number, U.S. street address, city, state, ZIP code and U.S. area code and telephone number of the PR or DI who is resigning.
Section A is signed by the authorized person for a designation, under penalties of perjury, with a printed name and, for an entity, the name and title of the individual who signs. Section B is signed by the resigning PR or DI.
Enter the partnership's name, address, EIN and the ending date of the tax year the designation or resignation applies to. The instructions say to use a P.O. box only if the post office does not deliver to the street address, and to check the box above Part I when filing with an AAR.
Check line 1 to designate a PR, and appoint a DI for an entity PR, or line 2 to resign as PR or DI. The form says line 1 leads to Part II and Section A, and line 2 leads to Part III and Section B.
For an individual PR, enter the PR's name, U.S. mailing address, TIN and a phone number with a U.S. area code, and leave the DI lines blank. For an entity PR, fill in both the PR and DI lines. The instructions say an entity PR designation without a DI is invalid.
Only for a resignation. The resigning PR or DI enters their name, mailing address, TIN and telephone number.
The authorized person signs, dates and prints their name. If the authorized person is an entity, the third line holds the name and title of the individual who can legally bind it, such as a corporation's president in the instructions' example.
The resigning PR or DI signs and dates, then enters their name followed by their role. The instructions' examples use wording such as "resigning Partnership Representative of GHI Partnership."
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions list specific situations: to the IRS employee point of contact after Letter 2205-D, Letter 5893 or Letter 5893-A; with an AAR; with Form 8985; with Form 8988; or with a request that requires the partnership to extend a statute.
The instructions say a resignation goes directly to the current IRS employee point of contact, and only after Letter 2205-D, Letter 5893 or Letter 5893-A is issued.
With an AAR, the instructions point to How to file an AAR at IRS.gov/BBAAAR. Otherwise the form is mailed or faxed to the attention of the current IRS employee point of contact, such as a revenue agent, appeals officer or counsel.
The instructions say that if the IRS notifies the partnership that no designation is in effect, the partnership has 30 days from the date the IRS mails the notification to submit Form 8979. Otherwise the IRS designates a PR and appoints a DI, if applicable.
The instructions say address information on Form 8979 does not change the last known address with the IRS. They point to Form 8822 for a home address and Form 8822-B for a business address.
The instructions say a new PR who wants a person to represent it as power of attorney submits Form 2848, even if a prior PR appointed that person for the same tax year.

1065
440 fields, 6 pages
8082
59 fields, 2 pages
1065-X
227 fields, 4 pages

2848
92 fields, 2 pages
8822
25 fields, 2 pages
8822-B
22 fields, 2 pages
The instructions name two kinds of filers: the partnership, acting through an authorized person, and a PR or DI who is resigning. The form goes to the IRS, not to the partners.
No tool matches that search.
No. The instructions say a partnership designates a PR on the return it files for the partnership tax year. Form 8979 is used in the later situations they list, such as an exam, an AAR, Form 8985 or Form 8988.
The instructions say there can be only one designated PR at any time during the partnership tax year. A valid new designation revokes the prior one.
Yes. The instructions say a partnership may designate any person, including an entity or itself. An entity PR needs a designated individual appointed at the same time, or the designation is invalid.
The instructions say no PR designation is then in effect and the IRS asks the partnership to designate one. If none is made within 30 days of that request, the IRS makes the designation.
An authorized person, which the instructions define as someone who was a partner at any time during the tax year involved. If that partner is an entity, an individual who can legally bind it under state law signs.
No. The instructions say the address on Form 8979 does not change the last known address. They point to Form 8822 or Form 8822-B for that.