Items A to G
The beneficiary's name and Social Security number, the trust's name, address and EIN, the type of trust (domestic or foreign), the beneficiary's date of birth, and the number of trusts that made accumulation distributions this year.
4970
Tax on Accumulation Distribution of Trusts
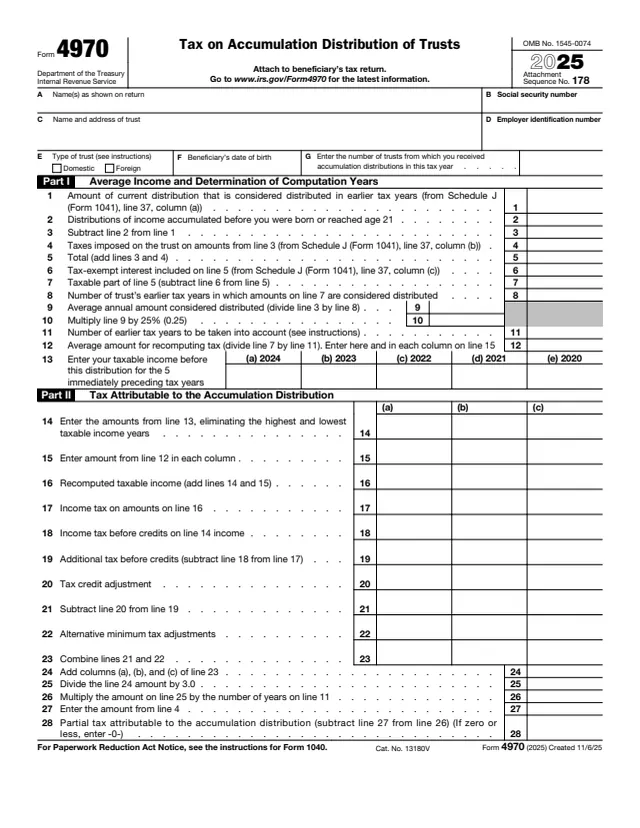
Form 4970, Tax on Accumulation Distribution of Trusts, is attached to a beneficiary's tax return. The IRS About page says a beneficiary of certain domestic trusts uses this form to figure the partial tax on accumulation distributions under section 667.
An accumulation distribution comes from a trust that accumulated its income instead of distributing it each year and paid taxes on that income. The instructions say the trustee notifies the beneficiary by completing Part IV of Schedule J (Form 1041) and gives the beneficiary a completed Part IV, which supplies the numbers for this form. The form spreads the distribution over earlier tax years and recomputes the tax for three of the five preceding years.
This is the 2025 version of the form, and its instructions are printed on page 2. You can fill out Form 4970 free in your browser on this page and download the result without an account.
The beneficiary's name and Social Security number, the trust's name, address and EIN, the type of trust (domestic or foreign), the beneficiary's date of birth, and the number of trusts that made accumulation distributions this year.
Average income and determination of computation years: the distribution, taxes the trust paid, tax-exempt interest, the number of earlier years, and the average amount for recomputing tax.
Taxable income before this distribution for the 5 immediately preceding tax years, in columns for 2024, 2023, 2022, 2021 and 2020.
Tax attributable to the accumulation distribution, figured in three columns: recomputed taxable income, income tax before and after, a tax credit adjustment and alternative minimum tax adjustments.
The three columns are added, averaged, multiplied by the number of years, and reduced by the trust's taxes to give the partial tax on line 28.
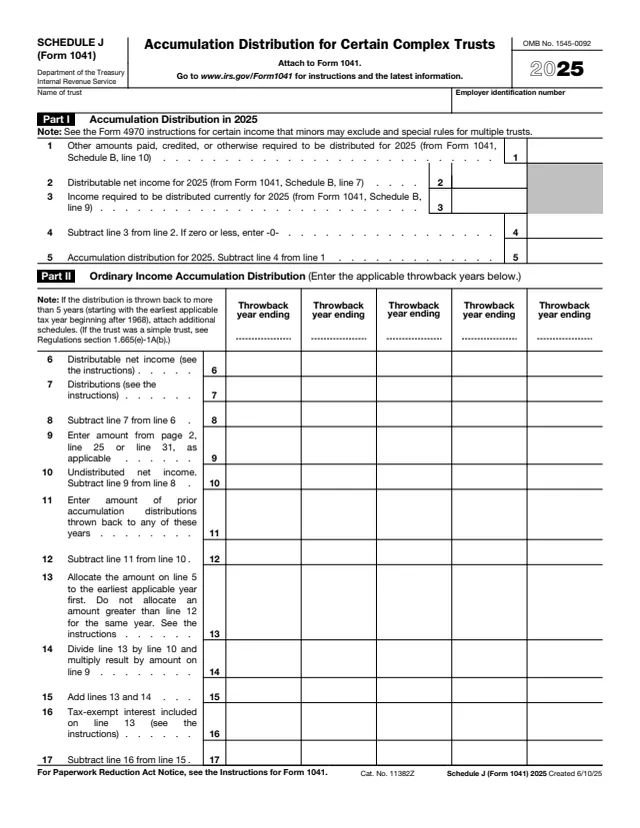
Lines 1, 4 and 6 come from Schedule J (Form 1041), line 37, columns (a), (b) and (c). Line 2 is any amount accumulated before the beneficiary was born or reached age 21. For a nonresident alien or foreign corporation, line 1 includes only the U.S. source or effectively connected part.
Line 8 counts the throwback years with entries on lines 32 through 36 of Part IV of Schedule J (Form 1041); there can be more than 5. Line 11 drops any year whose distribution in column (a) is less than line 10.
Enter taxable income for 2020 to 2024 as reported or as changed by the IRS, and zero if it is less than zero. Line 14 keeps three years, eliminating the highest and lowest. Line 15 repeats the line 12 amount in each column, and line 16 adds lines 14 and 15.
Figure the tax on line 16 with the tax rates for each earlier year, and enter the tax as originally reported on line 18. Line 20 holds any increase in limited credits. For line 22, the instructions say to use and attach that year's Form 4626, Form 6251 or Schedule I (Form 1041).
Add the three columns of line 23, divide by 3.0, multiply by the years on line 11, and subtract line 4. If zero or less, enter -0-. If estate or generation-skipping transfer taxes apply, the instructions say to reduce the partial tax proportionately.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the beneficiary's tax return for the year of the accumulation distribution.
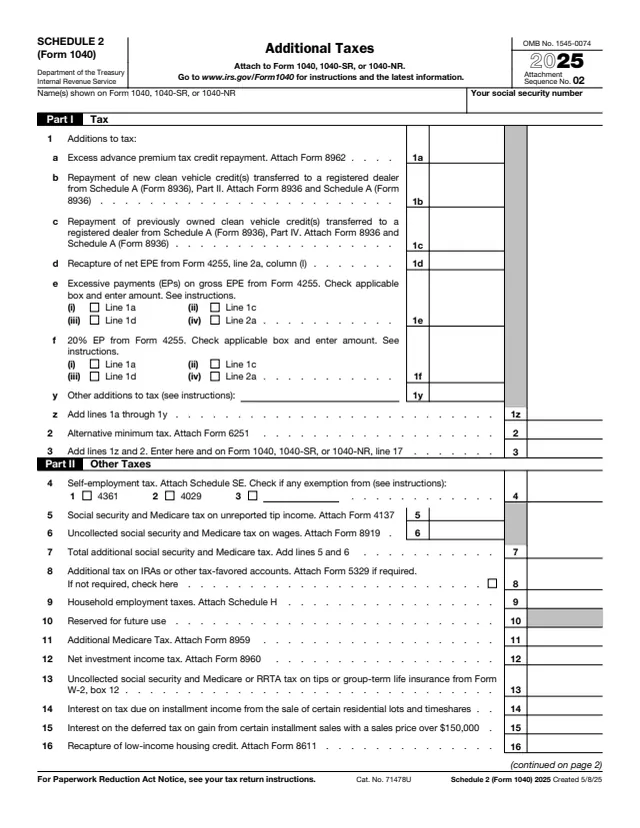
The instructions say to include the line 28 amount on Schedule 2 (Form 1040), line 17l.
Include the amount on Form 1041, Schedule G, line 8, and write "From Form 4970" and the amount of the tax to the left of the line 8 entry space.
Add the result to the total tax liability before the refundable credits on the income tax return for the year of the accumulation distribution.
For line 4, the instructions count only trusts whose current and earlier accumulation distributions considered made in the same earlier years total $1,000 or more.
1041
174 fields, 2 pages

1041
173 fields, 3 pages
3520
462 fields, 6 pages
1040
63 fields, 2 pages
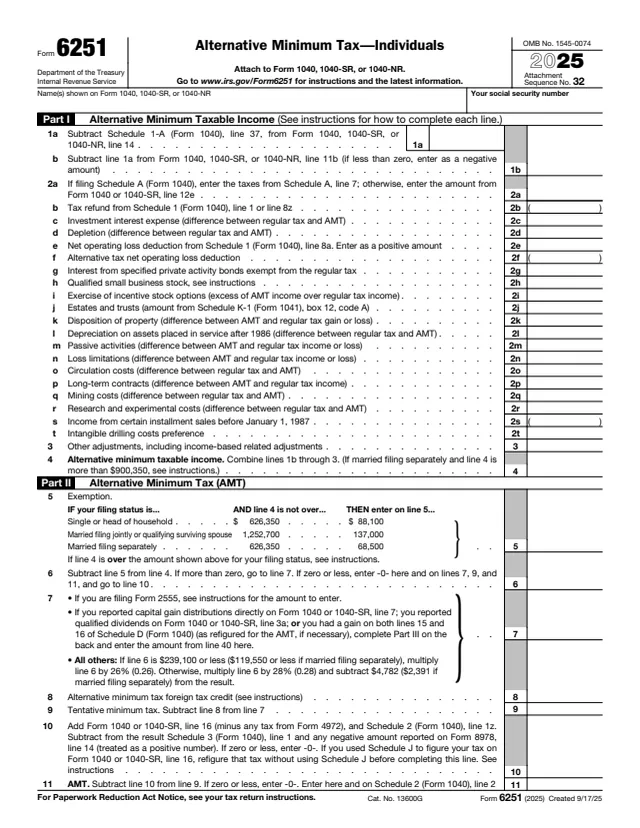
6251
62 fields, 2 pages

1040
199 fields, 2 pages
The beneficiary who received the accumulation distribution completes the form and attaches it to their own return. The trustee supplies the figures on Schedule J (Form 1041).
No tool matches that search.
A beneficiary who received an accumulation distribution from certain domestic trusts created before March 1, 1984. It is attached to the beneficiary's own return.
The trustee gives the beneficiary a completed Part IV of Schedule J (Form 1041). Lines 1, 4 and 6 come from line 37 of that schedule.
The instructions say the distribution and partial tax are reported on a 2025 Form 3520, and Form 4970 is used only as a worksheet attached to Form 3520 if those instructions direct it.
No. The instructions say to prepare a separate Form 4970 for each trust that made an accumulation distribution.
Taxable income for 2020 through 2024, the 5 tax years before 2025, even if fewer than 5 years of the trust had accumulated income after the beneficiary became 21.
On Schedule 2 (Form 1040), line 17l, according to the instructions.