Part I: General Information
The trust's name, EIN, address and creation date, whether it appointed a U.S. agent, the trustee, and the number of owner and beneficiary statements included.
3520-A
Annual Information Return of Foreign Trust With a U.S. Owner (Under section 6048(b))
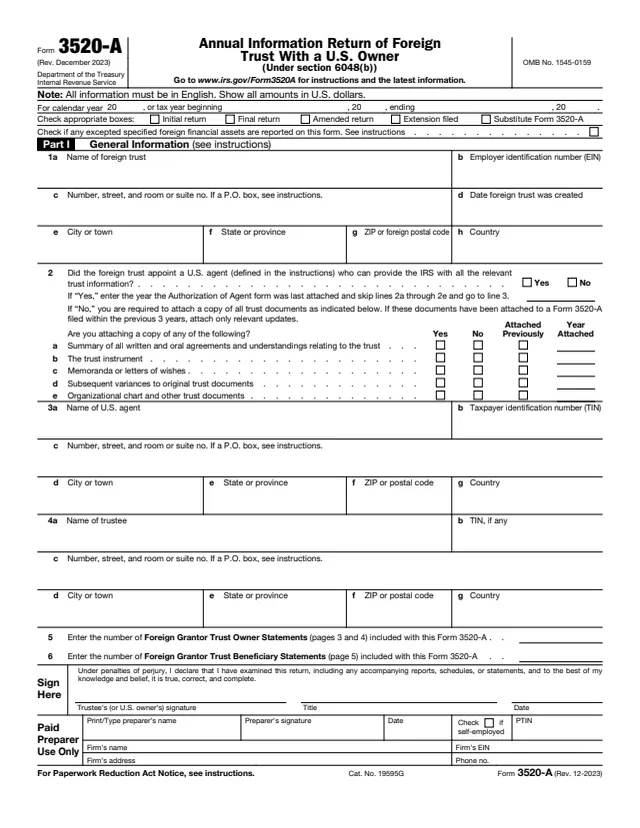
Form 3520-A is the annual information return of a foreign trust with at least one U.S. owner. The instructions say it provides information about the foreign trust, its U.S. beneficiaries, and any U.S. person treated as an owner of any portion of the trust under the grantor trust rules (sections 671 through 679).
The foreign trust files the form and its trustee signs it. Each U.S. owner is responsible for ensuring that the trust files it and furnishes the annual statements. If the trust does not file, the U.S. owner completes a substitute Form 3520-A and attaches it to the owner's Form 3520. The return holds an income statement, a balance sheet, a Foreign Grantor Trust Owner Statement for each U.S. owner and a Foreign Grantor Trust Beneficiary Statement for each U.S. beneficiary who received a distribution.
The form says all information must be in English and all amounts in U.S. dollars. You can fill out Form 3520-A free in your browser on this page and download the result without an account.
The trust's name, EIN, address and creation date, whether it appointed a U.S. agent, the trustee, and the number of owner and beneficiary statements included.
Lines 1 to 16 for income and expenses from the trust's books and records, and line 17 for distributions to all persons, U.S. owners and U.S. beneficiaries.
Assets, liabilities and net worth at the beginning and end of the tax year.
Pages 3 and 4, one per U.S. owner: trust and owner details, the gross value of the owner's portion, distributions, and the trust income attributable to the owner.
Page 5, one per U.S. beneficiary who received a distribution, with amounts distributed, loaned or used without compensating the trust.
The trustee's signature, or the U.S. owner's on a substitute, on page 1 and on each statement, plus a Paid Preparer Use Only section.
Fill in the calendar year or the fiscal year dates. Check initial, final, amended, extension filed or substitute Form 3520-A as it applies.
Enter the trust's EIN (not an SSN or ITIN), name and address. On line 2, Yes means entering the year the Authorization of Agent form was last attached; No means attaching the listed trust documents.
Enter the number of owner statements and beneficiary statements included. The trustee, or the U.S. owner for a substitute, signs.
Report all income from U.S. and non-U.S. sources, and list all trust assets and liabilities at fair market value. Attach the statements that lines 7, 10a, 14 and 17a ask for.
Prepare a separate statement for each U.S. owner and for each U.S. beneficiary who received a distribution, with the tax year at the top. Include copies with the return and send each person theirs.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
By the 15th day of the 3rd month after the end of the trust's tax year. A substitute Form 3520-A is due the same day as the U.S. owner's Form 3520.
File Form 7004 using the trust's EIN by that date. The instructions say an extension of time to file an income tax return does not extend the time to file Form 3520-A.
Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409. A substitute Form 3520-A goes with the U.S. owner's Form 3520.
The instructions say only a complete Form 3520-A, including all required attachments, is considered timely filed.
The U.S. owner faces an initial penalty of the greater of $10,000 or 5% of the gross value of its portion of trust assets if the trust files late or with missing or incorrect information. Reasonable cause can avoid it.
U.S. owners and beneficiaries who treat items on their returns differently from the trust's Form 3520-A file Form 8082, the instructions say.
3520
462 fields, 6 pages

7004
26 fields, 1 page
8938
131 fields, 2 pages
8082
59 fields, 2 pages
4972
58 fields, 4 pages
8949
202 fields, 2 pages
The foreign trust files it, not an individual taxpayer. A U.S. owner fills it out only as a substitute when the trust does not file.
No tool matches that search.
The trustee of the foreign trust. A substitute Form 3520-A is signed by the U.S. owner, whose name and TIN go on the Title line of the signature box.
The instructions say the U.S. owner completes a substitute Form 3520-A, to the best of its ability, and attaches it to its own Form 3520 by the Form 3520 due date.
By the 15th day of the 3rd month after the end of the trust's tax year, unless an extension is granted. The owner and beneficiary statements go out by the same date.
No. The instructions say an income tax return extension does not extend Form 3520-A. Form 7004, filed with the trust's EIN, requests that extension.
A U.S. person with a binding contract to act as the trust's authorized agent for IRS requests for records or testimony and summonses under sections 7602, 7603 and 7604. Without one, the trust attaches its trust documents.
No. Form 3520-A is the foreign trust's own return. Form 3520 is filed by U.S. persons, and a U.S. owner attaches its Foreign Grantor Trust Owner Statement to it.