Part I: general information
The recipient's name, SSN or ITIN, or trust EIN, address and fiduciary, then Yes/No questions on lines 7 to 16 that point to the parts to complete.
708
United States Return of Tax for Gifts and Bequests Received From Covered Expatriates
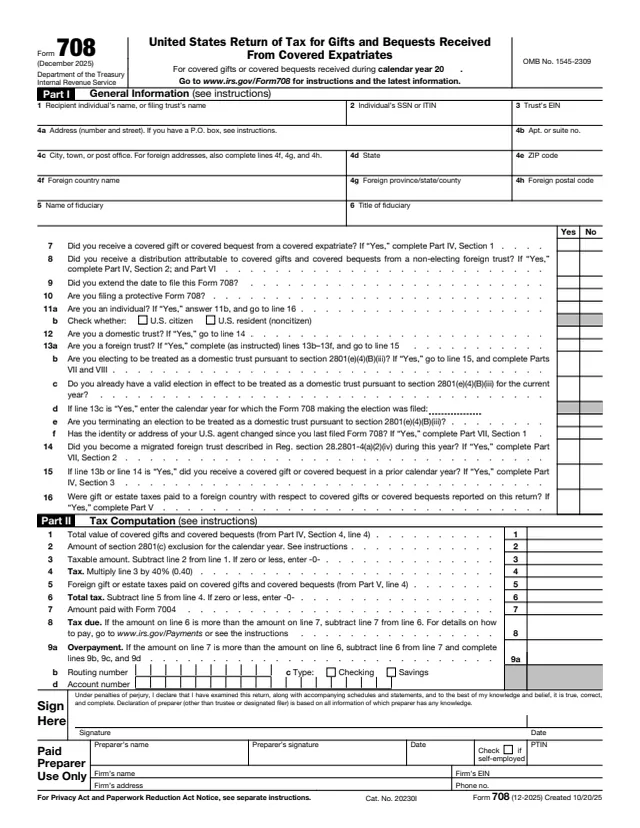
Form 708 is the United States Return of Tax for Gifts and Bequests Received From Covered Expatriates. The form says it covers covered gifts or covered bequests received during one calendar year, and it is completed by the recipient: an individual, with boxes for a U.S. citizen or a U.S. resident (noncitizen), or a trust.
Part II figures the tax. It starts from the total value of covered gifts and covered bequests, subtracts the section 2801(c) exclusion for the calendar year, multiplies the result by 40% (0.40), and subtracts foreign gift or estate taxes paid on those gifts and bequests.
This is the December 2025 edition of the form. The form says to go to www.irs.gov/Form708 for instructions and the latest information. You can fill out the PDF free in your browser on this page and download the result without an account.
The recipient's name, SSN or ITIN, or trust EIN, address and fiduciary, then Yes/No questions on lines 7 to 16 that point to the parts to complete.
Total covered gifts and bequests, the section 2801(c) exclusion, tax at 40%, foreign taxes, any amount paid with Form 7004, tax due or overpayment with direct deposit fields.
The name, expatriation date, identifying number and, if deceased, date of death of each covered expatriate the gifts or bequests came from.
Section 1 lists gifts and bequests received, Section 2 lists distributions from non-electing foreign trusts, Section 3 covers prior-year receipts of electing and migrated foreign trusts, and Section 4 totals them.
Part V lists foreign gift or estate taxes paid for each item. Part VI figures the section 2801 ratio for each non-electing foreign trust that made a distribution.
Part VII holds the U.S. agent, prior distributions to U.S. recipients and permissible distributees. Part VIII is the declaration of a foreign trustee electing domestic treatment.
Enter the calendar year at the top, the recipient's or trust's name, the SSN or ITIN for an individual or the EIN for a trust, and the address. A trust also names its fiduciary and the fiduciary's title.
Each Yes points to more work: line 7 to Part IV, Section 1; line 8 to Part IV, Section 2 and Part VI; line 13b to Parts VII and VIII; line 16 to Part V. Line 11a sends an individual to line 16.
In Part III, enter each covered expatriate. In Part IV, Section 1, enter covered gifts and covered bequests in the order received, with the date of receipt, a description and the value.
If foreign gift or estate taxes were paid, complete Part V for each item. For a distribution from a non-electing foreign trust, complete Part VI for that trust before Part IV, Section 2.
Carry the Part IV, Section 4 total to Part II, line 1. Subtract the line 2 exclusion, multiply line 3 by 40% (0.40), subtract foreign taxes and any amount paid with Form 7004.
The filer signs under penalties of perjury. A paid preparer completes the preparer block. A foreign trust electing domestic treatment also completes Part VIII.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form header says it is for covered gifts or covered bequests received during one calendar year.
The form prints no due date and no mailing address. It says to go to www.irs.gov/Form708 for instructions and the latest information.
Part II, line 8 says that for details on how to pay, go to www.irs.gov/Payments or see the instructions.
Line 9 asks whether the date to file this Form 708 was extended, and line 10 asks whether this is a protective Form 708. Part II, line 7 subtracts any amount paid with Form 7004.
Part VII, line 10 asks whether the U.S. agent was designated by filing Form 2848, and line 11 asks for the date it was filed. The form says that if not, a valid designation has not been made.
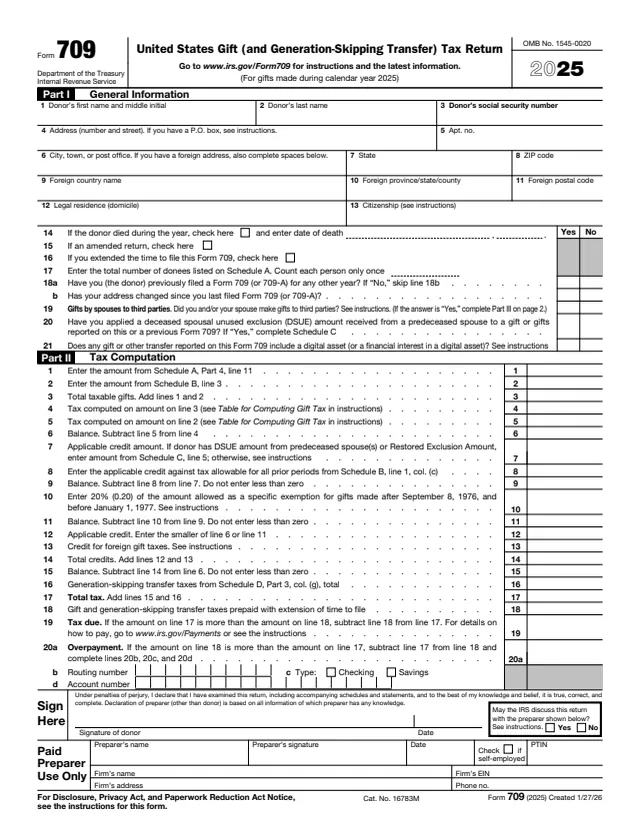
709
1,851 fields, 10 pages
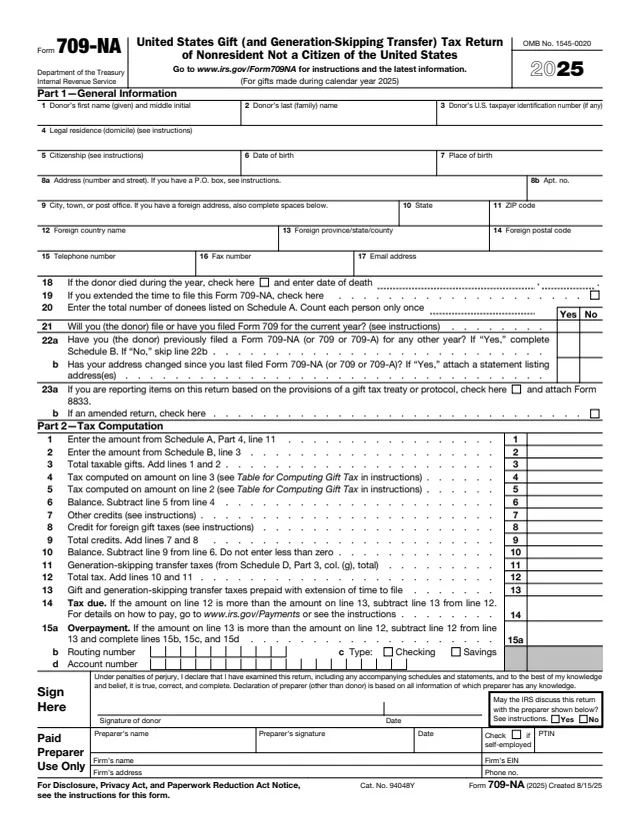
709-NA
889 fields, 8 pages

7004
26 fields, 1 page

2848
92 fields, 2 pages

706
316 fields, 5 pages
The form is completed by the recipient of the covered gift or covered bequest, not by the expatriate who gave it.
No tool matches that search.
The recipient. Part I asks for the recipient individual's name, or the filing trust's name, and the form lists the covered expatriate donor or decedent separately in Part III.
Part II, line 4 says to multiply the taxable amount on line 3 by 40% (0.40).
Part II, line 2 subtracts the amount of the section 2801(c) exclusion for the calendar year. The form does not print the amount and refers to the instructions.
Yes. Line 16 asks whether such taxes were paid, Part V lists them per item, and Part II, line 5 subtracts the total from the tax.
The form has lines for a foreign trust electing to be treated as a domestic trust under section 2801(e)(4)(B)(iii). Its trustee signs the declaration in Part VIII.