Tax year and records box
Calendar year or tax year dates, and a box to check if the partnership keeps its records and books of account outside the United States and Puerto Rico.
8804
Annual Return for Partnership Withholding Tax (Section 1446)
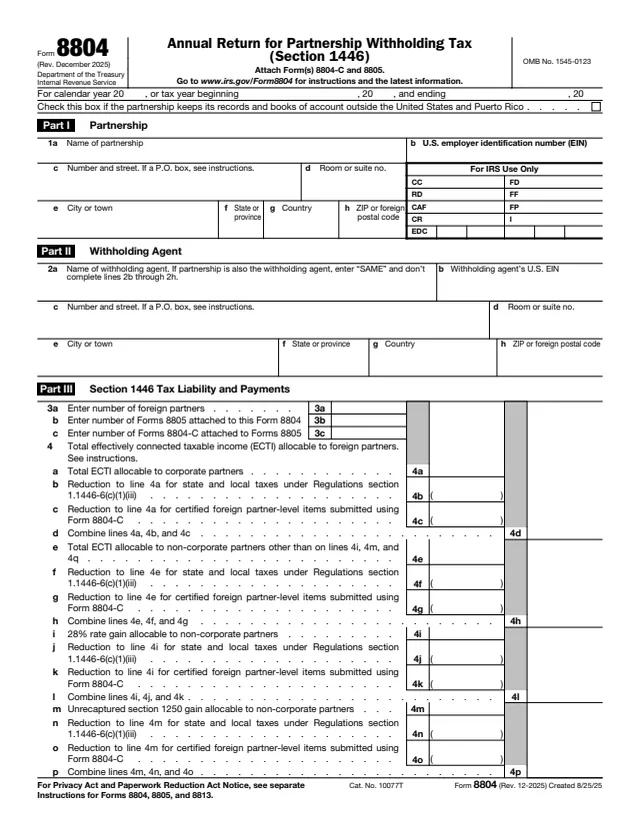
Form 8804 is the Annual Return for Partnership Withholding Tax (Section 1446). The IRS says to use it to report the total liability under section 1446 for the partnership's tax year. Form 8804 is also a transmittal form for Form(s) 8805.
Section 1446 withholding tax is based on effectively connected taxable income (ECTI) allocable to foreign partners. The form reports the partnership and any withholding agent, the number of foreign partners, ECTI by income type, the gross tax at the rates printed on the form, payments and credits, and any balance due or overpayment. The form says to attach Form(s) 8804-C and 8805.
This is a partnership return, filed by the partnership or a person it designates, not by the foreign partners. You can fill out Form 8804 free in your browser on this page and download the result without an account.
Calendar year or tax year dates, and a box to check if the partnership keeps its records and books of account outside the United States and Puerto Rico.
Lines 1a to 1h: name of partnership, U.S. employer identification number and address.
Lines 2a to 2h: the withholding agent's name, U.S. EIN and address. If the partnership is also the withholding agent, enter SAME and skip lines 2b through 2h.
Counts of foreign partners, Forms 8805 and Forms 8804-C, then ECTI allocable to foreign partners by type, each with reductions for state and local taxes and for items certified on Form 8804-C.
Lines 5a to 5e multiply the ECTI totals by 21% (0.21), 37% (0.37), 28% (0.28), 25% (0.25) and 20% (0.20), and line 5f adds them.
Payments and credits from Forms 8805, 1042-S and 8288-A, the estimated tax penalty, balance due or overpayment, amounts allocated to partners, refund and direct deposit details, and credit to next year.
Enter the partnership's name, EIN and address, including any suite or room number. Enter SAME on line 2a if the partnership is its own withholding agent.
Enter the number of foreign partners, the total number of Forms 8805, Copy A, attached, and the number of Forms 8804-C attached to Forms 8805.
Enter ECTI allocable to foreign partners by income type on lines 4a, 4e, 4i, 4m and 4q, with no negative numbers, then the reductions and the combined totals.
Multiply each total by the rate on its line and add them on line 5f. Enter payments and credits on lines 6a to 6g; the instructions say to attach the Form 8805, 1042-S or 8288-A behind any credit claimed.
Check line 8 and enter any penalty if Schedule A (Form 8804) is attached. Figure the balance due or overpayment, any part allocated to partners on line 12, and the refund or credit to next year.
A partner or LLC member signs, with title and date. A paid preparer, if any, completes the Paid Preparer Use Only section.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to generally file Forms 8804 and 8805 on or before the 15th day of the 3rd month following the close of the partnership's tax year.
For partnerships that keep their records and books outside the United States and Puerto Rico, the instructions give the 15th day of the 6th month, with the box at the top of the form checked.
The instructions list Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409, and say to file Forms 8804 and 8805 separately from Form 1065.
The instructions name Form 7004 to request more time to file, and say filing Form 7004 does not extend the time for payment.
Installment payments during the year go with Form 8813 or through EFTPS. The instructions say Forms 8804 and 8805 are still filed either way.
The instructions say to complete a new Form 8804, write Amended in the top margin and write Corrected on any attached Forms 8805.
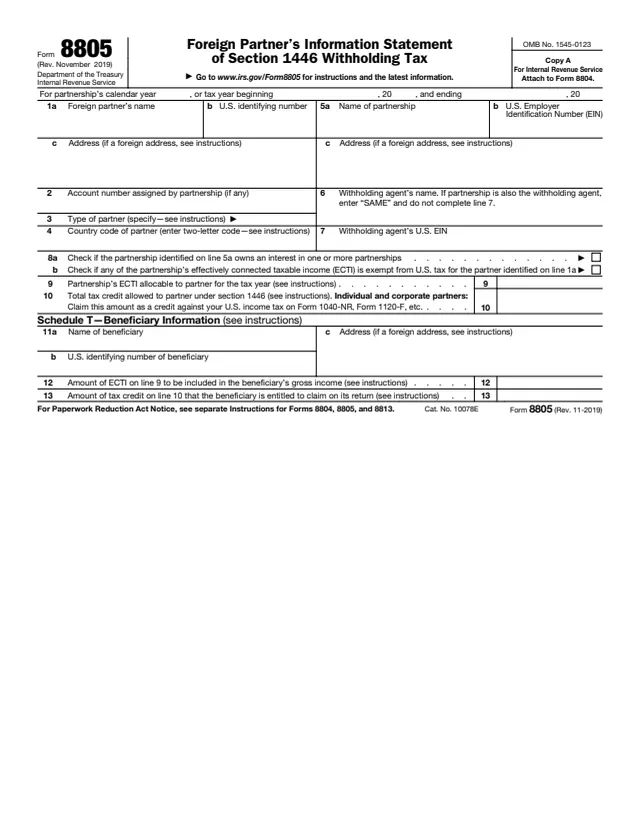
8805
100 fields, 4 pages
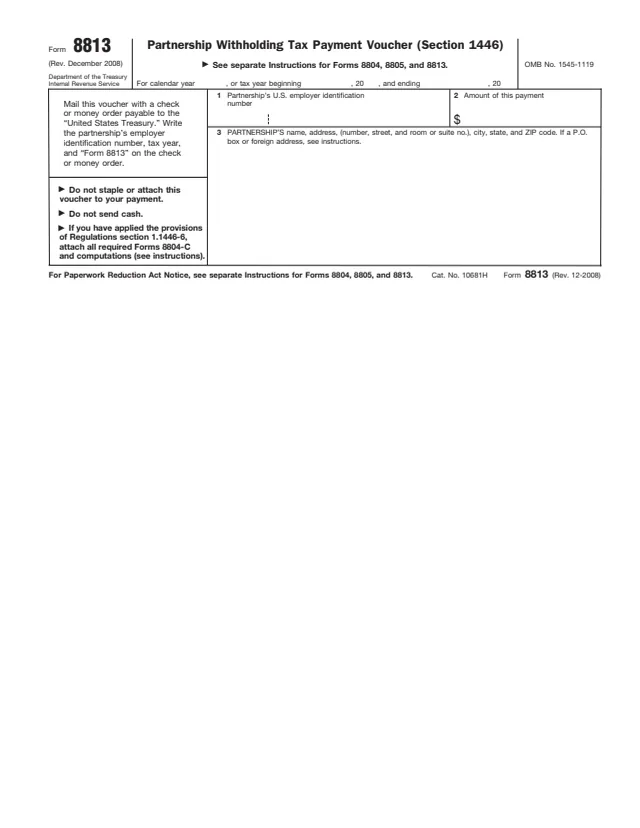
8813
9 fields, 1 page
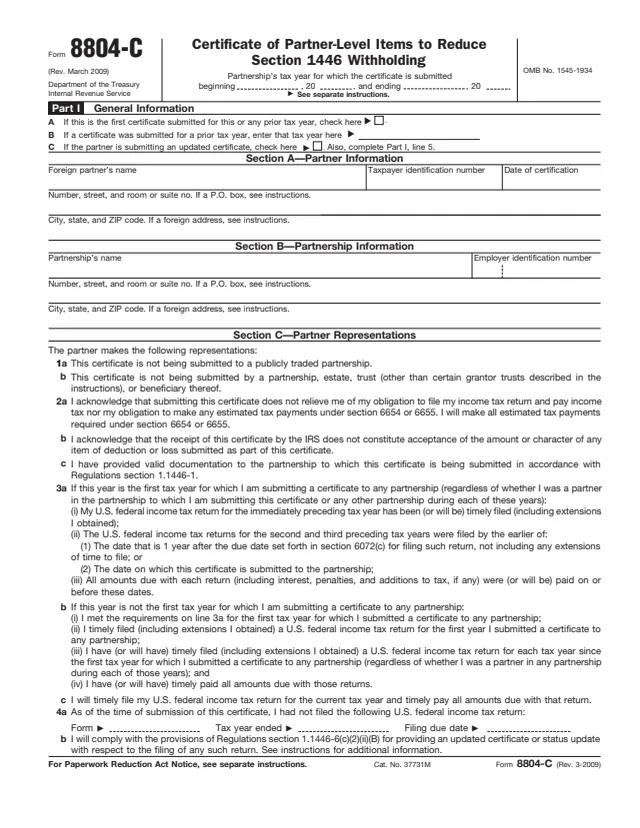
8804-C
46 fields, 3 pages
8804
405 fields, 5 pages

1065
440 fields, 6 pages
8288-A
60 fields, 5 pages
The instructions say every partnership, other than a publicly traded partnership (PTP), that has effectively connected gross income allocable to a foreign partner files Form 8804, regardless of whether it had ECTI allocable to a foreign partner.
No tool matches that search.
The instructions say every partnership, other than a publicly traded partnership, that has effectively connected gross income allocable to a foreign partner, or a person it designates.
No. The instructions say to file Forms 8804 and 8805 separately from Form 1065.
Generally by the 15th day of the 3rd month after the partnership's tax year ends, or the 15th day of the 6th month if its records and books are kept outside the United States and Puerto Rico.
The form says to attach Form(s) 8804-C and 8805. The instructions add that any Form 8805, 1042-S or 8288-A behind a credit on lines 6b to 6g is attached too.
The instructions say Form 8813 accompanies each section 1446 tax payment made during the year, while Form 8804 reports the total liability for the year.
A partner or limited liability company member the partnership designates. A paid preparer also signs and enters a PTIN.