Part I: reasons for filing
Two boxes, one for the adjusted seasonal installment method and one for the annualized income installment method.
8804
Penalty for Underpayment of Estimated Section 1446 Tax by Partnerships
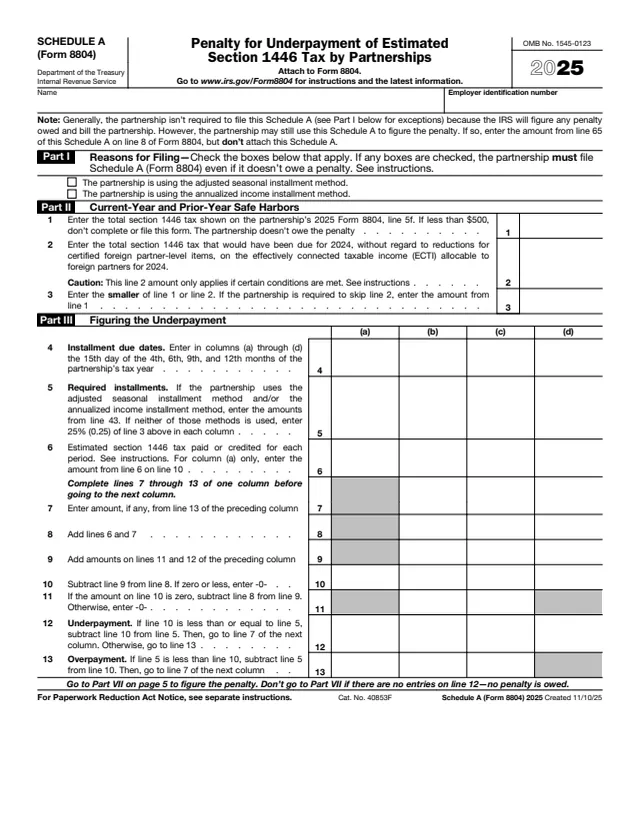
Schedule A (Form 8804), Penalty for Underpayment of Estimated Section 1446 Tax by Partnerships, is a schedule for Form 8804, Annual Return for Partnership Withholding Tax (Section 1446). The IRS About page says partnerships that have effectively connected taxable income (ECTI) allocable to foreign partners use it to determine whether they are subject to the penalty for underpayment of estimated tax and, if so, the amount of the penalty.
The schedule notes that generally the partnership isn't required to file it, because the IRS will figure any penalty owed and bill the partnership. It is attached when the partnership uses the adjusted seasonal installment method or the annualized income installment method. A partnership may also use it only to figure the penalty, enter the result on Form 8804, line 8, and not attach it.
This page has the 2025 schedule. You can fill out Schedule A (Form 8804) free in your browser on this page and download it without an account.
Two boxes, one for the adjusted seasonal installment method and one for the annualized income installment method.
The current-year and prior-year safe harbor amounts, then four installment columns with due dates, required installments, payments, underpayments and overpayments.
ECTI allocable to foreign partners for the 3 prior tax years and the current year by period, base period percentages, and tax at 37% and 21% rates.
Annualized ECTI by type of partner and gain, tax at the printed rates, the applicable percentage, and the required installments carried to line 5.
Days late in each rate period, the underpayment times the rate, and the total penalty on line 65 that goes to Form 8804, line 8.
Enter the partnership's name and EIN. Check one or both Part I boxes that apply. The instructions say to also check the box on Form 8804, line 8.
Enter the 2025 Form 8804, line 5f tax on line 1 and the 2024 amount on line 2 if its conditions are met. Line 3 is the smaller, or line 1 when line 2 is skipped.
Enter the 15th day of the 4th, 6th, 9th and 12th months of the tax year on line 4, then complete lines 7 through 13 of one column before going to the next.
Only for partnerships using an alternative method. The instructions say once Parts IV through VI are used for any due date, they are used for all later due dates.
Go to Part VII only if line 12 shows an underpayment. Count days in each period, apply the rate shown or the quarterly rate marked with an asterisk, and total on line 65.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says "Attach to Form 8804." The penalty from line 65 is entered on Form 8804, line 8.
The instructions say the partnership generally doesn't have to file the schedule because the IRS will figure the penalty and notify the partnership of any amount due.
The instructions say the penalty is figured separately for each installment due date, so a penalty can apply to an earlier date even if enough tax was paid later.
The instructions say it runs from the installment due date to the earlier of the payment date or the 15th day of the 3rd month after the 2025 tax year closes (6th month for books kept outside the United States and Puerto Rico).
The schedule prints 7% for its first rate periods and an asterisk for later ones. It says the IRS publishes those quarterly rates in a news release and a revenue ruling in the Internal Revenue Bulletin.
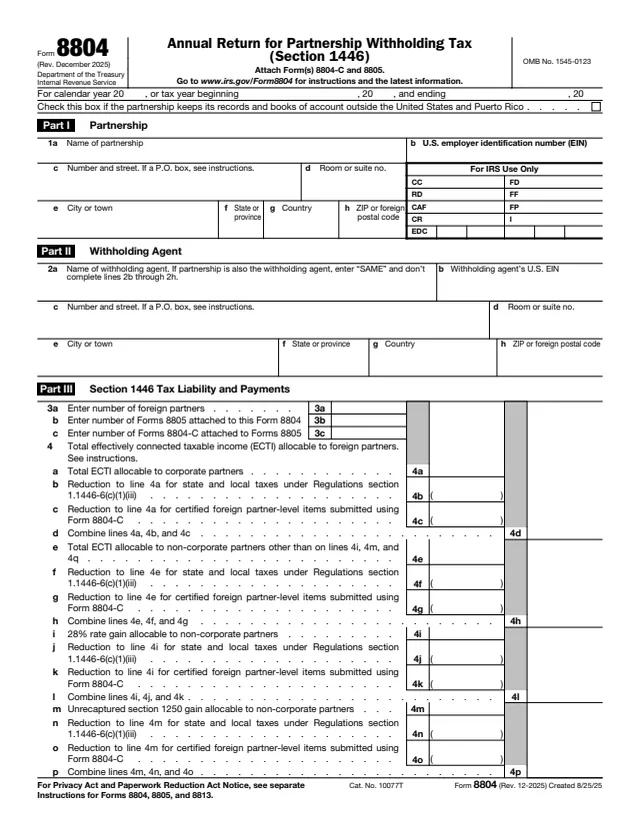
8804
81 fields, 2 pages
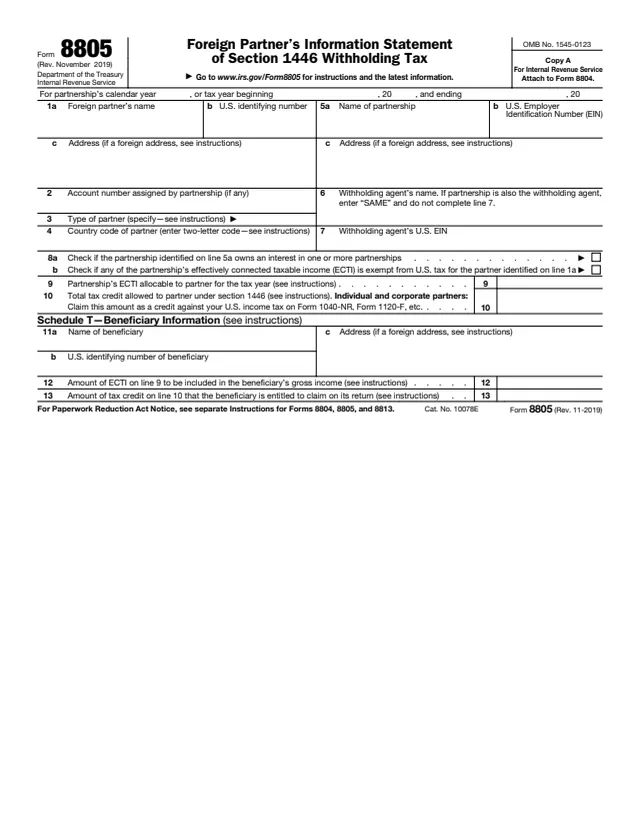
8805
100 fields, 4 pages
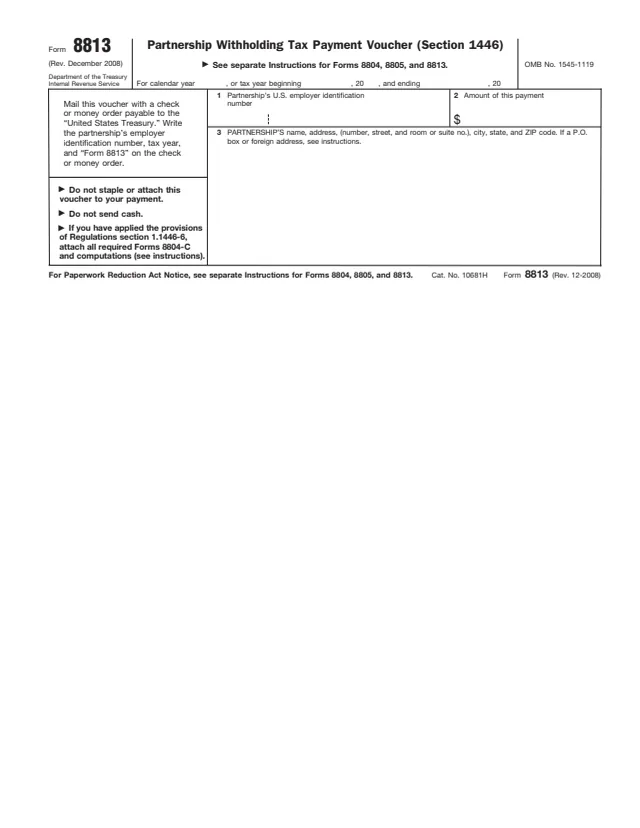
8813
9 fields, 1 page
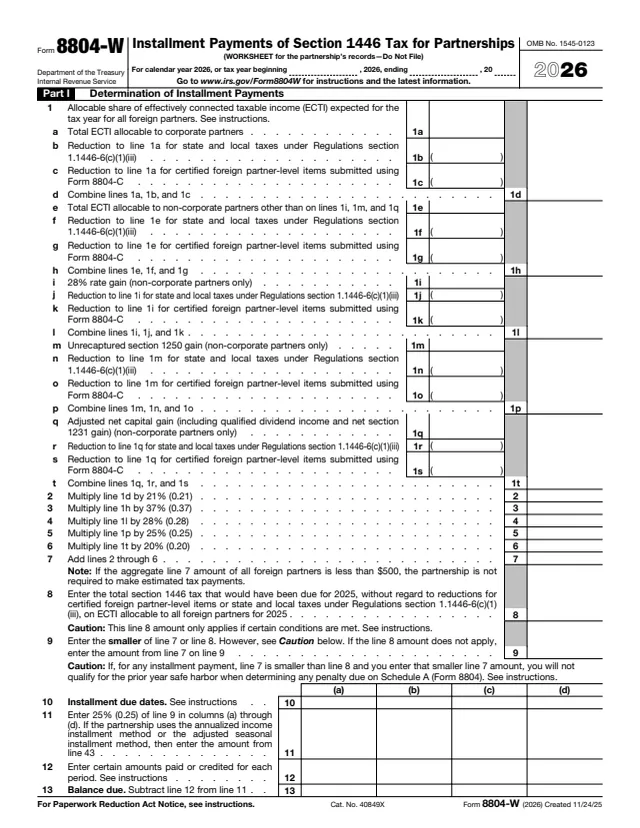
8804-W
319 fields, 4 pages
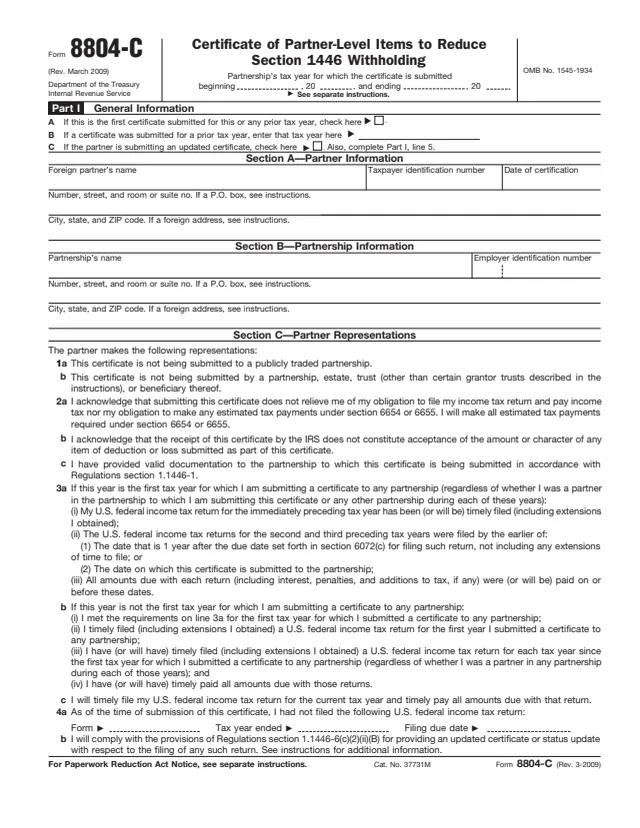
8804-C
46 fields, 3 pages

1065
440 fields, 6 pages
It is a partnership's schedule, not an individual's. The instructions say the partnership attaches it to Form 8804 when Part II, line 1, is $500 or more and it uses the adjusted seasonal or annualized income installment method, even if no penalty is owed.
No tool matches that search.
No. The schedule says that generally the partnership isn't required to file it, because the IRS will figure any penalty owed and bill the partnership. It is attached when a Part I box is checked.
The schedule says that if the total section 1446 tax on Form 8804, line 5f, is less than $500, the form is not completed or filed and the partnership doesn't owe the penalty.
The instructions list conditions, including that the prior tax year was 12 months, a partnership return was timely filed for it, and prior-year ECTI isn't less than 50% of the ECTI on the current-year Form 8804.
The schedule and instructions say it is used only if the base period percentage for any 6 consecutive months of the tax year is 70% or more.
The instructions say Option 1 or Option 2 is used only if the partnership elected it by filing Form 8842 by the due date of the first required installment payment.
Estimated section 1446 tax paid or credited for each period, including a credited prior-year overpayment and certain section 1446, 1445 and 1446(f)(1) amounts withheld, as the instructions describe.