Part I, items A to C
Boxes for a first certificate, the tax year of an earlier certificate, and an updated certificate. The partnership's tax year goes under the title.
8804-C
Certificate of Partner-Level Items to Reduce Section 1446 Withholding
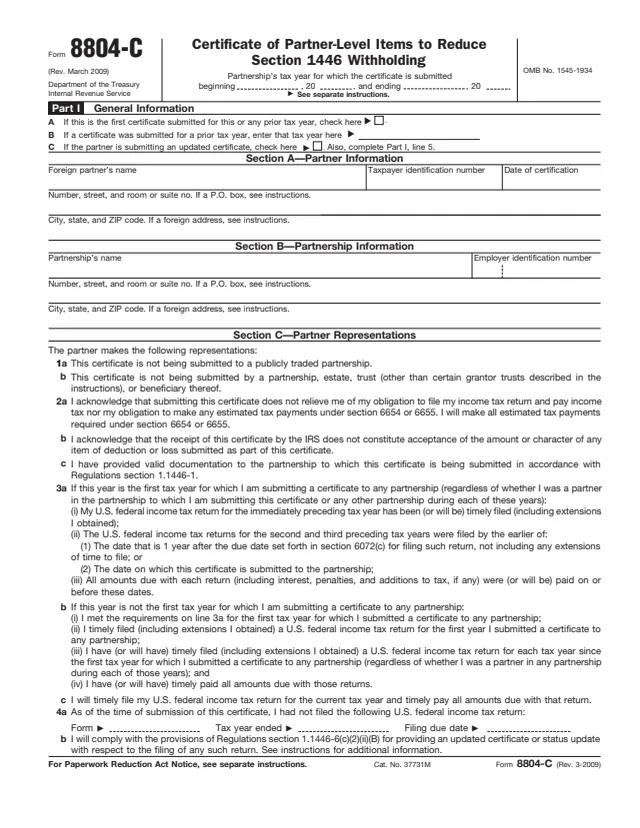
Form 8804-C, Certificate of Partner-Level Items to Reduce Section 1446 Withholding, is used by a foreign partner who chooses to give a partnership a certification under Regulations section 1.1446-6. The certification can reduce or eliminate the partnership's withholding tax under section 1446 (1446 tax) on the partner's allocable share of effectively connected taxable income (ECTI) from the partnership.
The instructions say the foreign partner uses the form to certify partner-level deductions and losses, to certify that its investment in the partnership is its only activity giving rise to effectively connected income, gain, loss, or deduction, or to update a certificate already given for the same tax year.
The foreign partner gives the form to the partnership. The instructions say a foreign partner should not file it with the IRS; only the partnership files it with the IRS. You can fill out the PDF free in your browser on this page and download it without an account.
Boxes for a first certificate, the tax year of an earlier certificate, and an updated certificate. The partnership's tax year goes under the title.
The foreign partner's name, taxpayer identification number, address and date of certification, then the partnership's name, EIN and address.
Partner representations about the partnership type, estimated tax payments, documentation, timely filed prior returns, and any return not yet filed.
Six boxes, 5a to 5f, giving the reason for an updated certificate, such as a return now filed or changed deductions and losses.
Certification of deductions and losses. Line 8 lists net operating loss carryover, capital losses, section 704(d) losses, suspended passive and at-risk losses and other deductions in columns (a) to (c).
Line 12 certifies that the partnership investment is the partner's only activity giving rise to effectively connected items. Part IV holds the disclosure consent and signature.
Enter the tax year of the partnership receiving the certificate; the instructions say to ask the partnership if unsure. Check box A only for a first certificate to any partnership. Line B takes the first tax year of an earlier certificate.
The instructions say an individual enters last name, then first name, and an SSN or ITIN as NNN-NN-NNNN. Other partners enter an EIN as NN-NNNNNNN. The date of certification uses MM/DD/YYYY.
List every return required under line 3a or 3b that has not been filed when the certificate is submitted, with the form, tax year ended and filing due date.
A first certificate for the year fills column (a) only. An updated certificate fills columns (a), (b) and (c). The instructions say to show negative numbers in parentheses.
Attach the statements that lines 5f, 8b, 8d, 8e and 8f ask for. The instructions say the line 8b statement separates short-term from long-term capital losses.
The partner or an authorized representative signs and dates it. The form says that if a representative signs, a copy of the power of attorney must be attached.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The foreign partner gives the form to the partnership, not the IRS. The instructions say only the partnership files Form 8804-C with the IRS.
The instructions say a foreign partner may submit it at any time during the partnership's year and before the partnership files its Form 8804.
For the first installment period it considers the certificate, the partnership attaches a copy to Form 8813. It also attaches the most recent certificate and its 1446 tax computation to Form 8805.
The form says updates for lines 5a, 5d and 5e go to the partnership within 10 days. Updates on lines 5b and 5c go before the partnership's final installment due date of 1446 tax.
The instructions say a partnership relying on the Part III certification need not pay 1446 tax for that partner if it estimates the tax otherwise due is less than $1,000.
The instructions list a blank date of certification, missing attachments, unfiled returns left off line 4a, and an unsigned Part IV or missing power of attorney.
8804
81 fields, 2 pages
8805
100 fields, 4 pages
8813
9 fields, 1 page
8804-W
319 fields, 4 pages
8582
205 fields, 3 pages
6198
34 fields, 1 page
A foreign partner completes the form and gives it to the partnership. The partnership decides whether to consider it and files it with the IRS.
No tool matches that search.
No. The instructions say a foreign partner should not file it with the IRS. The partner gives it to the partnership, and only the partnership files it with the IRS.
The instructions say a partnership is not obligated to consider a Form 8804-C. It may consider it in whole or in part when it figures the 1446 tax for that partner.
The instructions say a foreign partner submits a new Form 8804-C for each tax year in which it chooses to use Regulations section 1.1446-6.
The instructions say a foreign partner may not certify current year deductions and losses, and may not certify charitable contribution deductions.
The form says an updated certificate is required when the facts or representations in the original certificate have changed or a status report is required. Section D lists the reasons.
Line 10 says the amounts have not been certified to another partnership for the same tax year. The instructions say different deductions and losses may go to different partnerships.