Lines 1a to 4: the foreign partner
Partner's name, U.S. identifying number and address, account number assigned by the partnership, type of partner and two-letter country code.
8805
Foreign Partner's Information Statement of Section 1446 Withholding Tax
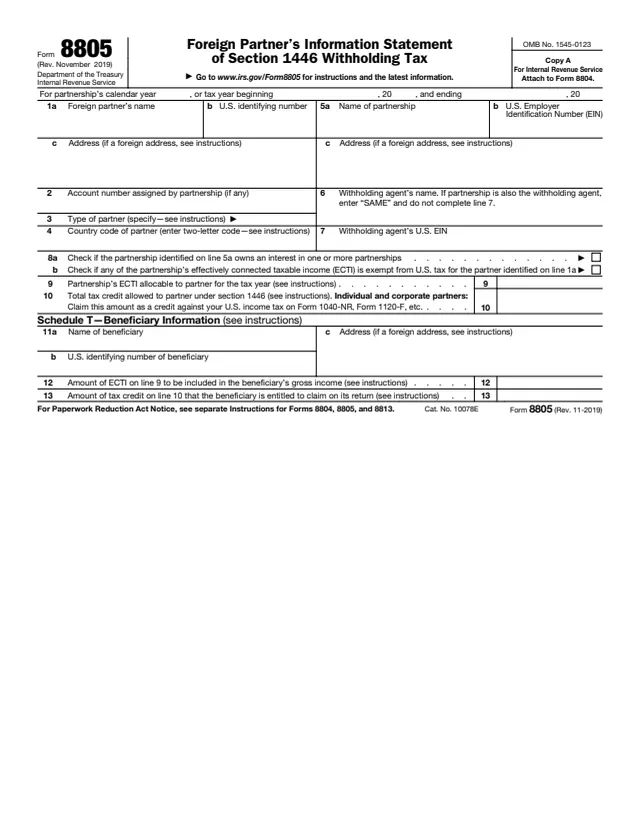
Form 8805 is the Foreign Partner's Information Statement of Section 1446 Withholding Tax. The instructions say it shows the amount of effectively connected taxable income (ECTI) and the total tax credit allocable to a foreign partner for the partnership's tax year, with a separate Form 8805 for each foreign partner.
The partnership, or its withholding agent, prepares the form. Copy A goes to the IRS attached to Form 8804, Copies B and C go to the partner, and Copy D is for the withholding agent. The partner attaches Copy C to its U.S. income tax return, such as Form 1040-NR or Form 1120-F, to claim the credit. A foreign trust or estate that is a partner uses Schedule T on the form to pass the credit on to its beneficiaries.
You can fill out Form 8805 free in your browser on this page and download it without an account.
Partner's name, U.S. identifying number and address, account number assigned by the partnership, type of partner and two-letter country code.
Partnership name, EIN and address, the withholding agent's name and the withholding agent's U.S. EIN.
Line 8a if the partnership owns an interest in one or more partnerships, and line 8b if any of its ECTI is exempt from U.S. tax for the partner.
The partnership's ECTI allocable to the partner for the tax year, and the total tax credit allowed to the partner under section 1446.
Lines 11a to 13 for a foreign trust or estate: the beneficiary's name, identifying number and address, the ECTI to include in the beneficiary's income and the credit the beneficiary can claim.
Four copies of the same page: A for the Internal Revenue Service, B and C for the partner, and D for the withholding agent.
Enter the partnership's tax year, then the partner's name, U.S. identifying number and address. The instructions say the partnership pays the withholding for a foreign partner even without a U.S. TIN for that partner.
On line 3 enter the type, for example individual, corporation, partnership, trust or estate. On line 4 enter the two-letter code from IRS.gov/CountryCodes for the partner's country of tax residence.
Complete lines 5a to 7. If the partnership is its own withholding agent, enter SAME on line 6 and leave line 7 blank.
The instructions say to check it if any ECTI is not allocable to the partner because it is exempt from U.S. tax for that partner by a treaty, reciprocal exemption or a provision of the Internal Revenue Code.
Line 9 is the ECTI allocable to the partner before any reductions. Line 10 is the credit figured by type of ECTI at the applicable percentage, and the instructions say the calculation is attached to the form.
A foreign trust or estate fills in lines 11a to 13 for each beneficiary: the ECTI from line 9 to include in the beneficiary's gross income and the share of the line 10 credit the beneficiary can claim.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Forms 8804, 8805 and 8813 with Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409, with Copy A of each Form 8805 attached to Form 8804.
Generally by the 15th day of the 3rd month after the partnership's tax year ends, or the 15th day of the 6th month for partnerships that keep their records and books of account outside the United States and Puerto Rico.
The instructions say the foreign partner also receives a copy of its Form 8805 by the due date of the partnership return, including extensions.
The instructions say Forms 8804 and 8805 are filed separately from Form 1065, U.S. Return of Partnership Income.
To correct, the partnership files an amended Form 8804 and writes Corrected on any Forms 8805 attached to it.
The instructions say penalties can apply for not filing a correct Form 8805 or not furnishing a correct copy to the recipient. The amounts are found through IRS.gov/InflationAdjustment.
8804
81 fields, 2 pages
8813
9 fields, 1 page
8804-C
46 fields, 3 pages
1040-NR
171 fields, 2 pages
1120-F
527 fields, 9 pages

1065
111 fields, 1 page
The instructions say the partnership, or a person it designates, files Form 8805. The foreign partner receives it and uses it to claim the withholding credit.
No tool matches that search.
The partnership, or a person it designates, files it with Form 8804 and gives copies to the foreign partner. The partner attaches Copy C to its U.S. income tax return to claim the credit.
Yes. The instructions say to file a separate Form 8805 for each foreign partner, and in some cases even when no section 1446 tax was paid.
The form says individual and corporate partners claim the line 10 amount as a credit against U.S. income tax on Form 1040-NR, Form 1120-F, etc.
A foreign trust or estate that is a partner uses Schedule T to report to each beneficiary the ECTI and the section 1446 credit the beneficiary can claim.
The instructions say the partner can't claim an early refund of withholding tax paid under section 1446.
Generally by the 15th day of the 3rd month after the partnership's tax year ends, or the 6th month when books are kept outside the United States and Puerto Rico. A weekend or legal holiday moves it to the next business day.