1120-F

U.S. Income Tax Return of a Foreign Corporation

Agency
IRS
Revision
2025
Fillable fields
527
Pages
9
Official source
IRS form page
Checked
October 21, 2026
Fill 1120-F online
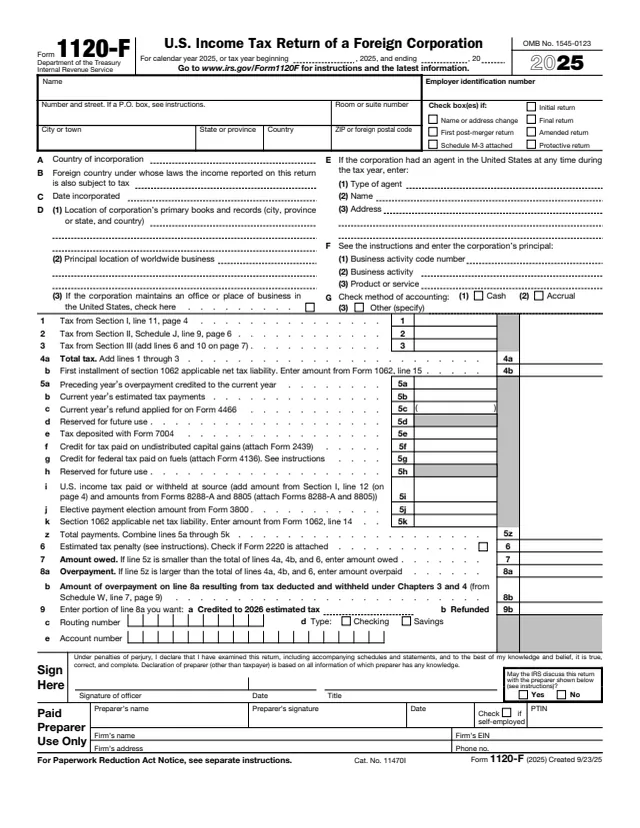
Page 1 of form 1120-F

Form 1120-F: U.S. Income Tax Return of a Foreign Corporation

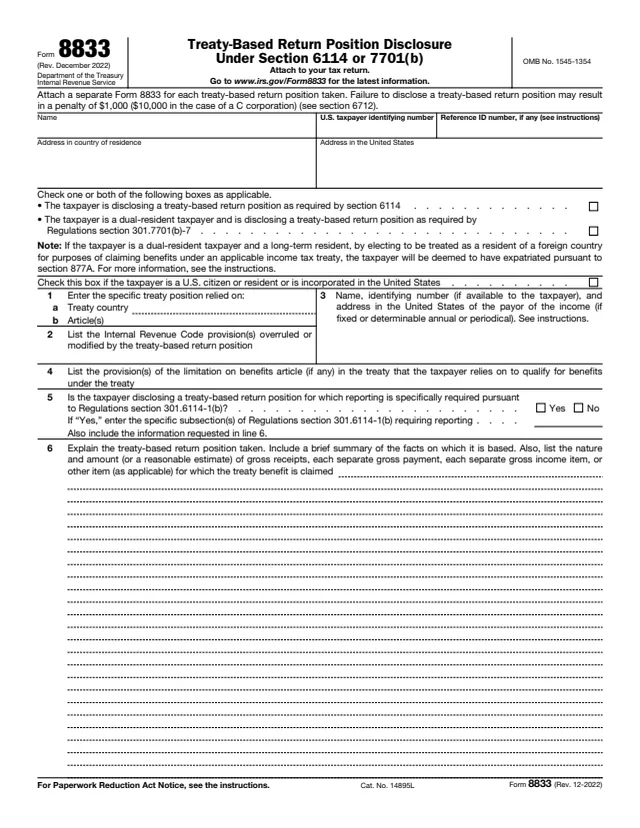
Form 1120-F, U.S. Income Tax Return of a Foreign Corporation, is filed by a foreign corporation to report its income, gains, losses, deductions and credits and to figure its U.S. income tax liability. The instructions say it is also used to claim a refund, to transmit Form 8833, and to figure the branch profits tax and tax on excess interest under section 884.

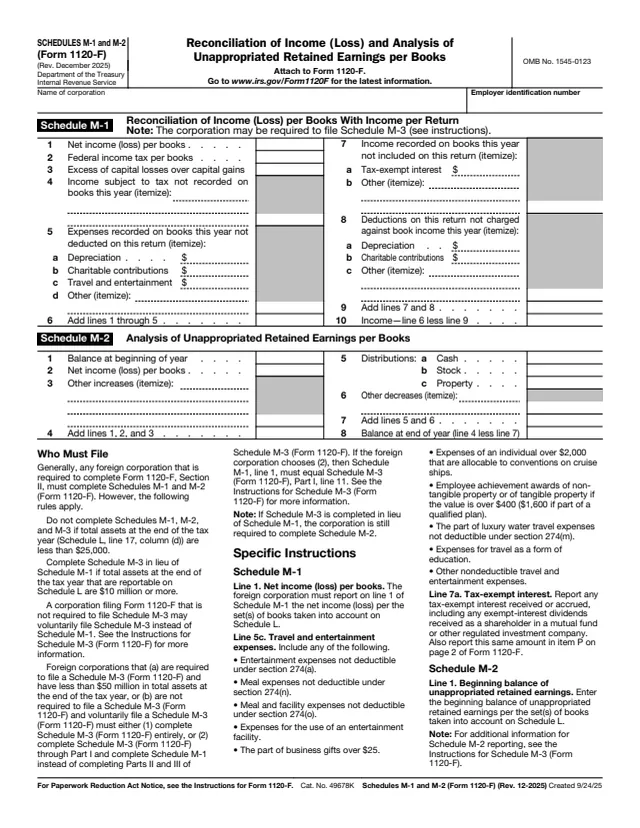
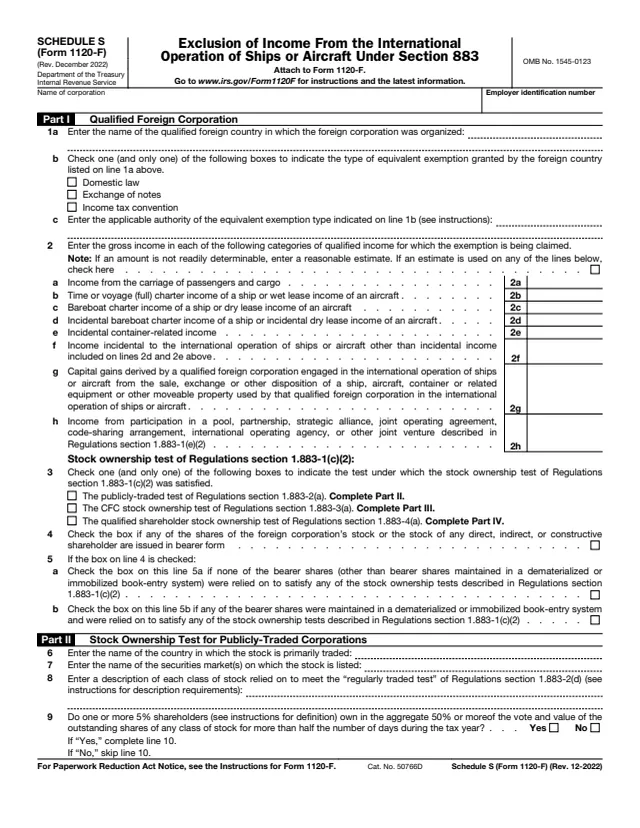
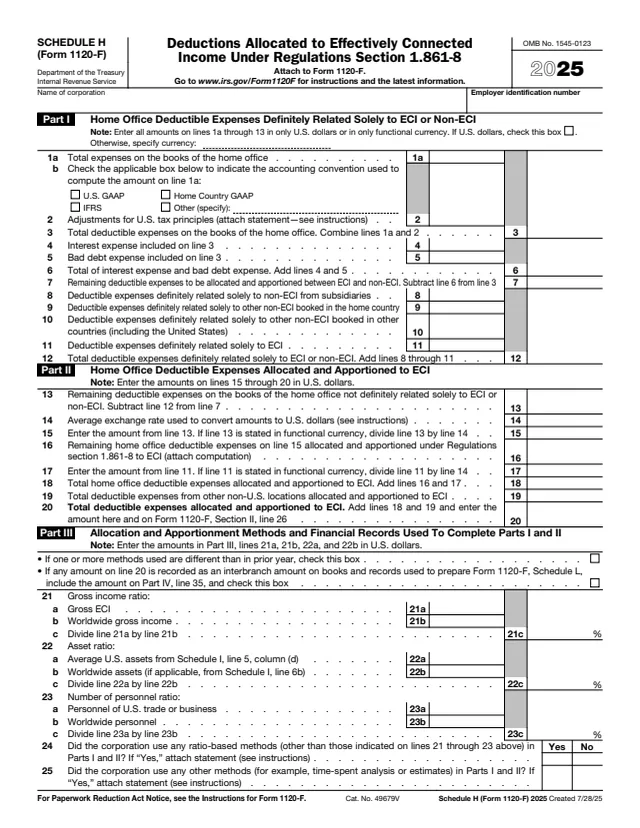
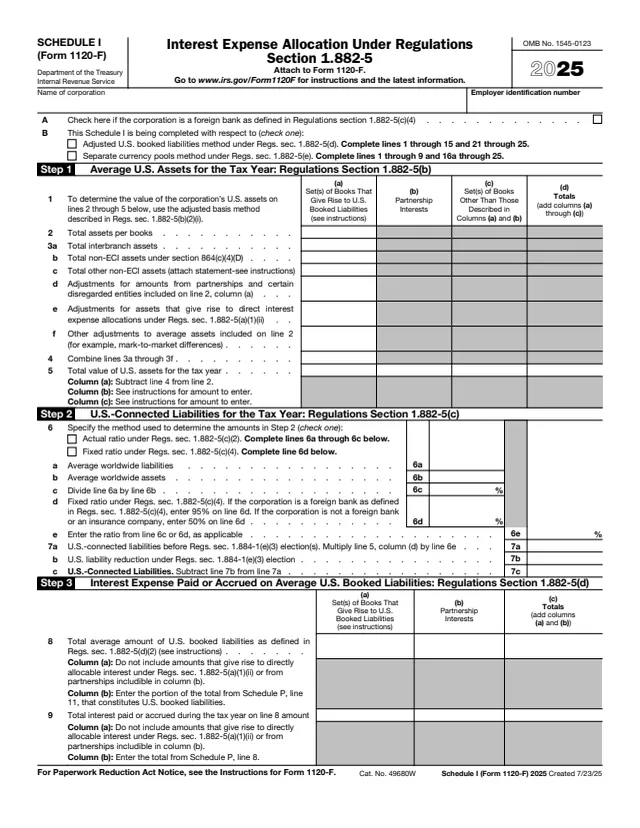
Page 1 totals the tax and payments and holds the signature. Section I covers U.S. source income not effectively connected with a U.S. trade or business. Section II covers effectively connected income, with Schedules C and J. Section III covers the branch profits tax and tax on excess interest. Schedules L and W follow, and separate schedules such as Schedules H, I, M-1 and M-2, P, S and V (Form 1120-F) attach when they apply.

This page hosts the 2025 Form 1120-F, for calendar year 2025 or a tax year beginning in 2025. You can fill it out free in your browser on this page and download it without an account.

What's on Form 1120-F

Page 1

Return type boxes including protective return and Schedule M-3 attached, items A through G on incorporation, books and records, U.S. agent, business activity and accounting method, then lines 1 through 9 for tax, payments, amount owed or overpayment.
Additional Information, pages 2 and 3

Yes or No questions starting at item H, on accounting changes, prior returns, U.S. trade or business, treaty positions under item W and other matters.

Section I

U.S. source income not effectively connected with a U.S. trade or business. The form says the rate on these gross income items is 30% or a lower treaty rate, and gross transportation income subject to 4% tax goes on line 9.

Section II with Schedules C and J

Income effectively connected with a U.S. trade or business, deductions and taxable income, with Dividends and Special Deductions on Schedule C and the Tax Computation on Schedule J.

Section III

Branch Profits Tax and Tax on Excess Interest, starting from Section II, line 29, effectively connected earnings and profits and U.S. net equity.

Schedules L and W

Balance Sheets per Books, and Schedule W for an overpayment resulting from tax deducted and withheld under Chapters 3 and 4. Schedules M-1 and M-2 (Form 1120-F) are a separate schedule.

How to fill out Form 1120-F

  1. 1

    Identifying information

    Enter the name, address, EIN and tax year, check any return type boxes, and complete items A through G, including the country of incorporation and any U.S. agent.

  2. 2

    Additional Information

    Answer the Yes or No questions on pages 2 and 3. If a lower treaty rate is claimed in Section I, the form says to complete item W on page 2.

  3. 3

    Section I

    Report each type of non-effectively connected U.S. source income with its rate and tax. The form says to report items only if not properly withheld and reported on Form 1042-S, and to attach Forms 1042-S for withholding claimed on line 5i.

  4. 4

    Sections II and III

    Report effectively connected income and deductions, complete Schedules C and J, then figure the branch profits tax and tax on excess interest in Section III.

  5. 5

    Schedules and attachments

    Complete Schedules L and W as they apply, and attach separate schedules such as Schedules M-1 and M-2 (Form 1120-F), Schedule H (Form 1120-F) or Schedule I (Form 1120-F) when required.

  6. 6

    Page 1 totals and signature

    Carry tax from Sections I, II and III to lines 1 through 3, total payments on line 5z, then enter the amount owed or overpayment. An authorized officer signs and dates the return.

Why fill Form 1120-F on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

When and where to file

With a U.S. office

The instructions say a foreign corporation that maintains an office or place of business in the United States generally files by the 15th day of the 4th month after its tax year ends.

Without a U.S. office

The instructions say a foreign corporation with no office or place of business in the United States generally files by the 15th day of the 6th month after its tax year ends.

Extension

The instructions say to file Form 7004 by the applicable due date to request an extension of time to file.

Where to file

The instructions say to file with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409. Corporations filing 10 or more returns of any type in a calendar year e-file, unless a waiver applies.

Timely filing for deductions

The instructions say Form 1120-F is generally considered timely for taking deductions and credits against effectively connected income if filed no later than 18 months after the due date of the current year's return.

Protective return

The instructions describe a protective return for a foreign corporation that determines its limited U.S. activities do not produce effectively connected income, to safeguard deductions and credits.

Who files Form 1120-F?

  • Foreign corporations in a U.S. trade or business

    The instructions say a foreign corporation files if it was engaged in a trade or business in the United States during the tax year, whether or not it had U.S. source income from it or a treaty exempts that income.

  • U.S. source income not fully withheld

    A foreign corporation not engaged in a U.S. trade or business files if it had U.S. source income and its tax liability was not fully satisfied by withholding at source under Chapter 3.

  • Refund claims and treaty positions

    The instructions say it is also filed by a foreign corporation claiming a refund of an overpayment, claiming deductions or credits, or disclosing a treaty-based position on Form 8833.

  • Agents, receivers and certain branches

    The instructions include a U.S. agent when the corporation has no U.S. office when the return is due, a receiver, assignee or trustee holding its property, and certain Mexican or Canadian branches of U.S. mutual life insurers.

  • Exceptions and special returns

    The instructions list exceptions, such as no U.S. trade or business with full tax withheld at source. Foreign insurance companies file Form 1120-L or 1120-PC, and an FSC files Form 1120-FSC.

The return is filed by or for a foreign corporation and signed by a corporate officer. The instructions list the situations below, plus exceptions and special returns.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 1120-F

What is Form 1120-F used for?

The instructions say it reports a foreign corporation's income, gains, losses, deductions and credits, figures its U.S. income tax liability, claims refunds, transmits Form 8833, and figures the branch profits tax and tax on excess interest.

Can Form 1120-F be filed only to claim a refund of tax withheld?

Yes. The instructions describe a simplified procedure for a corporation filing only as a claim for refund or credit of tax paid or withheld at source, with proof of withholding such as Form 1042-S attached.

When is Form 1120-F due?

The instructions give the 15th day of the 4th month after the tax year ends for a corporation with a U.S. office, and the 15th day of the 6th month for one without.

Where is Form 1120-F mailed?

The instructions say to file with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.

What if the corporation has no gross income because of a treaty?

The instructions say it still files to show the income was exempted, completing the identifying information including items A through G and a statement of the exclusions, or item W and Form 8833.

Can a foreign corporation join a consolidated return?

The instructions say a foreign corporation may not belong to an affiliated group filing a consolidated return, with a limited exception for certain Canadian or Mexican corporations under section 1504(d).