Header
Name of corporation and employer identification number.
1120-F
Reconciliation of Income (Loss) and Analysis of Unappropriated Retained Earnings per Books
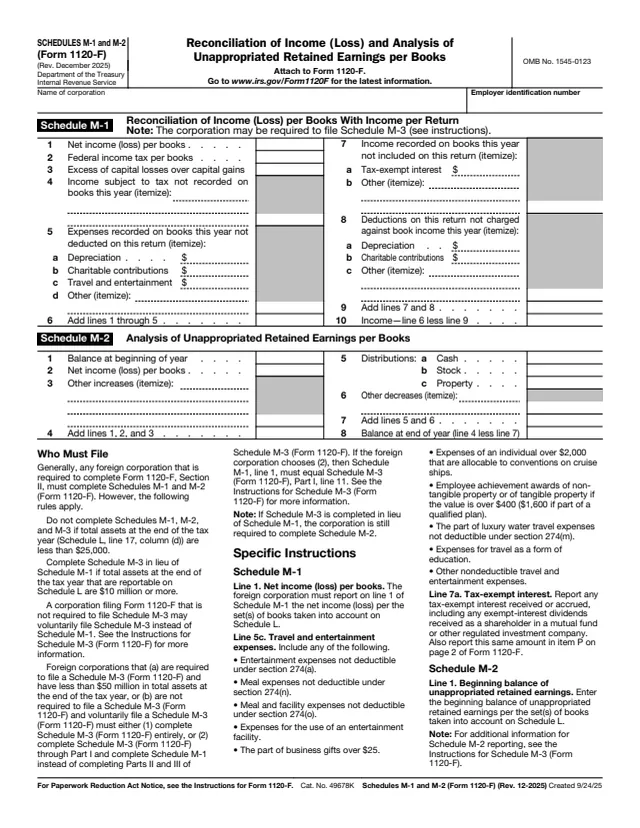
Schedules M-1 and M-2 (Form 1120-F) are the Reconciliation of Income (Loss) and Analysis of Unappropriated Retained Earnings per Books. They are attached to Form 1120-F, the U.S. Income Tax Return of a Foreign Corporation.
Schedule M-1 starts from net income (loss) per books and adds and subtracts the items that differ between the books and the return, ending with income on line 10. Schedule M-2 follows unappropriated retained earnings from the balance at the beginning of the year to the balance at the end of the year.
The About Form 1120-F page says that generally, any foreign corporation that is required to complete Form 1120-F, Section II must complete Schedules M-1 and M-2. The instructions on the same PDF add asset thresholds and Schedule M-3 rules. You can fill out the schedules free in your browser on this page and download them without an account.
Name of corporation and employer identification number.
Net income (loss) per books, federal income tax per books, excess of capital losses over capital gains, income subject to tax not recorded on books, and expenses recorded on books not deducted on the return.
Income recorded on books not included on the return, deductions on the return not charged against book income, and income on line 10 (line 6 less line 9).
Balance at beginning of year, net income (loss) per books, other increases, and their total.
Distributions of cash, stock and property, other decreases, their total, and balance at end of year (line 4 less line 7).
Who Must File and Specific Instructions for selected lines are printed below the schedules on the same page.
Compare total assets at the end of the tax year with the thresholds in Who Must File: less than $25,000, and $10 million or more reportable on Schedule L, where Schedule M-3 is used in lieu of Schedule M-1.
The instructions say to report the net income (loss) per the set(s) of books taken into account on Schedule L. If Schedule M-3 is completed through Part I with Schedule M-1, line 1 equals Schedule M-3 (Form 1120-F), Part I, line 11.
The instructions list what to include, such as entertainment expenses not deductible under section 274(a), meal expenses not deductible under section 274(n), and the part of business gifts over $25.
Report tax-exempt interest received or accrued, including exempt-interest dividends from a mutual fund or other regulated investment company. The instructions say to also report this amount in item P on page 2 of Form 1120-F.
Enter the beginning balance of unappropriated retained earnings per the set(s) of books taken into account on Schedule L, then work down to the balance at end of year on line 8.
The form says to attach the schedules to Form 1120-F.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1120-F. It has no separate mailing address and travels with the return.
The instructions say a foreign corporation that is required to file Schedule M-3 with less than $50 million in total assets, or that files it voluntarily, either completes Schedule M-3 entirely or completes it through Part I and completes Schedule M-1 instead of Parts II and III.
The instructions note that if Schedule M-3 is completed in lieu of Schedule M-1, the corporation is still required to complete Schedule M-2.
The form points to www.irs.gov/Form1120F for the latest information, and to the Instructions for Form 1120-F for the Paperwork Reduction Act Notice.
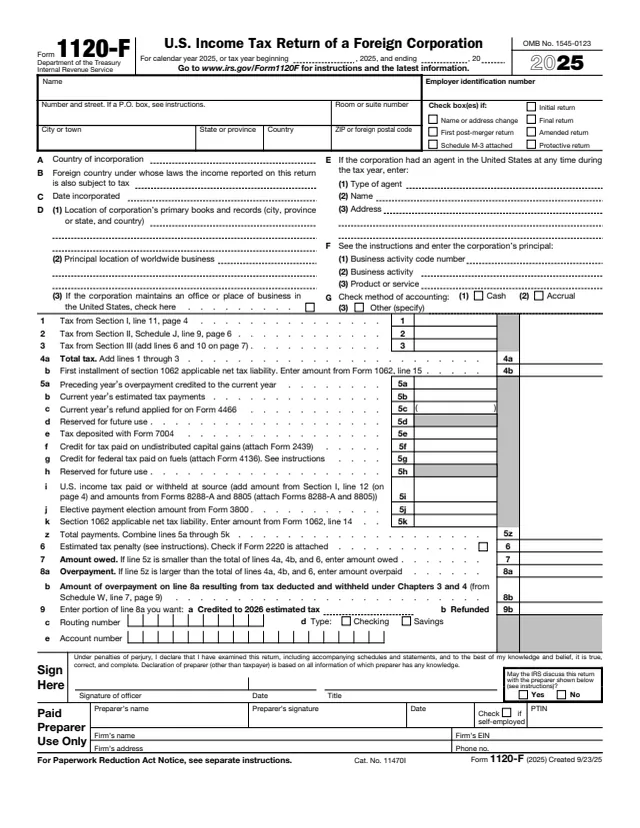
1120-F
527 fields, 9 pages
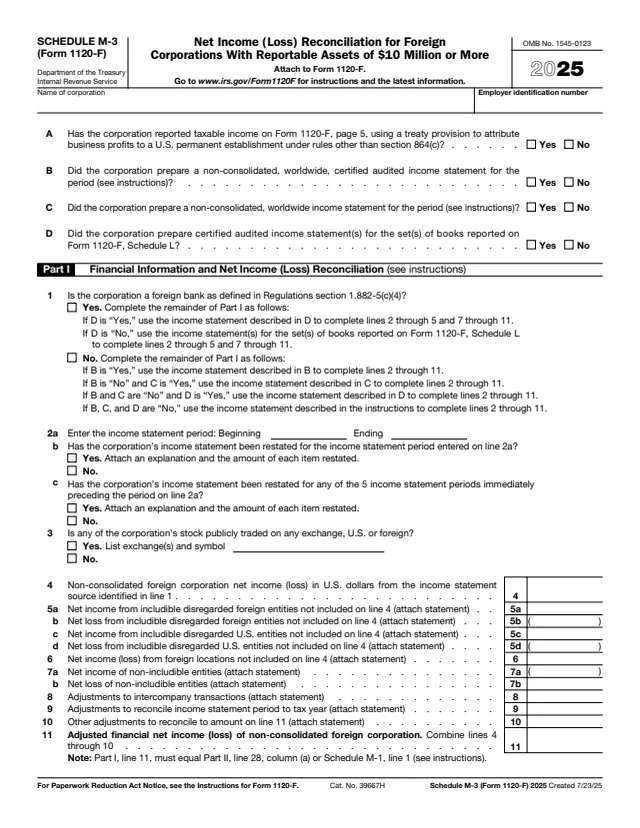
1120-F
439 fields, 4 pages
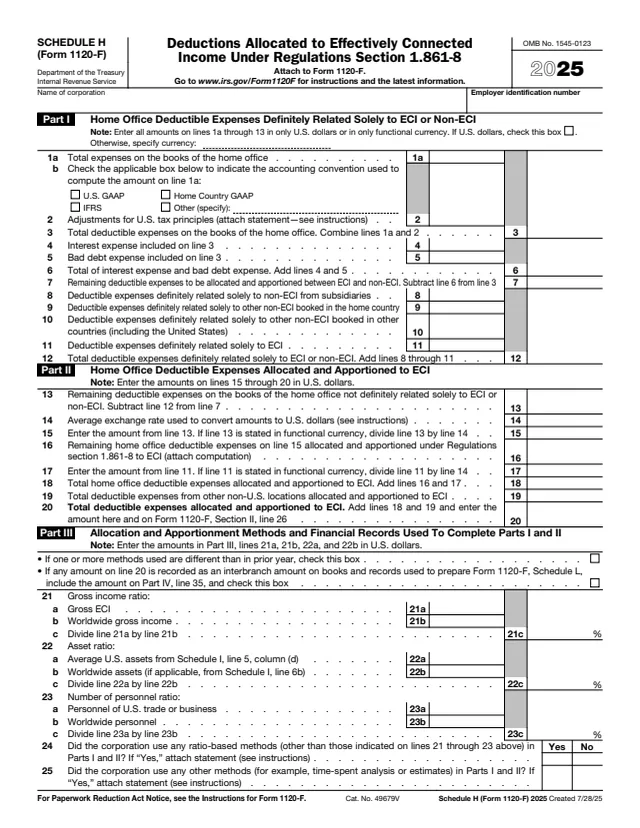
1120-F
77 fields, 2 pages
1120-F
113 fields, 3 pages
1120-F
173 fields, 3 pages
1120-F Sch. S
68 fields, 2 pages
The schedules are completed by a foreign corporation as part of its Form 1120-F. The instructions set out who completes them and when Schedule M-3 is used instead.
No tool matches that search.
The instructions say generally, any foreign corporation that is required to complete Form 1120-F, Section II completes them, subject to the asset rules in Who Must File.
The instructions say not to complete Schedules M-1, M-2 and M-3 if total assets at the end of the tax year (Schedule L, line 17, column (d)) are less than $25,000.
The instructions say Schedule M-3 is completed in lieu of Schedule M-1 if total assets reportable on Schedule L are $10 million or more. A corporation not required to file Schedule M-3 may file it voluntarily instead of Schedule M-1.
Yes. The instructions say a corporation that completes Schedule M-3 in lieu of Schedule M-1 is still required to complete Schedule M-2.
On Schedule M-1, line 7a. The instructions say the same amount is also reported in item P on page 2 of Form 1120-F.
The About Form 1120-F page lists no separate instructions for these schedules. Their Who Must File and Specific Instructions are printed on the schedule page itself.