Questions A to D
Whether a treaty position attributes business profits to a U.S. permanent establishment, and which audited or unaudited income statements the corporation prepared.
1120-F
Net Income (Loss) Reconciliation for Foreign Corporations With Reportable Assets of $10 Million or More
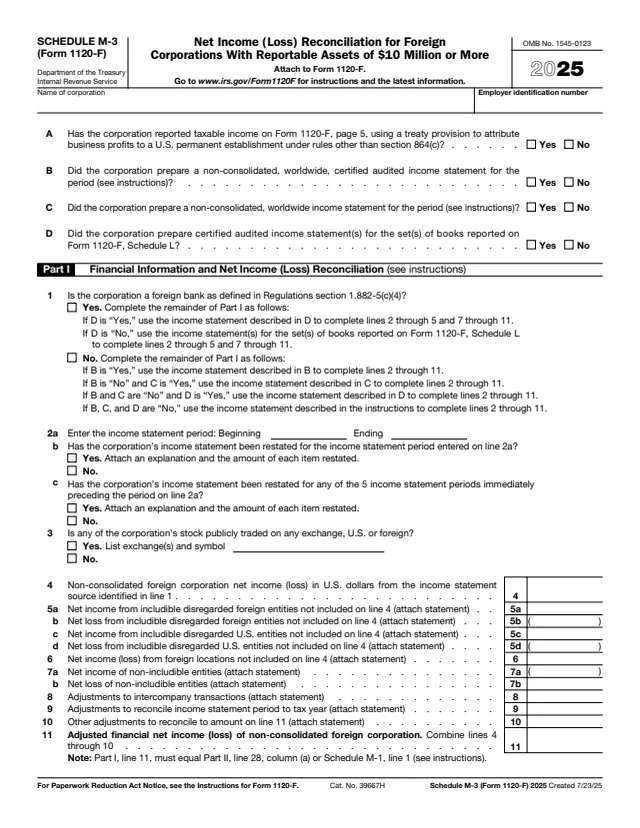
Schedule M-3 (Form 1120-F), Net Income (Loss) Reconciliation for Foreign Corporations With Reportable Assets of $10 Million or More, is attached to Form 1120-F, U.S. Income Tax Return of a Foreign Corporation. The IRS About page says Part I determines the adjusted financial net income (loss) of the non-consolidated foreign corporation, and Parts II and III reconcile that financial result with the corporation's taxable income before the NOL deduction and special deductions on Form 1120-F.
The instructions say a foreign corporation filing Form 1120-F that reports total assets of $10 million or more on Schedule L completes Schedule M-3 in place of Schedule M-1. Each income and expense item is reported per the income statement, with temporary and permanent book-to-tax differences, allocations between effectively connected income (ECI) and non-ECI, and the amount per the tax return.
This page has the 2025 schedule. You can fill out Schedule M-3 (Form 1120-F) free in your browser on this page and download it without an account.
Whether a treaty position attributes business profits to a U.S. permanent establishment, and which audited or unaudited income statements the corporation prepared.
Foreign bank status, the income statement period and restatements, publicly traded stock, and net income adjusted for disregarded and non-includible entities to reach line 11.
Gross receipts, dividends, interest, rents, royalties, partnership income, mark-to-market, global dealing, gains and losses, each across columns (a) to (e).
Income tax expense, compensation, meals, fines, benefits, amortization, depreciation, interest under Regulations section 1.882-5 and other expenses, totaled on line 33.
Column (a) per income statement, (b) temporary differences, (c) permanent differences, (d) other permanent differences for allocations to non-ECI and ECI, and (e) per tax return.
Enter the corporation's name and EIN. The instructions say filers answer all questions on page 1, and questions B to D use only the foreign corporation's own financial statements.
Answer the foreign bank question, then follow the printed path that says which income statement completes lines 2 through 11, based on the answers to B, C and D.
Enter the statement period, any restatements with an attached explanation, exchange listings, and net income with the adjustments. The form says line 11 equals Part II, line 28, column (a) or Schedule M-1, line 1.
For each line, report the book amount in (a) and the return amount in (e). The instructions say a difference that can't be classed as temporary or permanent goes in column (c).
Part III, line 33 goes to Part II, line 26. The form says Part II, line 28, column (e) equals Form 1120-F, page 5, line 29.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach the schedule to Form 1120-F and check the box at the top of Form 1120-F, page 1, indicating that Schedule M-3 is attached.
The instructions say a foreign corporation that completes Schedule M-3 is still required to complete Schedule M-2, Analysis of Unappropriated Retained Earnings per Books.
The instructions say that for any part completed, all columns must be completed and any statement required to support a line item must be attached.
If Part III is completed, the instructions say results from Schedule I (Form 1120-F) and Schedule H (Form 1120-F) are also included, on lines 26b, 26c and 31.
The instructions say required filers with at least $50 million total assets at the end of the tax year complete Schedule M-3 (Form 1120-F) in its entirety.
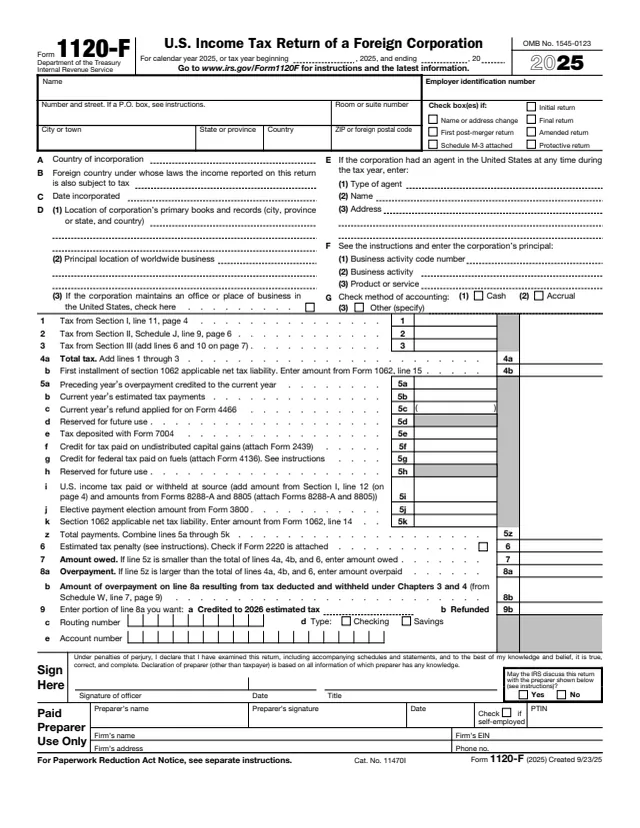
1120-F
527 fields, 9 pages
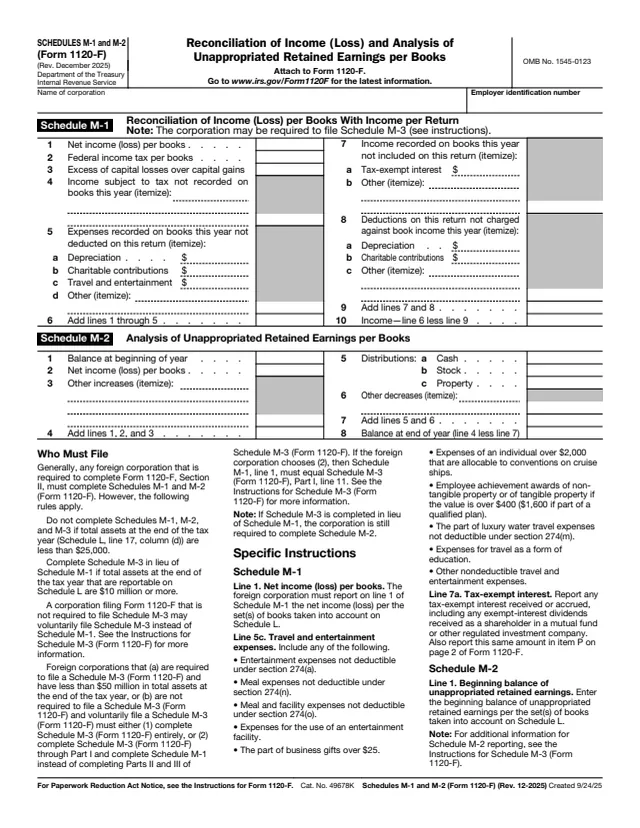
1120-F
45 fields, 1 page
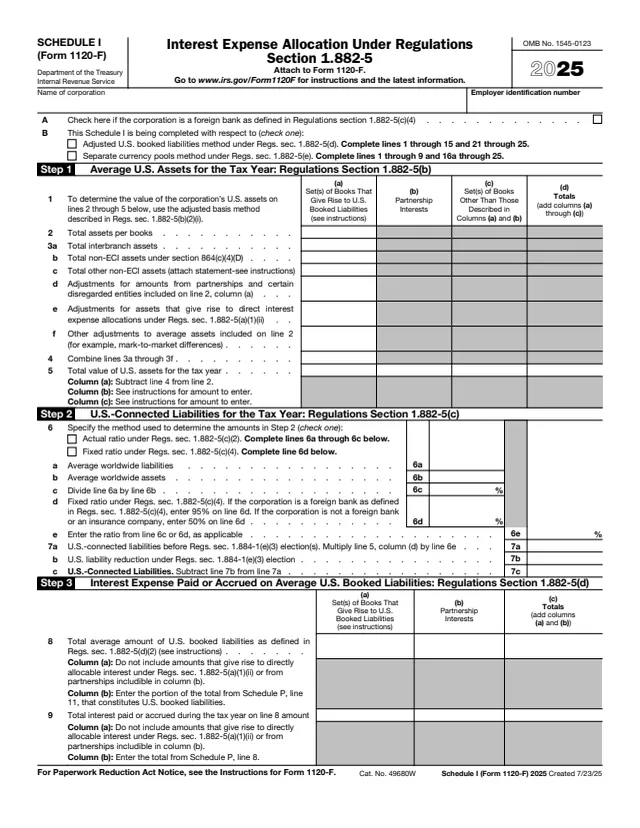
1120-F
113 fields, 3 pages
1120-F
77 fields, 2 pages
1120 Sch. M-3
380 fields, 3 pages
1065 Sch. M-3
316 fields, 3 pages
It is filed by a foreign corporation with its Form 1120-F, not by an individual. The instructions say a foreign corporation required to file Form 1120-F that reports on Schedule L, line 17, column (d), total assets at year end that equal or exceed $10 million completes Schedule M-3 in lieu of Schedule M-1.
No tool matches that search.
The instructions say it applies when total assets on Form 1120-F, Schedule L, line 17, column (d), at the end of the tax year equal or exceed $10 million.
For required filers, the instructions say it is completed in lieu of Schedule M-1. Filers under $50 million may complete Part I and Schedule M-1 instead of Parts II and III.
The instructions say a foreign corporation that prepares its own financial statements uses them for Part I, rather than the statements of a controlling corporation.
The instructions say column (b) holds book-to-tax differences expected to reverse or reversing a prior year difference, and column (c) holds differences not expected to reverse.
It answers Yes to question A. The instructions say the treatment of items in columns (c) and (d) is then adapted to apply the concepts of the applicable treaty.
Yes. The form says to attach an explanation and the amount of each item restated when lines 2b or 2c are answered Yes.