Withholding agent
The withholding agent's name, address, phone number and U.S. TIN.
8288-A
Statement of Withholding on Certain Dispositions by Foreign Persons
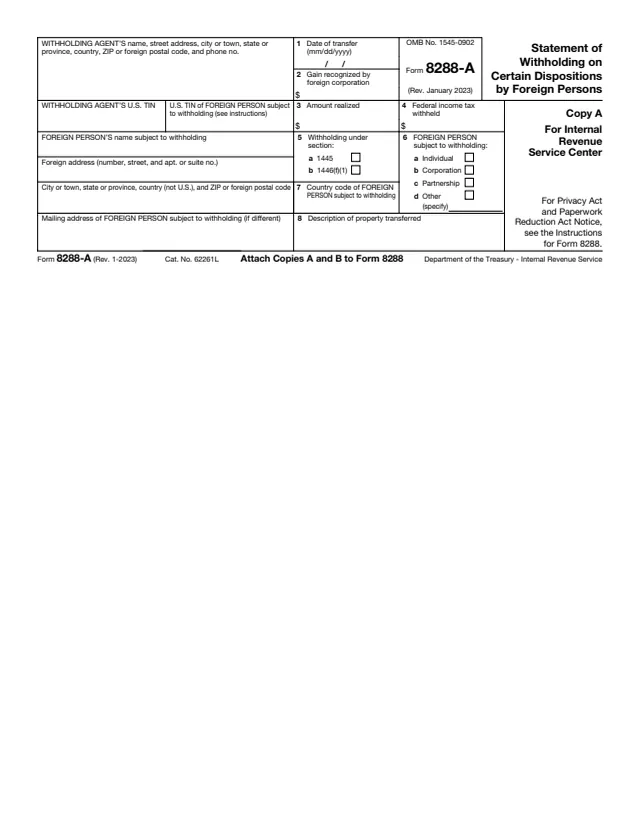
Form 8288-A is a statement prepared by a withholding agent, not by the seller. The IRS About page says buyers and transferees use it with Form 8288 for each foreign person that disposes of real property located in the U.S. to report withholding on the amount realized. The form also covers withholding under section 1446(f)(1) on transfers of certain partnership interests.
The withholding agent attaches Copies A and B to Form 8288 and keeps Copy C. The instructions say the IRS stamps Copy B and sends it to the foreign person subject to withholding if the form is complete, including the transferor's taxpayer identification number. The foreign person then uses Copy B to claim credit for the tax withheld.
You can fill out the PDF free in your browser on this page and download the result without an account.
The withholding agent's name, address, phone number and U.S. TIN.
The foreign person's name, U.S. TIN, foreign address and a separate mailing address if different.
Date of transfer, gain recognized by a foreign corporation, amount realized and federal income tax withheld.
The section the withholding was made under (1445 or 1446(f)(1)), the type of foreign person, the two-letter country code and a description of the property transferred.
Copy A is for the IRS. Copy B is sent to the IRS for use by the foreign person. Copy C is for the withholding agent's records.
Notes for the foreign person on how to report the sale, how to claim credit for the tax withheld and how to apply for an early refund.
Enter the withholding agent's name, street address, city, state or province, country, ZIP or foreign postal code, phone number and U.S. TIN.
Enter the name and U.S. TIN (SSN, EIN or ITIN). The instructions ask for the foreign home address for an individual or foreign office address for others, outside the United States. A separate mailing address is optional.
Enter the date of transfer. The instructions say to enter the date of distribution instead for withholding under section 1445(e)(2), (e)(3) or (e)(6), section 1446(f)(1), or the large trust election.
Box 2 is only for a foreign corporation required to withhold under section 1445(e)(2). Box 3 is the amount realized by the foreign person. Box 4 is the federal income tax withheld for that person.
Check the section and the type of foreign person. For Other, the instructions say to specify trust or estate. Box 7 takes the two-letter code from www.irs.gov/countrycodes. Box 8 describes the property.
Attach Copies A and B to Form 8288 and keep Copy C. The instructions say the withholding agent does not have to give a copy to the foreign person.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach Copies A and B to Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons. It points to the Instructions for Form 8288 for more information.
The instructions say the IRS stamps Copy B and sends it to the foreign person if the form is complete, including the transferor's TIN.
The instructions say 15% of the amount realized under section 1445, 21% for certain foreign interest holders that are beneficiaries or shareholders, and 10% under section 1446(f)(1).
The instructions say to attach Form 8288-A to Form 1040-NR, 1041, 1065 or 1120-F to receive credit. Foreign partnerships report the credit on Form 8804 and attach Form 8288-A.
Available only when box 5a is checked, after the IRS issues a withholding certificate. The form gives the address Ogden Service Center, P.O. Box 409101, Ogden, UT 84409. Not available for section 1446(f)(1) or 1446(f)(4).
8288
56 fields, 2 pages
8288-B
51 fields, 4 pages
8288-C
48 fields, 5 pages
1040-NR
171 fields, 2 pages
1120-F
527 fields, 9 pages
8804
81 fields, 2 pages
The instructions for the withholding agent say to prepare Form 8288-A for each foreign person subject to withholding under section 1445 or 1446(f)(1). The foreign person receives the stamped Copy B from the IRS.
No tool matches that search.
The withholding agent, usually the buyer or other transferee. The instructions say to prepare one for each foreign person subject to withholding under section 1445 or 1446(f)(1).
No. The instructions say the withholding agent does not have to give a copy to the foreign person. The IRS stamps Copy B and sends it if the form is complete, including the transferor's TIN.
The instructions say to attach it to Form 1040-NR, 1041, 1065 or 1120-F to receive credit for the tax in box 4. Foreign partnerships report the credit on Form 8804.
15% of the amount realized under section 1445, 21% for certain foreign interest holders that are beneficiaries or shareholders, and 10% under section 1446(f)(1).
The instructions describe an early refund for box 5a withholding after the IRS issues a withholding certificate. The early refund is not available for withholding under section 1446(f)(1) or 1446(f)(4).
No. The instructions say PTPs and their nominees use Forms 1042 and 1042-S to report the withholding.