8288

U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons

Agency
IRS
Revision
Rev. January 2026
Fillable fields
56
Pages
2
Official source
IRS form page
Checked
October 21, 2026
Fill 8288 online
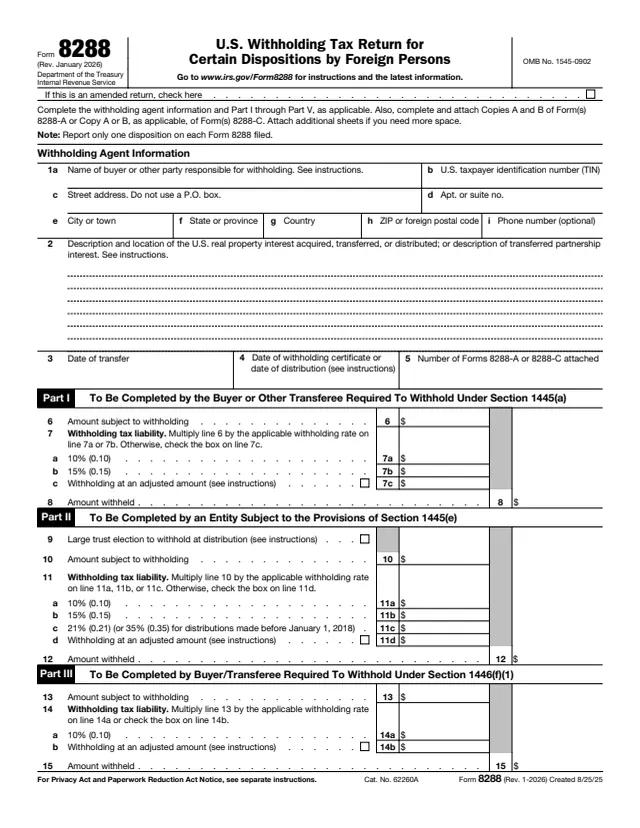
Page 1 of form 8288

Form 8288: U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons

Form 8288 is the U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons. The instructions say it is used to report and transmit amounts withheld on certain dispositions and distributions subject to sections 1445 and 1446(f)(1), and to report and transmit amounts withheld under section 1446(f)(4) or claim a credit or refund of them for transfers occurring on or after January 1, 2023.

The form is completed by the withholding agent, not by the foreign seller. The instructions name the buyer or other transferee of a U.S. real property interest (USRPI), a corporation, qualified investment entity (QIE) or fiduciary subject to section 1445(e), the buyer or other transferee of a partnership interest, and a partnership that withholds under section 1446(f)(4). The form says to report only one disposition on each Form 8288 filed and to attach Copies A and B of Form 8288-A, or Copy A or B of Form 8288-C, as applicable.

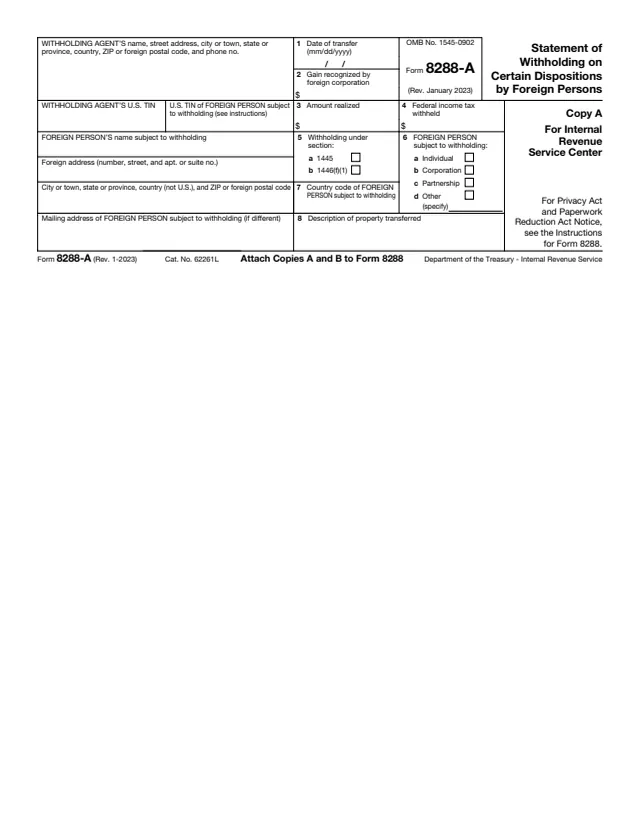
The IRS stamps Copy B of each Form 8288-A and forwards it to the foreign person subject to withholding. You can fill out Form 8288 free in your browser on this page and download it without an account.

What's on Form 8288

Withholding agent information, lines 1 to 5

Name, TIN and address of the withholding agent, a description and location of the property or partnership interest, the date of transfer, the date of a withholding certificate or distribution, and the number of Forms 8288-A or 8288-C attached.
Part I: section 1445(a), lines 6 to 8

Amount subject to withholding, the withholding tax liability at 10% or 15% or at an adjusted amount on line 7c, and the amount withheld.

Part II: section 1445(e), lines 9 to 12

A large trust election box, the amount subject to withholding, rate lines for 10%, 15%, and 21% (or 35% for distributions made before January 1, 2018), an adjusted amount line, and the amount withheld.

Part III: section 1446(f)(1), lines 13 to 15

For a transfer of a partnership interest: amount subject to withholding, liability at 10% or at an adjusted amount, and the amount withheld.

Part IV: section 1446(f)(4), lines 16 to 18

The partnership reports the total number and amount of distributions, other withholding on them, the transferee's section 1446(f)(1) liability if known, and the total amounts withheld.

Part V, refund lines and signature

Lines 19 to 22 cover a transferee's refund claim, with lines 22b to 22d for direct deposit. The return is signed by the withholding agent, partner, fiduciary or corporate officer, with a Paid Preparer Use Only area.

How to fill out Form 8288

  1. 1

    Amended box and line 1

    Check the box at the top only for an amended return. On line 1, enter the withholding agent's name, address and TIN: an SSN for a U.S. individual, an EIN for any other person, or an ITIN for a nonresident alien not eligible for an SSN. The form says not to use a P.O. box.

  2. 2

    Lines 2 to 5

    Describe the property, for example "12-unit apartment building", or the partnership interest, for example "40% of the Class B capital interest in the ABC Partnership". Enter the transfer date, any withholding certificate or distribution date, and the number of Forms 8288-A or 8288-C. Copies A and B of one Form 8288-A count as one form.

  3. 3

    Pick the one part that applies

    The instructions say to complete only one part of Parts I through V. Part V notes that a refund claim can be filed with both Parts III and V completed when no Form 8288 with Part III was filed before.

  4. 4

    Rate line and amount withheld

    Enter an amount on only one rate line in the part you complete. For an adjusted amount, enter it and check the box; for Parts I and II the instructions say to attach a copy of the withholding certificate. Then enter the amount actually withheld.

  5. 5

    Part IV cumulative totals

    Line 16 reports this distribution plus prior distributions to the same transferee. The instructions say to file a separate Form 8288 for each distribution and attach only the Form 8288-C for the current one.

  6. 6

    Part V and signature

    Line 22a is the excess of line 20 over line 21a or 21b. For direct deposit, the routing number on line 22b is nine digits. Sign and date; a paid preparer also signs and enters a PTIN.

Why fill Form 8288 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, deadlines and penalties

Where to send it

The instructions say to send Form 8288 with the amount withheld and the attached Forms 8288-A or 8288-C to Ogden Service Center, P.O. Box 409101, Ogden, UT 84409.

Deadline

A transferee files and transmits the tax withheld by the 20th day after the date of transfer. A partnership withholding under section 1446(f)(4) files by the 20th day after the date of the distribution.

Forms 8288-A and 8288-C

A Form 8288-A is completed for each person subject to withholding, with Copies A and B attached and Copy C kept. For Part IV, one Form 8288-C is attached per Form 8288 and Copy B is sent to the transferee.

Missing TIN

The instructions say Forms 8288 and 8288-A are still filed without the transferor's TIN. The IRS then sends the transferor a letter asking for the TIN.

Penalties

The instructions cite section 6651 penalties for failure to file or pay when due, a penalty of up to $10,000 under section 7202 for willful failure to collect and pay over the tax, and a section 6672 penalty for responsible persons.

When Forms 1042 and 1042-S apply instead

The instructions list cases reported on Forms 1042 and 1042-S, not Forms 8288 and 8288-A, such as a transfer of a publicly traded partnership interest subject to section 1446(f)(1).

Who fills out Form 8288?

  • Buyers of U.S. real property from a foreign person

    The instructions say a buyer or other transferee of a USRPI completes and files Part I to report and transmit the amount withheld under section 1445(a).

  • Corporations, QIEs and fiduciaries

    A corporation, QIE or fiduciary required to withhold under section 1445(e) completes Part II, for example a domestic corporation distributing property to a foreign shareholder.

  • Buyers of partnership interests

    A buyer or other transferee of a partnership interest completes Part III to report withholding under section 1446(f)(1), unless one of the exceptions in the instructions applies.

  • Partnerships withholding on distributions

    A partnership that makes a distribution to a transferee partner that failed to withhold under section 1446(f)(1) completes Part IV.

  • Transferees claiming a refund

    A transferee that was overwithheld upon under section 1446(f)(4) completes Part V and attaches the Forms 8288-C it received from the partnership.

  • Not the title or settlement company

    The instructions say not to enter a title company or mortgage company on line 1 unless it is the actual person or entity responsible for withholding.

The withholding agent files it. The instructions list five kinds of withholding agent, one for each part of the form.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 8288

Does the foreign seller file Form 8288?

No. The withholding agent files it. The IRS stamps Copy B of Form 8288-A and forwards it to the foreign person, who generally attaches it to a U.S. income tax return such as Form 1040-NR or 1120-F to receive credit.

Is the title company the withholding agent?

Not by default. The instructions say not to enter a title or mortgage company on line 1 unless it is the actual person or entity responsible for withholding. Their example names the buying corporation, not the settlement agent.

What rates appear on Form 8288?

The form prints 10% and 15% in Part I, 10%, 15% and 21% (or 35% for distributions made before January 1, 2018) in Part II, and 10% in Parts III and V, plus lines for an adjusted amount.

Can one Form 8288 cover several sales?

The form says to report only one disposition on each Form 8288 filed. The instructions say multiple Forms 8288-A related to a single transaction can be filed with one Form 8288.

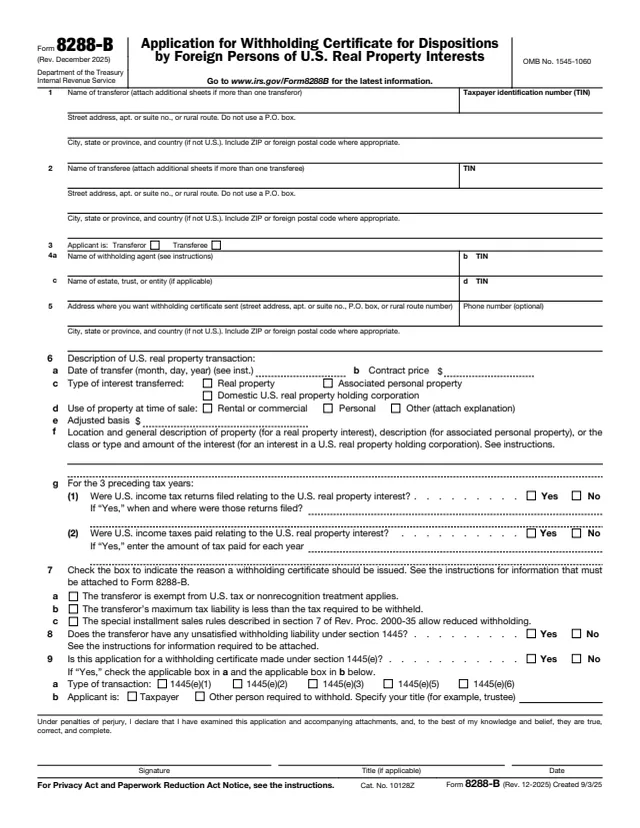
What if a withholding certificate was requested on Form 8288-B?

The instructions say withholding still applies, but Form 8288 and the withholding are not due until the 20th day after the IRS mails a copy of the withholding certificate or notice of denial.

What do the instructions say about a home bought for $300,000 or less?

They say no withholding is required when individuals acquire U.S. real property for use as a residence and the amount realized is $300,000 or less, and that a reduced rate of 10% applies to a residence with an amount realized of $1 million or less.

Can a refund under Part V be deposited directly?

Yes. The January 2026 revision added lines 22b, 22c and 22d for the routing number, account type and account number.