Lines 1 and 2: the parties
The name, street address and TIN of the transferor and of the transferee, with additional sheets for more than one. The form says not to use a P.O. box.
8288-B
Application for Withholding Certificate for Dispositions by Foreign Persons of U.S. Real Property Interests
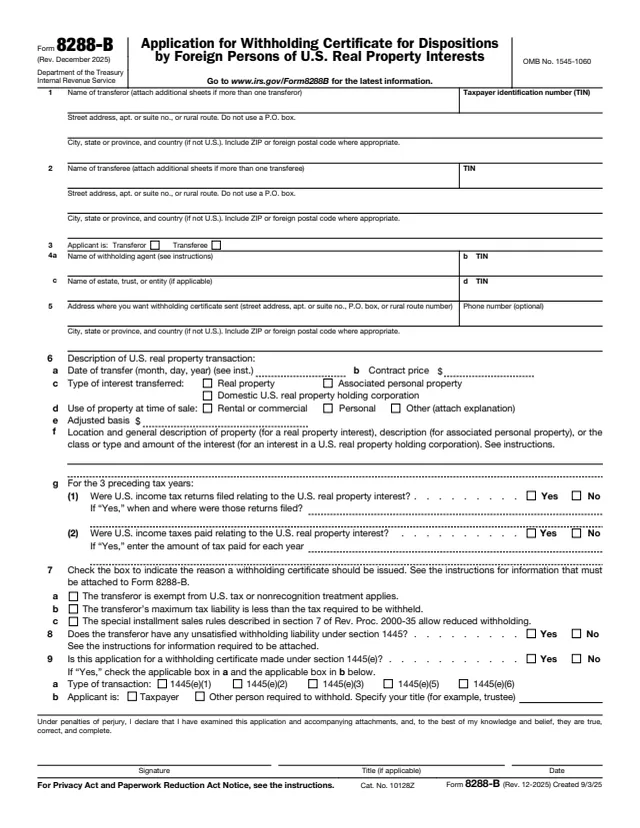
Form 8288-B, Application for Withholding Certificate for Dispositions by Foreign Persons of U.S. Real Property Interests, is used to apply for a withholding certificate to reduce or eliminate withholding under section 1445 when a foreign person disposes of a U.S. real property interest. The IRS page says foreign persons use this form, and the instructions say either the transferee or the transferor (or other authorized person) can file the application.
The form only covers three kinds of claims: that the transferor is exempt from tax or entitled to nonrecognition treatment, that the transferor's maximum tax liability is less than the tax otherwise required to be withheld, or that the special installment sales rules in section 7 of Rev. Proc. 2000-35 allow reduced withholding. The instructions list what has to be attached for each claim.
The instructions say the IRS will normally act on an application within 90 days of receipt of all information necessary to make a proper determination. You can fill out the PDF free in your browser on this page and download it without an account.
The name, street address and TIN of the transferor and of the transferee, with additional sheets for more than one. The form says not to use a P.O. box.
Whether the applicant is the transferor or transferee, the withholding agent and TIN, any estate, trust or entity and its TIN, and the address for the certificate.
Date of transfer, contract price, type of interest, use of the property, adjusted basis, a description, and returns filed and taxes paid for the 3 preceding tax years.
Three boxes: exempt or nonrecognition treatment, maximum tax liability less than the required withholding, or the special installment sales rules of Rev. Proc. 2000-35.
Whether the transferor has any unsatisfied withholding liability under section 1445, and whether the application is made under section 1445(e), with the type of transaction and the applicant's role.
A declaration under penalties of perjury covering the application and attachments, with the signature, title if applicable, and date.
Enter the name, street address and TIN of each transferor and transferee. For a section 1445(e) transaction, enter each foreign person for whom reduced withholding is requested. The instructions say the TIN of all parties goes on the application.
Check transferor or transferee. Enter the withholding agent, your SSN or ITIN on 4b if not applying in a personal capacity, the estate, trust or entity and its EIN on 4c and 4d, and the address for returning the certificate.
Enter the date of transfer with a four-digit year, the contract price and adjusted basis, the interest type and use. Check Other on 6d for mixed personal and rental use and attach an explanation.
Check one reason. For 7a attach the description, summary of law, facts, evidence and assessed value. For 7b attach the maximum tax calculation and the transferor's signed statement. For 7c see Installment sales.
Attach a calculation of the transferor's unsatisfied withholding liability or evidence that it does not exist, such as a copy of Form 8288 filed and proof of payment.
For a section 1445(e) application, check the provision and whether the applicant is the taxpayer or another person required to withhold. Then sign, add a title if applicable, and date.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 8288-B is sent to the Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
A person without a TIN who is eligible for an ITIN can attach the completed Form 8288-B to a completed Form W-7 and send the package to the address in the Form W-7 instructions.
The instructions say the IRS will normally act on an application within 90 days of receipt of all information necessary to make a proper determination.
If an application is or has been submitted on the date of transfer, the instructions say the withholding is not required to be paid over until the 20th day after the IRS mails the certificate or a notice of denial.
The instructions say an application that is not substantially complete will be rejected, for example one without a specific or estimated date of transfer.
If withholding is still required after a certificate is issued, the instructions say a copy of the certificate is attached to Form 8288.
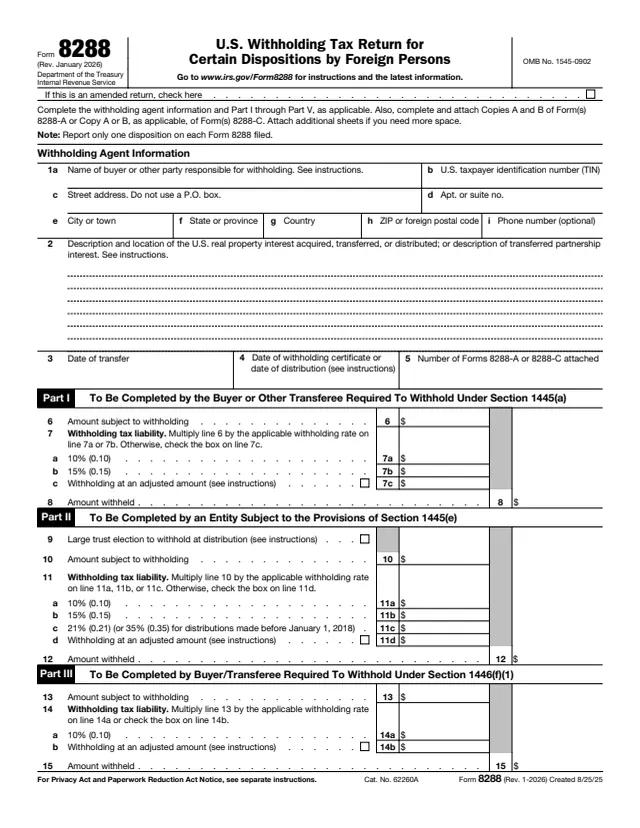
8288
56 fields, 2 pages
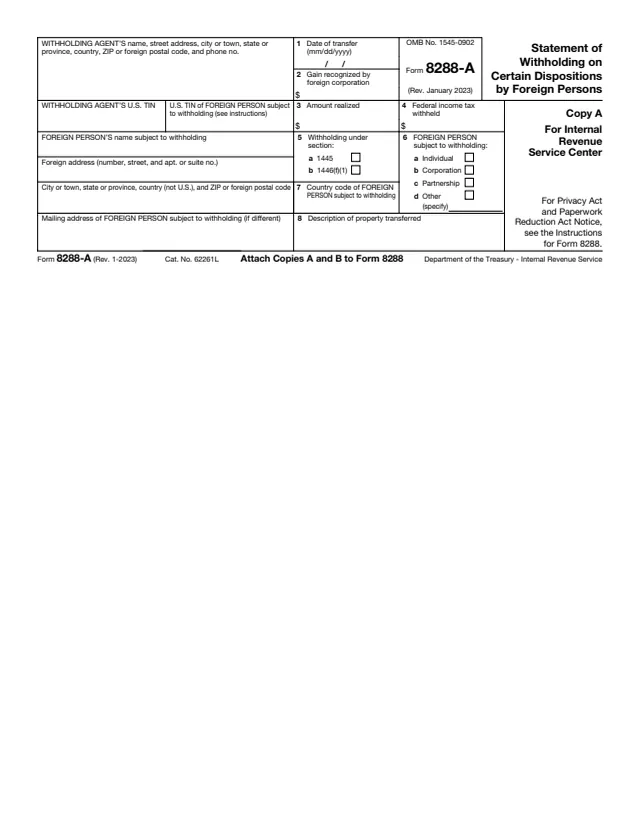
8288-A
60 fields, 5 pages
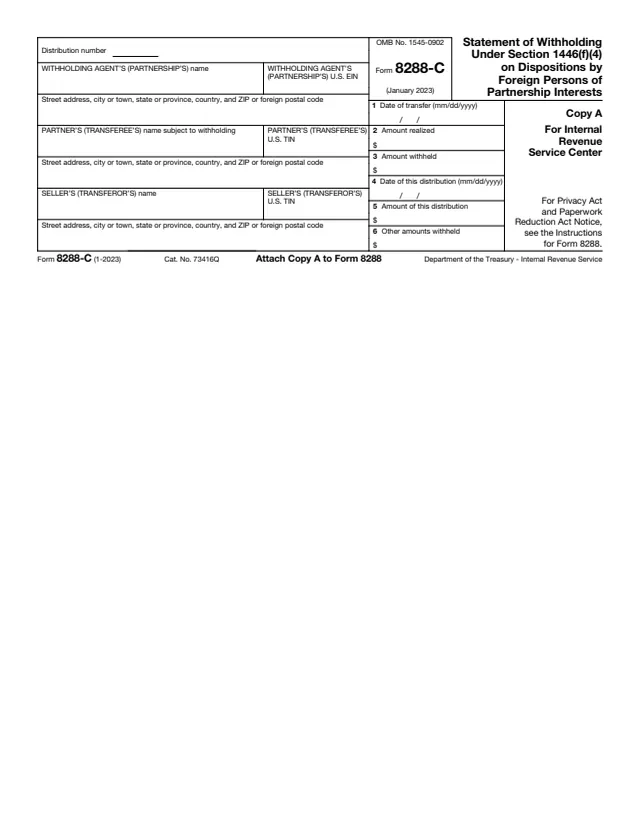
8288-C
48 fields, 5 pages
W-7
69 fields, 1 page

2848
92 fields, 2 pages
SS-4
89 fields, 2 pages
The instructions say either party to the sale, or another authorized person, can apply. The certificate is mailed to the address the applicant enters on line 5.
No tool matches that search.
The instructions say either the transferee or the transferor (or other authorized person) can file the application. The IRS page describes it as a form foreign persons use.
The instructions give the Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409. A package with Form W-7 goes to the address in the Form W-7 instructions.
The instructions say the IRS will normally act within 90 days of receipt of all information necessary to make a proper determination.
The instructions say a nonresident alien who needs a TIN but is not eligible for an SSN applies for an ITIN, and can do so by attaching Form 8288-B to a completed Form W-7.
No. The instructions say a certificate applies only for the limited purpose of determining the withholding obligation under section 1445 and does not apply to any substantive issue.
The instructions say that if the transferor is not a dealer and reports gain using the installment method under section 453, a certificate allowing reduced withholding may be obtained.
The form says not to use it for applications based on an agreement for the payment of tax with conforming security, for blanket certificates under Rev. Proc. 2000-35, or for other types.