Distribution number and partnership
A distribution number, then the withholding agent's (partnership's) name, U.S. EIN and address.
8288-C
Statement of Withholding Under Section 1446(f)(4) on Dispositions by Foreign Persons of Partnership Interests
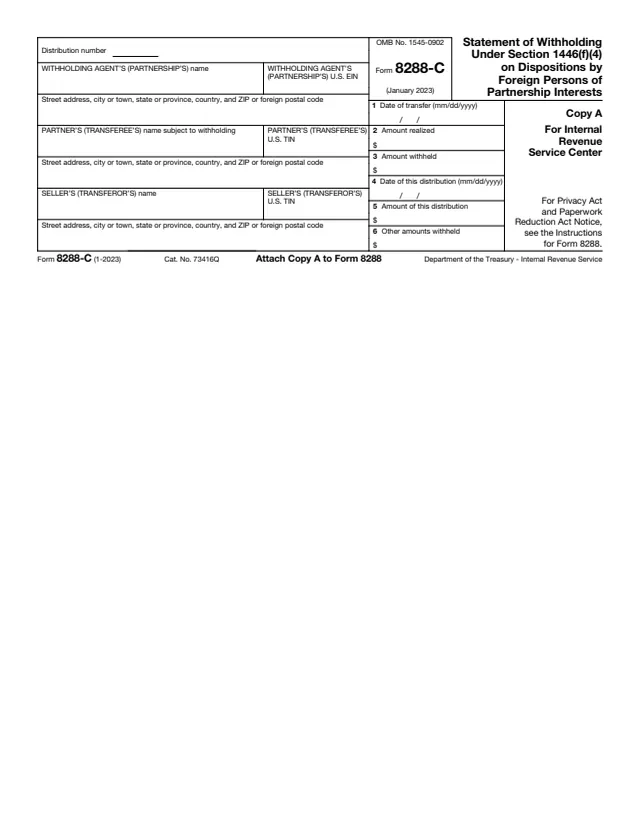
Form 8288-C is the Statement of Withholding Under Section 1446(f)(4) on Dispositions by Foreign Persons of Partnership Interests. It is prepared by a partnership acting as withholding agent, not by an individual taxpayer.
The instructions on the form explain when it is used: if a foreign person transferred an interest in a partnership and the transferee failed to withhold the entire amount required under section 1446(f)(1), or failed to certify to the partnership the extent to which it satisfied its withholding obligation, the partnership withholds on each distribution to the transferee under section 1446(f)(4) and issues the transferee a Form 8288-C.
Copy A goes to the IRS with Form 8288, Copy B goes to the partner (transferee) and Copy C stays with the partnership. You can fill out the PDF free in your browser on this page and download the result without an account.
A distribution number, then the withholding agent's (partnership's) name, U.S. EIN and address.
The name, U.S. TIN and address of the partner subject to withholding and of the seller who transferred the interest.
The date of transfer, the amount realized and the amount withheld.
The date of this distribution, the amount of this distribution and other amounts withheld.
Copy A for the IRS, Copy B for the partner (transferee) subject to withholding, and Copy C for the withholding agent.
Enter the distribution number and the partnership's name, U.S. EIN and address.
Enter each person's name, U.S. TIN (SSN, EIN or ITIN) and address. For a foreign address, the instructions say not to abbreviate the country name and to follow the country's practice for the postal code.
Enter the date the partnership interest was transferred to the transferee, and the amount realized by the foreign person who transferred it.
Enter the federal withholding tax and interest withheld under section 1446(f)(4) on the distribution to the transferee.
Enter the date and total amount of the distribution. In box 6, the instructions say to enter withholding under another provision of the Code, such as section 1441, if the distribution was also subject to it.
Attach Copy A to Form 8288, give Copy B to the partner (transferee) and keep Copy C for the partnership's records.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach Copy A to Form 8288. It points to the Instructions for Form 8288 for more information.
The instructions say to provide Copy B to the partner (transferee) subject to withholding.
The instructions say the partnership retains Copy C for its records.
The instructions say to prepare a separate Form 8288-C for each transfer subject to withholding under section 1446(f)(4), for each distribution.
If the partnership withholds more than the transferee's section 1446(f)(1) liability, the instructions say the transferee may be able to claim a refund by attaching Form(s) 8288-C to Form 8288.
The instructions say not to use Form 8288-C to claim a credit against income tax liability or attach it to an income tax return.
8288
56 fields, 2 pages
8288-A
60 fields, 5 pages
8288-B
51 fields, 4 pages
The form is labeled for the withholding agent (partnership). The IRS About page says transferees or partnerships (if a transferee fails to withhold) that are required to withhold part of the amount realized use it with Form 8288.
No tool matches that search.
The partnership, as withholding agent. The instructions say it issues the form to a transferee when it withholds on a distribution under section 1446(f)(4).
The instructions say this happens when the transferee failed to withhold the entire amount required under section 1446(f)(1), or failed to certify to the partnership the extent to which it satisfied that obligation.
No. The instructions say not to use it to claim a credit against income tax liability or attach it to an income tax return.
The instructions say that if the partnership withholds more than the transferee's section 1446(f)(1) liability, the transferee may be able to claim a refund by attaching Form(s) 8288-C to Form 8288.
Form 8288-A reports withholding under section 1445 or 1446(f)(1) by a buyer or other transferee. Form 8288-C reports withholding a partnership makes on a distribution under section 1446(f)(4).
That is how the PDF prints its edition date: Form 8288-C (January 2023).