7220

Prevailing Wage and Apprenticeship (PWA) Verification and Corrections

Agency
IRS
Revision
December 2025
Fillable fields
653
Pages
5
Official source
IRS form page
Checked
October 21, 2026
Fill 7220 online
Page 1 of form 7220

Form 7220: Prevailing Wage and Apprenticeship (PWA) Verification and Corrections

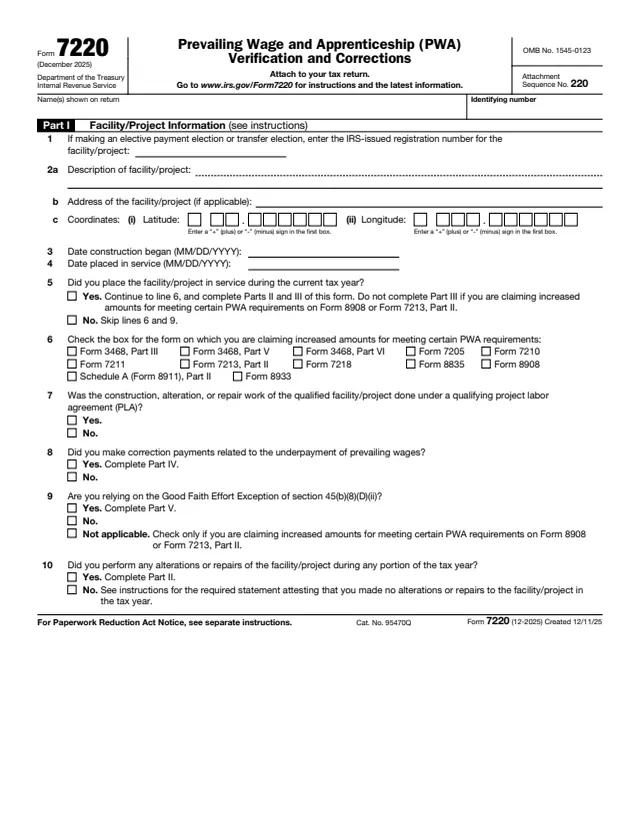
Form 7220, Prevailing Wage and Apprenticeship (PWA) Verification and Corrections, is listed as a new form in its instructions. The instructions say it is used to report information for each facility for which increased credit or deduction amounts are claimed for satisfying certain PWA requirements, and to calculate any penalties for failing to satisfy those requirements. For these instructions, a facility also includes a property, project, technology, equipment or residence.

The increased amounts themselves are claimed on other forms: Form 3468, Form 7205, Form 7210, Form 7211, Form 7213, Form 7218, Form 8835, Form 8908, Schedule A (Form 8911) and Form 8933. Form 7220 holds the supporting detail: facility dates, wages and fringe benefits paid to laborers and mechanics, apprentice hours, correction payments and any Good Faith Effort Exception. The form says to attach it to the tax return.

This page hosts the December 2025 edition. You can fill it out free in your browser on this page and download it without an account.

What's on Form 7220

Part I: Facility/Project Information

Ten lines: the IRS-issued registration number for an elective payment or transfer election, a description, address and coordinates, the dates construction began and the facility was placed in service, the form claiming the increased amounts, and yes or no questions that point to Parts II to V.

Part II: Prevailing wages paid

For each entity directly employing laborers and mechanics: name, EIN, labor or work classification, number of workers, total hours, total hourly wages and bona fide fringe benefits, with column (h) adding wages and fringe benefits.

Part III: Apprenticeship requirements and penalties

The same entity details for qualified apprentices, plus column (h) for labor hours that did not meet the requirements of IRC 45(b)(8)(A) and (C), and column (i) for the penalty, which is column (h) times $50.

Part IV: Prevailing wage corrections and penalties

Laborers and mechanics covered by the penalty waiver, those for whom a penalty payment is reported, a penalty of column (e) times $5,000 in column (f), and correction payments and interest paid in column (g).

Part V: Good Faith Effort Exception

Apprentices requested in each classification, hours needed to satisfy the Apprenticeship Requirements, hours requested and denied, and boxes for a request that was denied or partially denied, or got no response (deemed denial).

How to fill out Form 7220

  1. 1

    Lines 1 to 4

    Enter the IRS pre-filing registration number if applicable, a description of the facility, its address and coordinates, the date construction began and the date it was originally placed in service. The form says to enter a plus or minus sign in the first box of each coordinate.

  2. 2

    Lines 5 and 6

    Check Yes on line 5 if the facility was placed in service in the current tax year and complete Parts II and III, though Part III is skipped for Form 8908 or Form 7213, Part II. If No, skip lines 6 and 9. On line 6, check the form claiming the increased amounts.

  3. 3

    Lines 7 to 10

    Answer the questions on a qualifying project labor agreement, correction payments (Yes leads to Part IV), the Good Faith Effort Exception (Yes leads to Part V) and alterations or repairs in the year (Yes leads to Part II). The instructions say a No on line 10 calls for an attached statement that none were performed.

  4. 4

    Parts II to V, columns (a) to (c)

    On each row, enter the entity directly employing the workers, its EIN and each labor or work classification as defined by the Davis-Bacon Act. The instructions say to complete as many copies of each part as necessary and carry totals from attached copies to the 'If applicable' line.

  5. 5

    Penalty columns

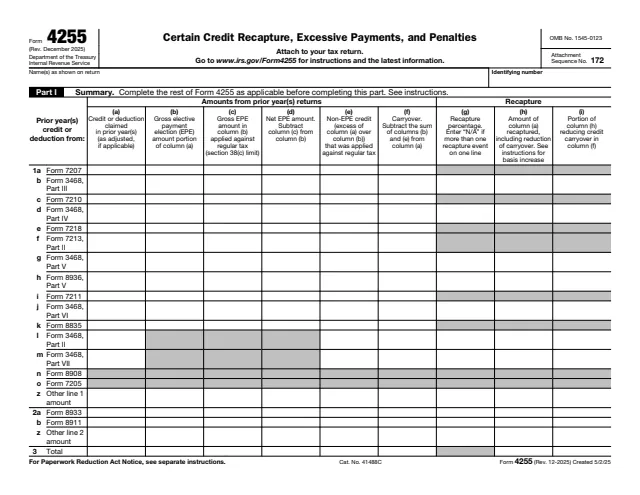
    In Part III, multiply column (h) by $50 for column (i). In Part IV, multiply column (e) by $5,000 for column (f). The instructions say line 18 of these columns is reported on Form 4255, Part I, columns (p) and (o).

Why fill Form 7220 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, penalties and statements

Where it goes

The form says 'Attach to your tax return.'

No alterations or repairs statement

When line 10 is No, the instructions call for a statement with the taxpayer's name, taxpayer identification number and facility description, a declaration that no alterations or repairs were performed in the tax year, and a signed penalties of perjury declaration.

Prevailing wage penalty

The instructions describe correction payments of the wage shortfall plus interest, and a penalty of $5,000 multiplied by the number of laborers and mechanics paid below the prevailing wage rate.

Penalty waiver

The instructions say the penalty payment is waived if correction payments are made by the last day of the first month after the end of the calendar quarter of the failure, and the failure occurred in less than 10% of pay periods or underpayments were not more than 5% below the prevailing wage rate amount.

Apprenticeship cure provision

If the Good Faith Effort Exception does not apply, the instructions describe a penalty of $50 multiplied by the labor hours for which the labor hours or participation requirement was not satisfied.

Penalties carry to Form 4255

The form says to use the amounts in Part III, column (i) and Part IV, column (f) to complete Form 4255.

Who files Form 7220?

  • Taxpayers claiming increased PWA amounts

    The instructions say Form 7220 reports information for each facility for which increased credit or deduction amounts are claimed for satisfying certain PWA requirements.

  • One form for each facility

    A separate Form 7220 is filed for each facility. The instructions give the example that three Forms 8835 with increased credit amounts call for three Forms 7220.

  • Alterations or repairs in later years

    The instructions say a separate Form 7220 reports ongoing compliance with the prevailing wage requirements for alterations or repairs on facilities placed in service in a prior year for which increased amounts were claimed.

  • Contractors appear on the form

    Parts II to V list each entity that directly employs the laborers, mechanics or apprentices. The instructions say this could be the taxpayer, a contractor or a subcontractor.

  • Not needed under the BOC or One Megawatt exception

    The instructions say a taxpayer claiming the increased amounts that satisfies the Beginning of Construction (BOC) or One Megawatt exception is not required to file Form 7220.

The form is completed by the taxpayer claiming the increased amounts and attached to that taxpayer's return. The instructions describe the cases below.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 7220

Is Form 7220 filed on its own?

No. The form says to attach it to your tax return.

Is a separate Form 7220 needed for each facility?

Yes. The instructions say to file a separate Form 7220 for each facility for which increased credit or deduction amounts are claimed.

When is Form 7220 not required?

The instructions say a taxpayer claiming the increased amounts that satisfies the Beginning of Construction (BOC) or One Megawatt exception is not required to file Form 7220.

What counts as a facility?

For the instructions, the term facility also includes property, project, technology, equipment or residence, as applicable.

What is the Good Faith Effort Exception?

The instructions say the apprenticeship requirements are deemed satisfied if qualified apprentices were requested from a registered apprenticeship program and the request was denied, or the program did not respond within 5 days. Part V reports those requests.

Where do the penalty amounts go?

The form says to use the amounts in Part III, column (i) and Part IV, column (f) to complete Form 4255.