3468

Investment Credit

Agency
IRS
Revision
2025
Fillable fields
321
Pages
12
Official source
IRS form page
Checked
October 21, 2026
Fill 3468 online
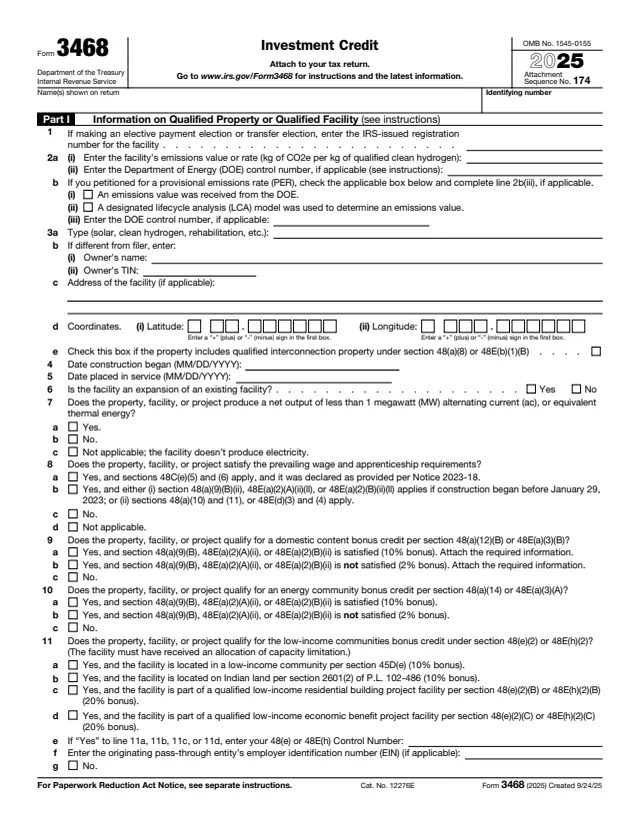
Page 1 of form 3468

Form 3468: Investment Credit

Form 3468, Investment Credit, is the form used to claim the investment credit. The 2025 instructions say to use a separate Form 3468 for each facility or property, completing Part I for the facility or property information and the appropriate part, Parts II through VII, to compute the credit for it.

The 2025 form covers the qualifying advanced coal project and qualifying gasification project credits (Part II), the qualifying advanced energy project credit under section 48C (Part III), the advanced manufacturing investment credit under section 48D (Part IV), the clean electricity investment credit under section 48E (Part V), the energy credit under section 48 (Part VI) and the rehabilitation credit under section 47 (Part VII).

The form says "Attach to your tax return." The total of each part is reported on a line of Form 3800, General Business Credit, Part III. You can fill out Form 3468 free in your browser on this page and download it without an account.

What's on Form 3468

Part I: facility or property information

Registration number, emissions values, type of property, owner if different, address and coordinates, dates construction began and placed in service, and questions on net output, prevailing wage and apprenticeship, domestic content, energy community and low-income communities bonuses, capacity and lessee elections.

Parts II and III

Part II figures the qualifying advanced coal project credit under section 48A and the qualifying gasification project credit under section 48B. Part III figures the qualifying advanced energy project credit under section 48C.

Part IV: advanced manufacturing investment credit

Check a semiconductor manufacturing facility or semiconductor equipment manufacturing facility, enter the basis of the qualified investment, and multiply it by 25% (0.25) (35% (0.35) for property placed in service after 2025), as the form prints.

Part V: clean electricity investment credit

Section A covers qualified clean electricity facilities, Section B covers qualified energy storage technology, and Section C holds totals, reductions for subsidized energy financing or private activity bonds, and the credit phaseout.

Part VI: energy credit

Sections A through N cover geothermal, solar, fuel cell, microturbine, combined heat and power, small wind, waste energy recovery, geothermal heat pump, energy storage, biogas, microgrid controllers, qualified investment credit facility and clean hydrogen property, then totals.

Part VII: rehabilitation credit

Questions on a prior section 170(h) deduction and the section 47(d)(5) election, the measuring period, adjusted basis and qualified rehabilitation expenditures, line 1j that multiplies line 1g by 4% (0.04) for certified historic structures, and National Park Service (NPS) details.

How to fill out Form 3468

  1. 1

    One form per facility

    Use a separate Form 3468 for each facility or property. Enter the name(s) shown on the return and the identifying number at the top.

  2. 2

    Complete the Part I lines that apply

    The instructions give a table of Part I lines for each part. For example, Part VII filers complete lines 1, 3a, 3b, 3c, 3d, 4, 5 and 13, and Part V filers complete lines 1 and 2b through 13.

  3. 3

    Answer the bonus questions

    Lines 7 to 11 ask about net output, prevailing wage and apprenticeship, domestic content, energy community and low-income communities. The boxes checked here set the percentages entered later in Parts III, V and VI.

  4. 4

    Figure the credit in the right part

    Complete the part for the credit being claimed. Each part multiplies the qualified investment or basis by the rate the form prints and adds any unused investment credit from cooperatives.

  5. 5

    Pass-through entities

    Partnerships, S corporations, estates and trusts complete the Part I facility lines and only the lines the instructions list for each part, then attach a statement to Schedule K-1 with each owner's share.

  6. 6

    Carry the totals to Form 3800

    Part II, line 7 goes to Form 3800, Part III, line 1a; Part III, line 3 to line 1d; Part IV, line 3 to line 1o; Part V, line 11 to line 1v; Part VI, line 32 to line 4a; and Part VII, line 3 to line 4k.

Why fill Form 3468 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, registration and recapture

Where it goes

The form says "Attach to your tax return." The instructions say a credit amount for a facility or property is reported on the applicable lines of Form 3800, Part III, and both forms are attached to the return.

Pre-filing registration

The instructions say a pre-filing registration is completed for each property or facility before filing when an elective payment or transfer election is made for the credit in Part III, IV, V or VI. They point to IRS.gov/Register and Pub. 5884.

Form 7220

The instructions say filers claiming the increased credit amount for meeting the prevailing wage and apprenticeship requirements under section 48C, 48E or 48 file Form 7220 for each facility, property, project or energy storage technology.

Recapture

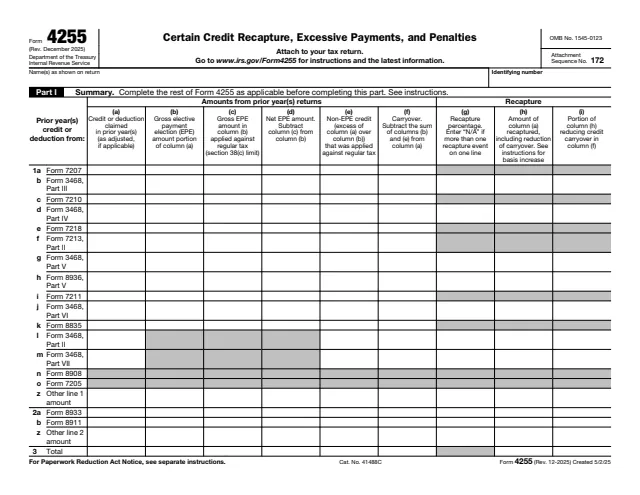
The instructions list events that can cause recapture, such as disposing of investment credit property before the end of 5 full years after it was placed in service. Recapture amounts are reported on Form 4255.

Recent developments

The About page lists corrections to the 2025 Instructions for Form 3468 and a reporting relief item for tax years 2023, 2024 and 2025 for Forms 3468 and 8835.

Who fills out Form 3468?

  • Taxpayers claiming the credit

    The form is attached to the filer's income tax return. The instructions note that an individual who files electronically sends a paper Form 8453 if attachments are required for Form 3468.

  • Partnerships, S corporations, estates and trusts

    The instructions say to complete and attach a separate Form 3468 for each facility or property used in the trade or business, even if the entity cannot claim the credit, and to attach a statement to Schedule K-1.

  • Cooperative patrons

    Patrons, including cooperatives that are patrons in other cooperatives, file a separate Form 3468 for unused investment credits allocated from cooperatives and enter "Unused Investment Credit from Cooperatives" on Part I, line 3a.

  • Tax-exempt and governmental entities

    The instructions say applicable entities, such as certain tax-exempt and governmental entities, can elect to treat section 48C, 48E and 48 credits as a payment of income tax, filing Form 3468 and Form 3800 with Form 990-T or other applicable return.

  • Filers electing payment or transfer

    Filers making an elective payment election or a transfer election enter the IRS-issued registration number for the facility on Part I, line 1. The instructions describe a pre-filing registration before the return is filed.

The filer claiming the credit attaches Form 3468 to its own tax return. The instructions describe individuals, partnerships, S corporations, estates, trusts, cooperative patrons and applicable entities.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 3468

Does each facility need its own Form 3468?

Yes. The instructions say to complete a separate Form 3468 to claim an investment credit for each facility or property.

Where does the Form 3468 credit go?

The total of each part is reported on a line of Form 3800, General Business Credit, Part III. The form names the line at the end of each part.

What rate does Part IV use?

The form says to multiply line 1b by 25% (0.25), or 35% (0.35) for property placed in service after 2025. The instructions say the rate remains 25% for property placed in service before 2026.

Does a partnership that cannot claim the credit still file Form 3468?

The instructions say S corporations, partnerships, estates and trusts complete and attach a separate Form 3468 for each facility or property, even if they cannot claim the credit, so owners can figure their share.

Can a tax-exempt organization use Form 3468?

The instructions say applicable entities can elect to treat section 48C, 48E and 48 credits as a payment of income tax, and file Form 3468, Form 3800 and Form 990-T or other applicable return.

What happens if the property is sold early?

The instructions say the credit may be refigured and recaptured if the property is disposed of before the end of 5 full years after it was placed in service. Recapture is reported on Form 4255.