Part I, columns (a) to (f)
Amounts from prior year returns for each credit line: the credit or deduction claimed, the gross and net elective payment election (EPE) amounts, the non-EPE credit applied against regular tax, and the carryover.
4255
Certain Credit Recapture, Excessive Payments, and Penalties
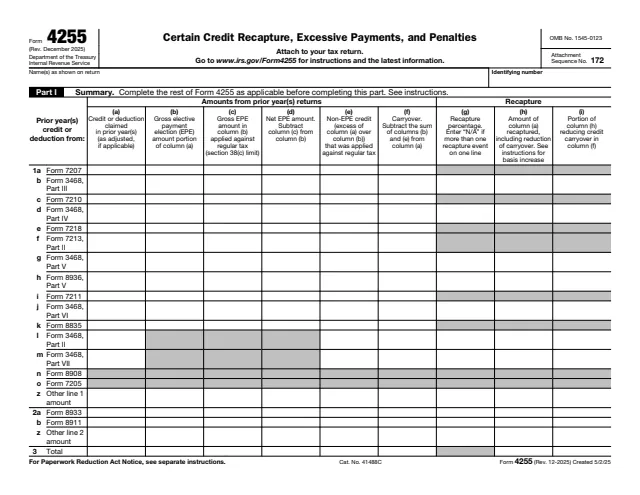
Form 4255, Certain Credit Recapture, Excessive Payments, and Penalties, is attached to a tax return. The instructions say it is used to figure the increase in the amount due for certain credit recaptures, excessive payments, excessive credit transfers, and penalty amounts for failure to satisfy the prevailing wage and apprenticeship (PWA) requirements.
Part I is a summary with a line for each credit form it covers, such as Form 7207, the parts of Form 3468, Form 8835, Form 8933 and Form 8911. Part II refigures the investment credit for properties A through D and figures recapture from an increase in nonqualified nonrecourse financing or from a disposition or cessation of use. Part III figures emissions tier recapture for property that is part of a specified clean hydrogen production facility.
This page hosts the December 2025 revision. You can fill it out free in your browser on this page and download it without an account.
Amounts from prior year returns for each credit line: the credit or deduction claimed, the gross and net elective payment election (EPE) amounts, the non-EPE credit applied against regular tax, and the carryover.
Recapture: the recapture percentage, the amount recaptured including reduction of carryover, and how that amount splits across the carryover, non-EPE credit, gross EPE and net EPE amounts.
Excessive credit transfers, excessive payments, prevailing wage and apprenticeship penalty amounts, then totals: amounts that can and cannot be reduced by nonrefundable credits, and two summing columns.
Section A describes properties A through D, Section B refigures the original credit, Section C covers an increase in nonqualified nonrecourse financing, and Section D covers disposition, cessation of use or certain advanced manufacturing expansions.
Nine lines for property that is part of a specified clean hydrogen production facility. Line 9 multiplies line 8 by 20% (0.20) and is entered in Part I, line 1j, column (h).
Part I says to complete the rest of Form 4255 as applicable before completing it, and the instructions repeat that Parts II and III come first.
Describe each property and credit on lines A through D, then enter the original rate of credit, the credit base, any net change in nonqualified nonrecourse financing and the refigured credit. The instructions say to attach additional Forms 4255 for more properties.
Enter the date placed in service, using the first day of that month, and the date the property ceased to be qualified credit property. Lines 12 to 16 count full years, apply the recapture percentage from the instructions' table and figure the recapture tax.
Enter credit or deduction information from each credit form and Form 3800, then the recapture in column (h) and any excessive payments, transfers and PWA penalties. The instructions give ratios for splitting PWA penalties among net EPE, non-net EPE and non-EPE amounts.
Carry line 3, columns (q) and (r), to the tax return. The instructions use Form 1120, Schedule J, lines 1g and 9a as the example, and Form 1065, line 27, or Form 1120-S, line 23c, for certain partnership and S corporation amounts.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says 'Attach to your tax return.'
The instructions say the recapture period runs until the end of 5 full years after the property was placed in service.
The instructions list a transfer because of the taxpayer's death, a transfer between spouses or incident to divorce, a transaction to which section 381(a) applies, and a mere change in the form of conducting a trade or business.
The instructions say remaining carryforwards and carrybacks are reduced by the recapture percentage, and the property's basis is increased by 100% or 50% of the recapture tax and related adjustments, depending on the type of property.
If there is no EPE, the instructions say to enter the full PWA penalty amounts in columns (o)(3) and/or (p)(3).
7220
653 fields, 5 pages
3468
321 fields, 12 pages

3800
1,921 fields, 9 pages

1065
440 fields, 6 pages

1120
481 fields, 6 pages

1120-S
390 fields, 5 pages
The form is attached to the filer's own tax return. The instructions describe the situations below.
No tool matches that search.
No. The form says to attach it to your tax return.
Part I says to complete the rest of Form 4255 as applicable first, so Parts II and III come before the Part I summary.
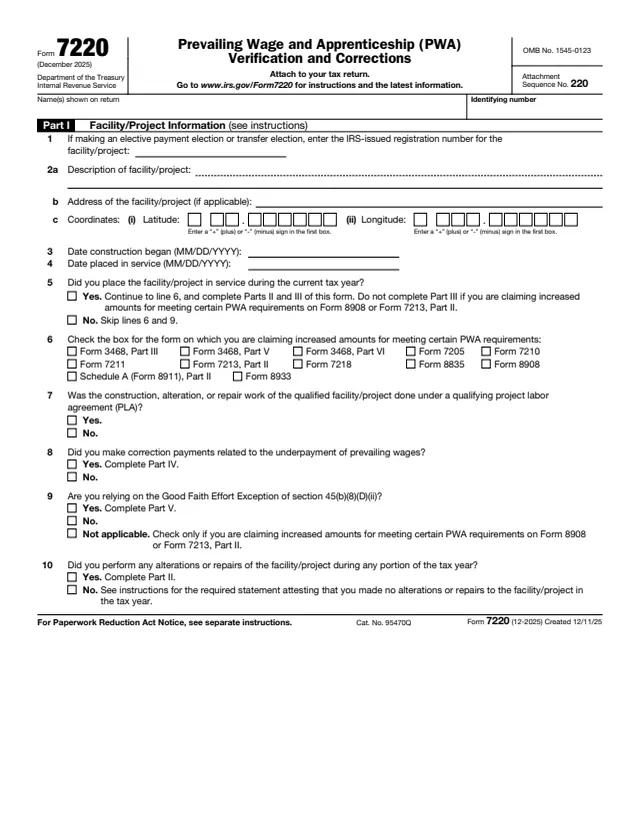
The instructions say columns (o)(1) to (o)(3) come from Form 7220, Part IV, column (f), and columns (p)(1) to (p)(3) from Form 7220, Part III, column (i).
The instructions say to complete and attach additional Forms 4255 to list all the properties for which the credit is refigured.
The instructions say the excessive payments, excessive credit transfers and penalties section was renamed, and columns (m), (n), (o) and (p) were expanded to allow more detailed reporting.
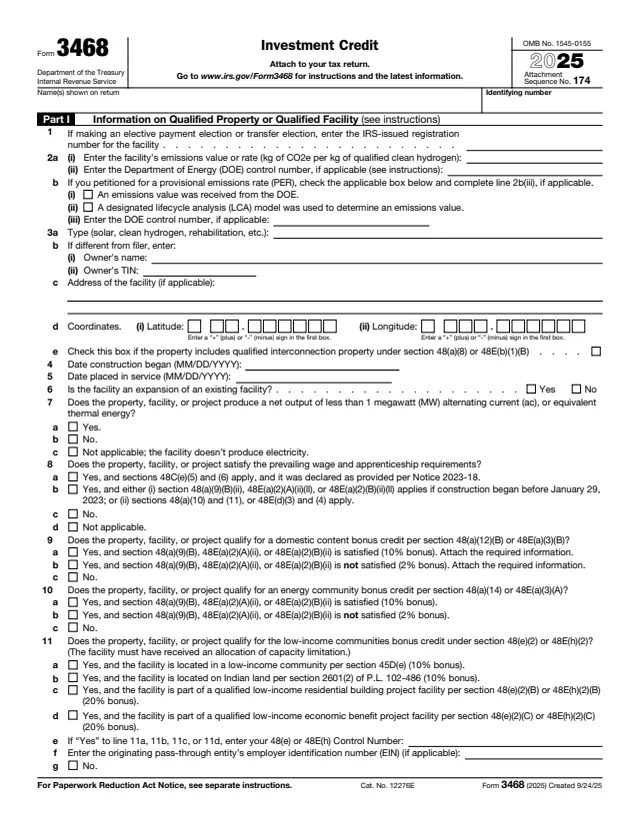
The instructions say a partner, shareholder or beneficiary will need a copy of the original Form 3468 to complete this form.