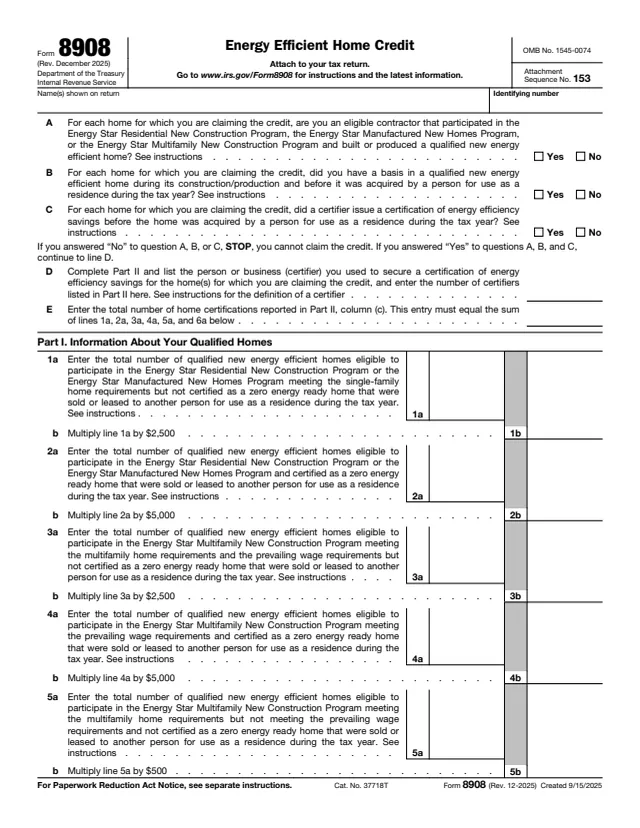
Items A, B and C
Three yes or no questions: Energy Star program participation, a basis in the home during construction or production, and a certification issued before the home was acquired.
8908
Energy Efficient Home Credit
Form 8908 is the IRS form for the energy efficient home credit. The IRS says eligible contractors use it to claim a credit for each qualified energy efficient home sold or leased to another person during the tax year for use as a residence. The instructions say the credit is based on the energy saving requirements of the home and is part of the general business credit.
The form opens with three yes or no questions, then counts homes by Energy Star program, zero energy ready certification and prevailing wage status, and multiplies each count by a set amount per home. Part II lists the certifiers and Part III lists the addresses of the first 20 homes. The form says to attach it to your tax return.
The instructions say the December 2025 revision is for tax years beginning in 2025 or later. You can fill out Form 8908 free in your browser on this page and download the result without an account.
Three yes or no questions: Energy Star program participation, a basis in the home during construction or production, and a certification issued before the home was acquired.
The number of certifiers listed in Part II, and the total number of home certifications from Part II, column (c).
Counts of homes by program and certification. The form multiplies them by $2,500, $5,000, $2,500, $5,000, $500 and $1,000 on lines 1b to 6b.
Line 7 holds credit from partnerships and S corporations. Line 8 adds lines 1b to 6b and line 7 for the total credit.
Up to 38 lines with the certifier's name, its state, the number of your homes it certified and the number of modified certifications. Column (e) is reserved.
Twenty lines for the street address, city, state and ZIP code of each home.
Check Yes or No for each question. The form says that if you answered No to question A, B or C, stop, because the credit cannot be claimed.
List each certifier in column (a) with its two-letter state in column (b) and the homes it certified in column (c). The instructions say item E equals the sum of lines 1a to 6a.
Place each home on the line that matches its program, zero energy ready status and, for multifamily homes, prevailing wage status, then multiply on the b lines.
The instructions say a credit on line 3b or 4b needs Form 7220 completed and attached to the tax return to claim the increased amount.
Enter credits from Schedule K-1 (Form 1065), box 15 (code AM) and Schedule K-1 (Form 1120-S), box 13 (code AM) on line 7, then add to line 8.
Enter the number and street, city, two-letter state and nine-digit ZIP code for the first 20 homes for which the credit is claimed.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. It has no separate mailing address.
The form says partnerships and S corporations report the line 8 amount on Schedule K, and all others report it on Form 3800, Part III, line 1p.
The instructions say the credit cannot be claimed for qualified new energy efficient homes acquired after June 30, 2026.
The instructions say to use the December 2025 revision for tax years beginning in 2025 or later and prior revisions for earlier tax years.
The instructions say the construction expenses of each home are generally reduced by the amount of the credit when figuring basis, with an exception for the low-income housing credit.
The IRS About page lists a clarification dated 29-SEPT-2026 for partnerships and S corporations completing the form only to report credits passed through by another partnership or S corporation.
The instructions say an eligible contractor may claim the credit for a qualified new energy efficient home acquired by a person from that contractor during the tax year for use as a residence.
No tool matches that search.
The instructions say an eligible contractor may claim it for a qualified new energy efficient home that a person acquires from that contractor during the tax year for use as a residence.
The form prints $2,500 on lines 1b and 3b, $5,000 on lines 2b and 4b, $500 on line 5b and $1,000 on line 6b. Which line applies depends on the program, zero energy ready status and prevailing wage status.
The instructions say taxpayers other than partnerships and S corporations are not required to complete the form when their only source of the credit is a partnership or S corporation. They can report it on Form 3800, Part III, line 1p.
The instructions say P.L. 119-21 changed the termination date to June 30, 2026, and the credit cannot be claimed for homes acquired after that date.
The instructions say a home leased by a person from an eligible contractor for use as a residence during the tax year is considered acquired. A home the contractor keeps for its own residence is not.
The instructions say to fill out Part III for the first 20 qualified new energy efficient homes for which the credit is claimed.