8933

Carbon Oxide Sequestration Credit

Agency
IRS
Revision
Rev. December 2025
Fillable fields
141
Pages
4
Official source
IRS form page
Checked
October 21, 2026
Fill 8933 online
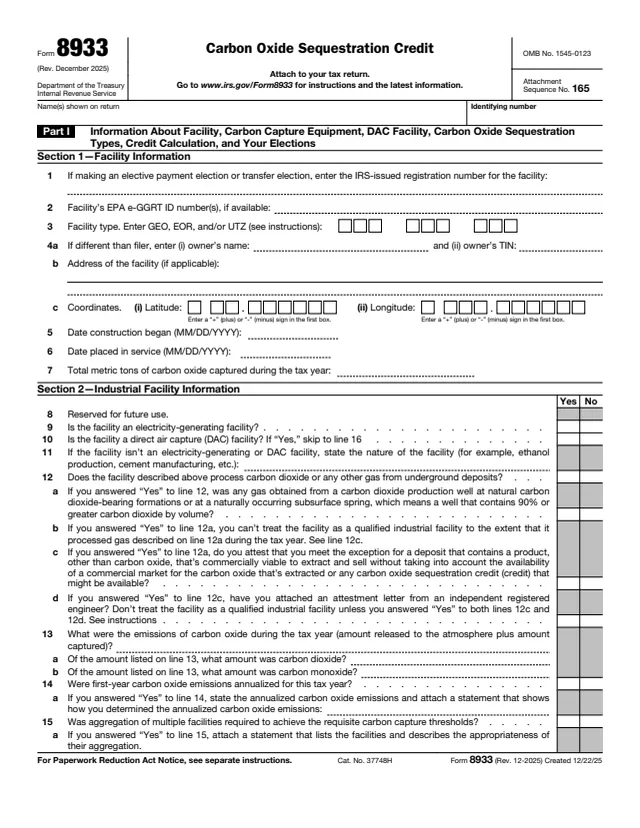
Page 1 of form 8933

Form 8933: Carbon Oxide Sequestration Credit

The IRS says to use Form 8933 to claim the section 45Q carbon oxide sequestration credit. The form says to attach it to your tax return.

Part I collects information about the facility, the carbon capture equipment or direct air capture (DAC) facility, the type of sequestration (disposal in geological storage, use as a tertiary injectant in an enhanced oil or natural gas recovery project, or utilization) and the elections made. Part II is a set of check boxes about the filer. Part III figures the credit in metric tons times the credit rate or applicable dollar amount, applies the reduction for tax-exempt bond financing, and adds credits elected to the filer and credits from partnerships and S corporations.

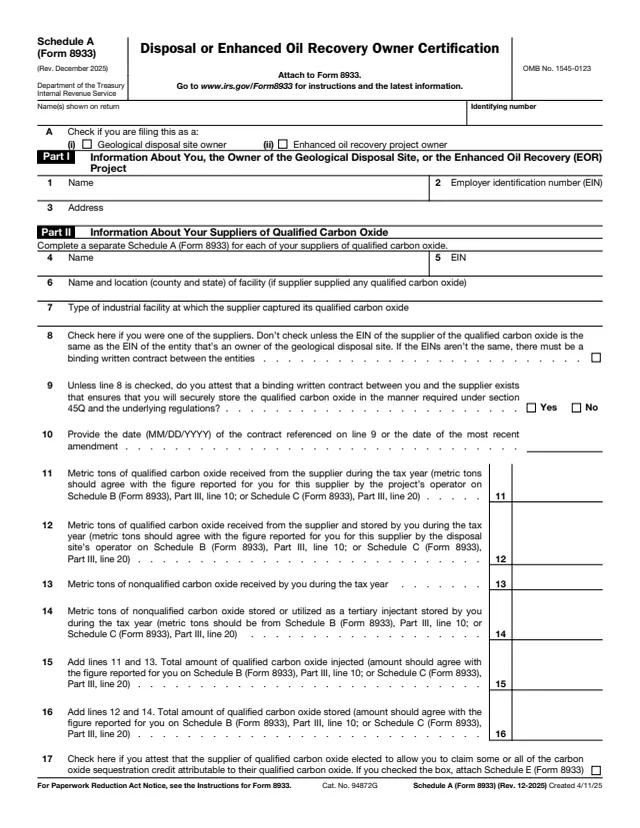
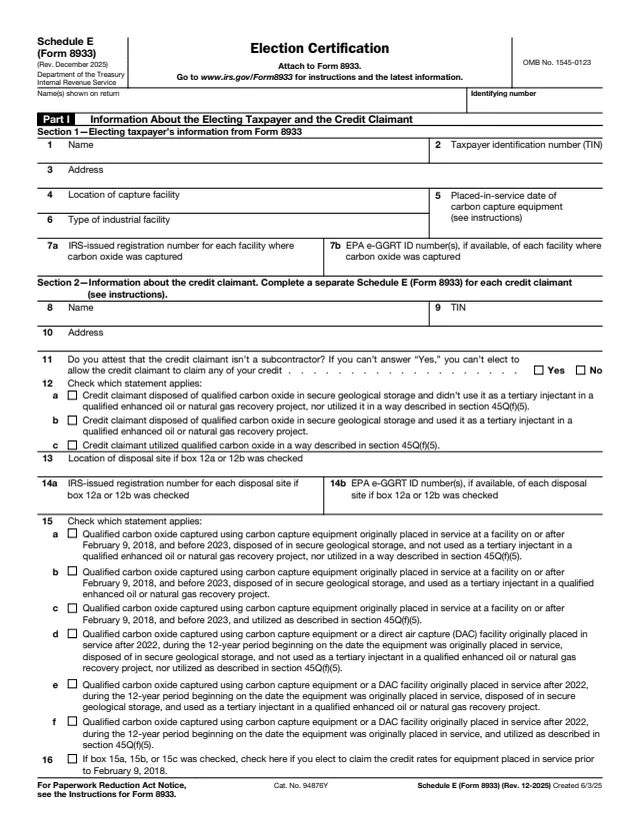
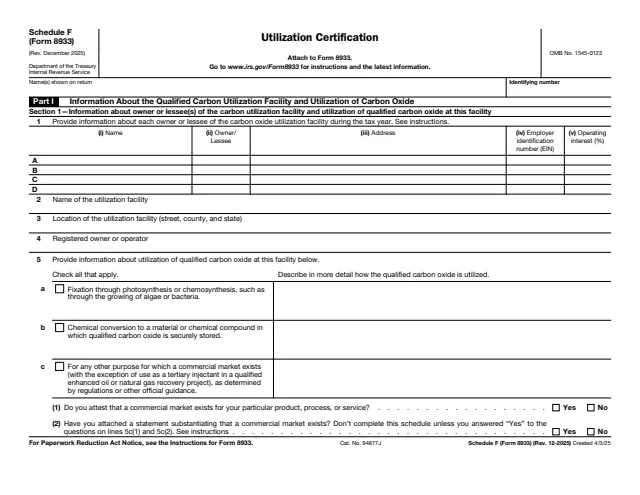
Schedules A through F (Form 8933) are certifications from owners and operators of disposal sites, enhanced oil recovery projects and utilization facilities, and cover elections and recapture. You can fill out Form 8933 free in your browser on this page and download it without an account.

What's on Form 8933

Part I, Section 1: facility

Lines 1 to 7: the IRS-issued registration number for an elective payment or transfer election, the EPA e-GGRT ID, the facility type (GEO, EOR, UTZ), the owner if different, address or coordinates, construction and placed-in-service dates, and metric tons captured.

Part I, Section 2: industrial facility

Lines 8 to 15: whether the facility generates electricity or is a DAC facility, its nature, gas from underground deposits, carbon oxide emissions, annualized first-year emissions and aggregation of facilities.

Part I, Section 3: equipment and DAC

Lines 16 to 25: DAC capture, equipment placed in service dates, ownership of the equipment, capture capacity, additional equipment and the 80/20 rule, and the total carbon oxide captured.

Part I, Section 4: credit and elections

Lines 26 to 33: contractual parties, the section 45Q(f)(3)(B), 45Q(b)(3) and 45Q(f)(6) elections, the credit rates on lines 28a to 28c, the disposal, injection and utilization paths, and the prevailing wage and apprenticeship question.

Part II: information about you

Eight check boxes: an approved lifecycle analysis (LCA), capture, disposal or utilization, credits elected away or received, and the elections under section 45Q(b)(3), 45Q(f)(6) and 45Q(f)(9).

Part III: credit calculations

Lines 1 to 3 for disposal, injection and utilization, line 4 credit before reduction, lines 5a to 6 for tax-exempt bonds, line 7 elected credits, line 8 pass-through credits, line 9 total and line 10 recapture.

How to fill out Form 8933

  1. 1

    Part I, Section 1

    On line 1 enter the pre-filing registration number from the IRS if making an elective payment or transfer election. On line 3 enter GEO for geological storage, EOR for enhanced oil or natural gas recovery, and/or UTZ for utilization. The instructions say a separate Form 8933 is completed for each facility when facilities took different paths.

  2. 2

    Sections 2 to 4

    Answer the yes and no questions about the facility, the equipment and the elections, and attach the statements the lines ask for, such as the annualized emissions statement on line 14a or the aggregation statement on line 15a.

  3. 3

    Credit rate on lines 1g, 2g and 3i

    Line 28 prints the rates for tax years beginning in 2025, for example $28.43 and $14.21 under the section 45Q(b)(3) election, and $36 and $26 for a DAC facility after 2022. The instructions list the other applicable dollar amounts.

  4. 4

    Part III, lines 1 to 4

    Enter metric tons for each path, subtract tons for which another person claims the credit (attach Schedule E (Form 8933)), and multiply by the rate. If Part I, line 33 is Yes, the form says to multiply by 5.0. Line 3g is the displacement factor from the approved LCA.

  5. 5

    Lines 5a to 6

    If tax-exempt bond proceeds financed the facility, divide those proceeds by additions to the capital account (line 5a), multiply line 4 by that fraction (line 5b) and by 15% (0.15) (line 5c), and subtract the smaller of the two from line 4. Otherwise enter line 4 on line 6.

  6. 6

    Lines 7 to 10

    Line 7 holds credits other taxpayers elected to allow you, line 8 credits from partnerships and S corporations. Line 9 goes to Schedule K for partnerships and S corporations and to Form 3800, Part III, line 1x for all others. Line 10 reports recapture with Schedule D (Form 8933).

Why fill Form 8933 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

How it is filed, schedules and timing

Attach to the return

The form says to attach it to your tax return. It carries Attachment Sequence No. 165.

Schedules A to F

The About page says Schedule A is for owners of a disposal site or EOR project, B for disposal site operators, C for EOR project operators, D for recapture events, E for the section 45Q(f)(3)(B) election and F for utilization facility owners.

Pre-filing registration

The instructions say a filer intending to make an elective payment or transfer election on Form 3800 completes a pre-filing registration for each facility before filing the return, at IRS.gov/Register.

Election timing

The instructions say the section 45Q(f)(3)(B) election is made annually by filing Schedule E (Form 8933) no later than the time prescribed by law (including extensions) for filing the return, with a separate election for each facility.

Prevailing wage and apprenticeship

For each qualified facility claiming the increased credit amount for meeting the prevailing wage and apprenticeship requirements, the instructions say a separate Form 7220 is filed.

Prohibited foreign entities

The instructions say no credit is allowed for any tax year beginning after July 4, 2025, if the taxpayer is a specified foreign entity or a foreign-influenced entity as defined in section 7701(a)(51).

Who files Form 8933?

  • Owners of carbon capture equipment

    For equipment placed in service on or after February 9, 2018, the instructions say the credit is attributable to the person that owns the equipment and physically or contractually ensures the disposal, utilization, or use as a tertiary injectant of the carbon oxide.

  • Credit claimants under an election

    A person to whom another taxpayer elected under section 45Q(f)(3)(B) to allow the credit reports it on line 7, with a copy of the electing taxpayer's Schedule E (Form 8933).

  • Applicable entities making a payment election

    The instructions say applicable entities making the elective payment election file Form 8933 with required schedules and statements, Form 3800, and Form 990-T or other applicable income tax return.

  • Partners in section 761(a) partnerships

    The instructions say partnerships with valid section 761(a) elections aren't required to file the form. The partner completes and files it in a manner commensurate with its undivided ownership interest in the facility.

  • Not for pass-through credit only

    Taxpayers other than partnerships or S corporations whose only source of this credit is from those pass-through entities aren't required to file the form. The instructions say to report the credit directly on line 1x in Part III of Form 3800.

The form is attached to the tax return of the person the instructions treat as the one the credit is attributable to, or of a credit claimant.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 8933

What is Form 8933 used for?

The IRS says to use it to claim the section 45Q carbon oxide sequestration credit.

Who can claim the credit?

For equipment placed in service on or after February 9, 2018, the instructions say it is the person that owns the equipment and physically or contractually ensures the disposal, utilization, or use as a tertiary injectant of the carbon oxide.

Is Form 8933 needed if the only credit comes from a partnership or S corporation?

The instructions say taxpayers other than partnerships or S corporations in that case aren't required to file it and report the credit directly on line 1x in Part III of Form 3800.

What do GEO, EOR and UTZ mean on line 3?

GEO is disposal in geological storage, EOR is enhanced oil or natural gas recovery, and UTZ is utilization. A single facility can enter more than one code.

What is the rate for equipment placed in service after July 4, 2025?

The instructions say that for facilities or equipment placed in service after July 4, 2025, and before 2027, the credit is $17 per metric ton of qualified carbon oxide.

What is a recapture event?

The instructions say it occurs when qualified carbon oxide for which a credit was claimed ceases to be captured, disposed of, or used as a tertiary injectant during the recapture period. It is reported on Schedule D (Form 8933) and line 10.