Header
Name and identifying number of the person filing Form 5471, the foreign corporation's name, its EIN if any, and a reference ID number.
5471
Organization or Reorganization of Foreign Corporation, and Acquisitions and Dispositions of its Stock
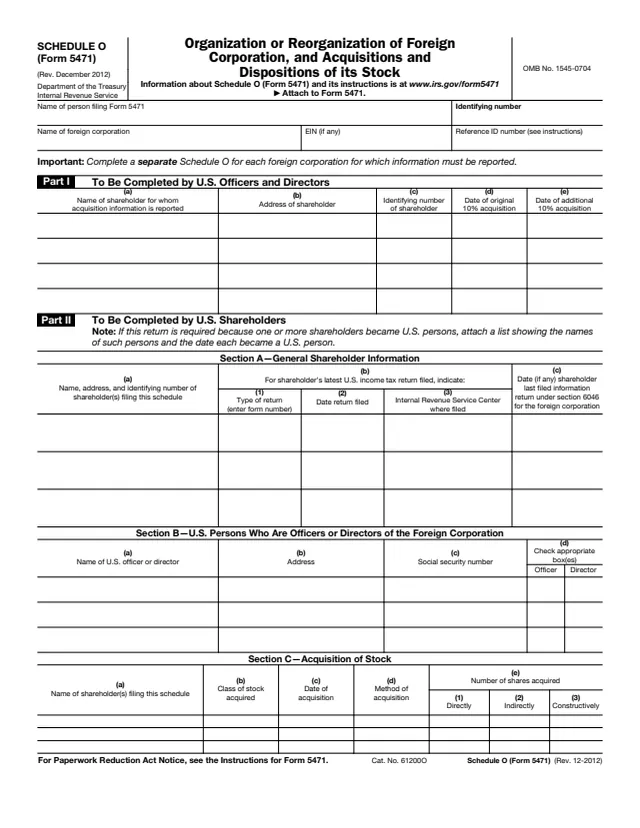
Schedule O (Form 5471) reports the organization or reorganization of a foreign corporation and the acquisition or disposition of its stock. Its full IRS title is Organization or Reorganization of Foreign Corporation, and Acquisitions and Dispositions of its Stock. It is completed by certain U.S. persons who are officers, directors or shareholders, not by the foreign corporation, and the form says "Attach to Form 5471."
The Form 5471 instructions say every U.S. citizen or resident described in Category 2 completes Part I, and every U.S. person described in Category 3 completes Part II. Category 3 includes a U.S. person who acquires stock that meets the 10% stock ownership requirement and a U.S. person who disposes of enough stock to fall below it. The schedule reports acquisitions, dispositions, and organizations or reorganizations that occurred during the filer's tax year.
This page shows the Rev. December 2012 schedule. You can fill out the PDF free in your browser on this page and download the result without an account.
Name and identifying number of the person filing Form 5471, the foreign corporation's name, its EIN if any, and a reference ID number.
For each shareholder whose acquisition is reported: name, address, identifying number, the date of the original 10% acquisition and the date of any additional 10% acquisition.
Section A covers each filing shareholder's latest U.S. income tax return and the date it last filed an information return under section 6046. Section B lists U.S. persons who are officers or directors, with their Social Security numbers.
Class of stock, date, method, and the number of shares held directly, indirectly and constructively, plus the amount paid or received and the other party's name and address.
Each transferor's name, address, identifying number and date of transfer, the assets transferred with fair market value and adjusted basis, and the assets, notes or securities the foreign corporation issued in return.
A statement about U.S. income tax returns filed in the last 3 years, the date of any reorganization in the last 4 years, and a chart when the corporation is part of a chain of ownership.
Enter the name of the person filing Form 5471 and the foreign corporation's details. The instructions say to use the reference ID number shown on Form 5471, page 1, item 1b(2).
Column (d) is the date the shareholder first acquired 10% or more, in value or voting power, of the outstanding stock. Column (e) is the date the shareholder acquired an additional 10% or more, in one or more transactions.
Give the type, date and service center of the shareholder's latest U.S. income tax return. If it was filed electronically, the instructions say to enter "e-filed" in column (b)(3) instead of a service center.
Use a separate line for each acquisition. Column (d) is the method, for example purchase, gift, bequest or trade. Columns (e)(2) and (e)(3) are shares held indirectly under section 958(a)(2) and constructively under section 958(b).
Completed by shareholders who dispose of their interest in whole or in part. In the instructions' example, a gift of 5,000 shares shows "gift" in column (d), "-0-" in column (f) and the recipient's name and address in column (g).
In item (b), list the most recent reorganization date in the last 4 years, but not a date already reported in Section E. In item (c), attach a chart showing the corporation's position in any chain of ownership.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to Form 5471." The Form 5471 instructions say Form 5471 is attached to the income tax return (or partnership or exempt organization return) and both are filed by the due date, including extensions, of that return.
The form says to complete a separate Schedule O for each foreign corporation for which information must be reported.
Unlike the rest of Form 5471, the instructions say Schedule O reports acquisitions, dispositions, and organizations or reorganizations that occurred during the filer's tax year.
The instructions list a $10,000 penalty for each failure for each reportable transaction. An additional $10,000 applies for each 30-day period the failure continues after 90 days from an IRS notice, limited to a maximum of $50,000. See section 6679.
The instructions say a person who agrees to have another person file Form 5471 and Schedule O for them may be subject to the penalties if the other person does not file a correct and proper form and schedule.
A corrected Form 5471 is filed with an amended tax return, with "Corrected" entered at the top and a statement identifying the changes.

5471
437 fields, 6 pages
5471 Sch. M
178 fields, 2 pages
5471 Sch. P
317 fields, 4 pages
8883
77 fields, 2 pages
8886
98 fields, 2 pages
8938
131 fields, 2 pages
The form says to complete a separate Schedule O for each foreign corporation for which information must be reported. The Form 5471 instructions define who completes each part.
No tool matches that search.
No. The form says "Attach to Form 5471." It is filed with Form 5471, which goes with the filer's income tax return.
The Form 5471 instructions say U.S. citizens or residents described in Category 2 complete Part I, and U.S. persons described in Category 3 complete Part II.
The instructions say it is met if a U.S. person owns 10% or more of the total value of the foreign corporation's stock, or 10% or more of the total combined voting power of all classes of stock with voting rights.
In the instructions' example, a U.S. citizen who held 10% gave 5,000 shares to his child, reduced his holding, and completed Form 5471 and Schedule O, reporting the gift in Section D.
The instructions say to report acquisitions, dispositions, and organizations or reorganizations that occurred during the filer's tax year, not the foreign corporation's year.
The instructions list $10,000 for each failure for each reportable transaction, plus $10,000 for each 30-day period after 90 days from an IRS notice, limited to a maximum of $50,000.