Part I: Filer's Identifying Information
Name and identifying number as shown on the return, a box for old target or new target, and whether a valid and timely Form 8023 was filed, with the date.
8883
Asset Allocation Statement Under Section 338
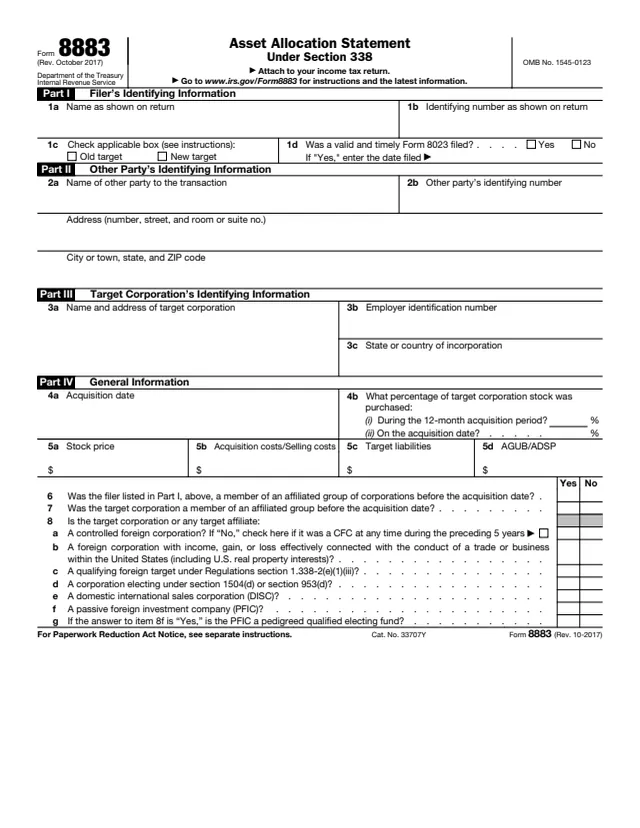
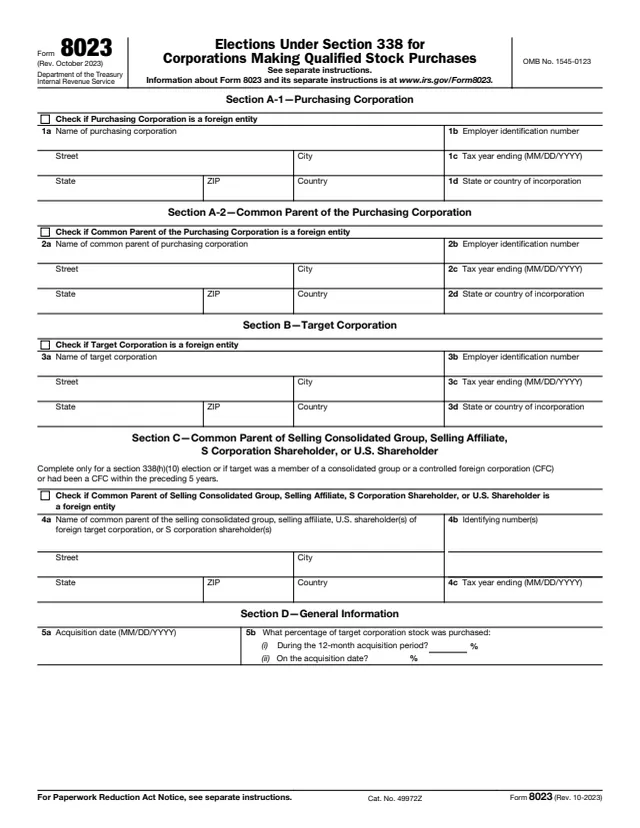
Form 8883 is the Asset Allocation Statement Under Section 338. The IRS says it is used to report information about transactions involving the deemed sale of corporate assets under section 338, including information previously reported on Form 8023, Elections Under Section 338 for Corporations Making Qualified Stock Purchases.
The instructions explain that when a section 338 election is made for a qualified purchase of stock of a target corporation, the old target is deemed to sell its assets to a new corporation, the new target, at the close of the acquisition date. Form 8023 makes the election, and Form 8883 supplies the information relevant to it. The instructions say that for both section 338(g) and section 338(h)(10) elections, the old target and the new target each file Form 8883 with an income tax return.
The form reports the stock price, costs, liabilities and the allocation of the deemed sale price across seven asset classes. You can fill out the PDF free in your browser on this page and download it without an account.
Name and identifying number as shown on the return, a box for old target or new target, and whether a valid and timely Form 8023 was filed, with the date.
Name, identifying number and address of the other party to the transaction.
Name and address, employer identification number and state or country of incorporation. The instructions say it is completed when Part I does not already identify the target.
Acquisition date, the percentage of stock purchased, stock price, acquisition or selling costs, target liabilities and AGUB or ADSP on lines 4a to 5d, then yes or no questions on lines 6 to 8g about affiliated groups and foreign status.
Line 9 lists Class I to Class V and Class VI and VII assets, each with its aggregate fair market value and its allocation of AGUB or ADSP, plus a total.
Lines 10 to 12 cover an increase or decrease in AGUB or ADSP after the original statement: the earlier return, the previous and redetermined allocations by class, and the reasons.
Enter the name as shown on the income tax return and the corporation's EIN. The instructions say an individual U.S. shareholder filing for a foreign target enters an SSN. Check old target or new target and answer the Form 8023 question.
Identify the taxpayer that files the return for the other side of the transaction, or the common parent of its consolidated group. For a CFC that files no U.S. return, the instructions point to the U.S. shareholder owning the largest interest.
Line 5a is the consideration paid for the recently purchased target stock. Line 5b is acquisition costs for the new target or selling costs for the old target. Line 5c is target liabilities. Line 5d is AGUB for the new target or ADSP for the old target.
The instructions say to use the residual method: reduce the consideration by Class I assets, allocate the rest to Classes II to VI in that order in proportion to fair market value, then to Class VII. Classes VI and VII are entered combined.
For each year AGUB or ADSP increases or decreases, complete Parts I to IV and VI on a new Form 8883. Enter on line 10 the tax year and return form number of the earlier filing, and give the reasons on line 12.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your income tax return. The instructions say to generally attach it to the return on which the effects of the section 338 deemed sale and purchase of the target's assets are reported.
The instructions say to file Form 8023 on time even if not all the information for Form 8883 is available yet.
Even when one Form 8023 covers several targets with the same acquisition date and affiliated group, the instructions say to file a separate Form 8883 for each target corporation.
The instructions say a filer that does not file a correct Form 8883 by the due date of the return and cannot show reasonable cause may be subject to penalties under sections 6721 through 6724.
The instructions say not to send Form 8883 to the Tax Forms and Publications Division address given for comments.
8023
58 fields, 3 pages

1120-S
390 fields, 5 pages

5471
437 fields, 6 pages

1120
481 fields, 6 pages
The instructions say that for elections under sections 338(g) and 338(h)(10), both the old target and the new target file Form 8883. It is attached to a return, not sent to a separate office.
No tool matches that search.
The instructions say Form 8023 is used to make an election under section 338, and Form 8883 is filed to supply information relevant to that election.
The instructions say that for elections under sections 338(g) and 338(h)(10), both the old target and the new target file Form 8883.
AGUB, the adjusted grossed-up basis, is the amount for which the new target is deemed to have purchased all of its assets. ADSP, the aggregate deemed sales price, is the amount for which the old target is deemed to have sold them.
The instructions define seven classes, from Class I, cash and general deposit accounts, to Class VII, goodwill and going concern value. Classes VI and VII are reported together on the form.
The instructions say any affected party completes Parts I to IV and VI of Form 8883 and attaches it to the return for the year the increase or decrease is taken into account.
The form says to attach it to your income tax return, and the instructions name the return for each case. For certain foreign targets a copy also goes with Form 5471.