Sections A-1 and A-2
Name, EIN, address, tax year ending and state or country of incorporation for the purchasing corporation and for its common parent, each with a box for a foreign entity.
8023
Elections Under Section 338 for Corporations Making Qualified Stock Purchases
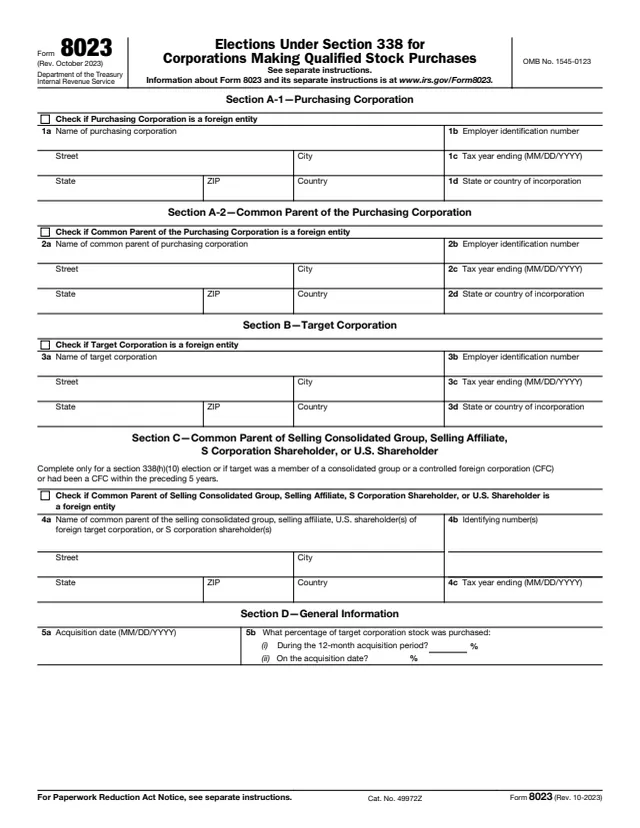
Form 8023 is the corporate form used to make elections under section 338 of the Internal Revenue Code. The IRS says purchasing corporations use it to make section 338 elections for the target corporation if they made a qualified stock purchase (QSP) of that target.
The instructions define a QSP as the purchase of at least 80% of the total voting power and value of a corporation's stock by another corporation during a 12-month acquisition period. The form covers a section 338(g) election, a section 338(h)(10) election and a gain recognition election.
The October 2023 revision adds 2D barcodes and a new page 3. The instructions also list an electronic fax option for this form. You can fill out Form 8023 free in your browser on this page and download it without an account.
Name, EIN, address, tax year ending and state or country of incorporation for the purchasing corporation and for its common parent, each with a box for a foreign entity.
The same identifying fields for the target corporation whose stock was purchased, plus a foreign entity box.
The common parent of the selling consolidated group, selling affiliate, S corporation shareholder or U.S. shareholder. The form says to complete it only for a section 338(h)(10) election or a consolidated group or CFC target.
Line 5a asks for the acquisition date. Line 5b asks what percentage of target stock was purchased during the 12-month acquisition period and on the acquisition date.
Line 6 is the section 338(h)(10) election, line 7 another section 338 election, line 8 a gain recognition election and line 9 a box for additional targets.
Separate signature areas for the purchasing corporation, the selling group or affiliate and S corporation shareholders. Page 3 holds the barcodes.
Complete Sections A-1, A-2 and B. The instructions say to include an EIN for each corporation unless it does not have, and is not otherwise required to have, one. Section A-2 is for a purchaser that is a member of a consolidated group.
For an S corporation target, the instructions ask for Section C information for each shareholder, with a schedule for the others. For a CFC target, enter the U.S. shareholder that owned the largest percentage by value.
On line 5a enter the acquisition date, which the instructions define as the first day on which a QSP has occurred. On line 5b enter the percentages purchased.
Check line 6 or line 7. Line 8 is available only if line 7 is checked. If a gain recognition election is actually made, the instructions list a schedule with a declaration that each holding corporation signs.
One form may cover several targets with the same acquisition date and the same affiliated group. Check line 9 and attach a schedule with Sections A-1 through E details for each extra target.
Each required party signs under the matching declaration. If multiple signatures are required, the instructions say to use a SIGNATURE ATTACHMENT and write See attached in the signature area.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 8023 by the 15th day of the 9th month after the acquisition date. Special rules may apply to foreign purchasing corporations.
The instructions list fax number 844-253-9765 (toll free) for Form 8023 and related attachments only. The fax may not exceed 100 pages.
The cover sheet lists Subject: Form 8023, the sender's name, title, phone number and street address, the date and the page count. The instructions say not to put an EIN or SSN on it.
Without electronic fax, the instructions say to mail it to Internal Revenue Service, OTSA Mail Stop 4916, 1973 Rulon White Blvd., Ogden, UT 84201.
The instructions say a section 338 election is not valid for a CFC, a passive foreign investment company or a foreign personal holding company target unless affected U.S. persons are notified in writing.
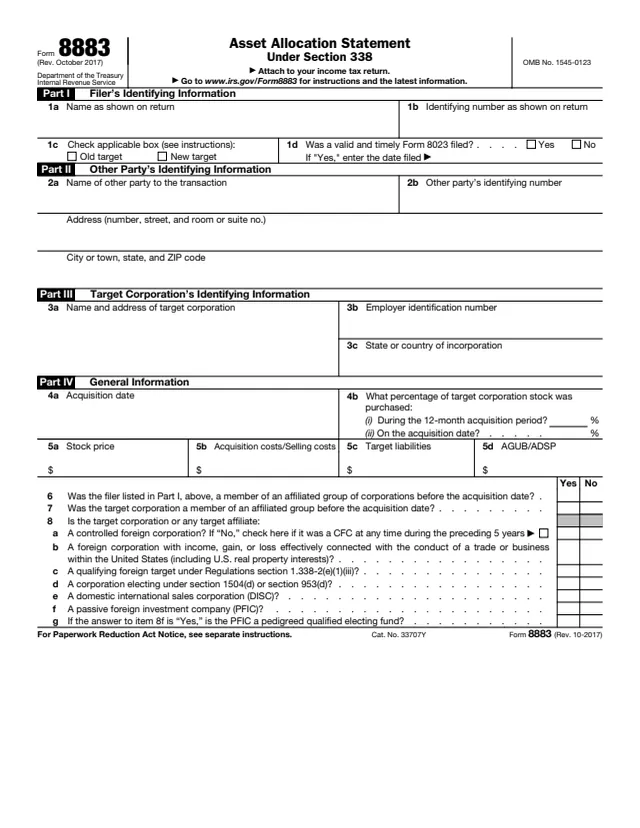
For foreign purchasers and foreign targets, the instructions say each U.S. shareholder also files Form 8883, Asset Allocation Statement Under Section 338, with Form 5471.
The instructions say a purchasing corporation generally files Form 8023 for the target. It is a corporate election, not a form for individual taxpayers.
No tool matches that search.
The instructions define it as the purchase of at least 80% of the total voting power and value of a corporation's stock by another corporation during a 12-month acquisition period. Preferred stock described in section 1504(a)(4) is not counted.
The purchasing corporation and the common parent of the selling consolidated group or the selling affiliate. For an S corporation target, the instructions say each shareholder signs, even one who does not sell stock in the QSP.
The instructions say by the 15th day of the 9th month after the acquisition date. Foreign purchasing corporations have special rules in Regulations section 1.338-2(e)(1).
Yes, when each target has the same acquisition date and was in the same affiliated group immediately before and after that date. Check line 9 and attach a schedule for the other targets.
The instructions list an electronic fax number, 844-253-9765, used only for Form 8023 and related attachments. Faxes may not exceed 100 pages.
No. Form 8023 makes the election. Form 8883 is the Asset Allocation Statement Under Section 338, which the IRS lists as a related form.