5471

Information Return of U.S. Persons With Respect To Certain Foreign Corporations

Agency
IRS
Revision
Rev. December 2025
Fillable fields
437
Pages
6
Official source
IRS form page
Checked
October 21, 2026
Fill 5471 online
Page 1 of form 5471

Form 5471: Information Return of U.S. Persons With Respect To Certain Foreign Corporations

Form 5471 is the Information Return of U.S. Persons With Respect To Certain Foreign Corporations. The instructions say it is used by certain U.S. persons who are officers, directors or shareholders in certain foreign corporations, and that the form and schedules satisfy the reporting requirements of sections 6038 and 6046 and the related regulations.

The filer checks one or more categories of filer, from 1a to 5c, and the instructions include a chart of which schedules each category completes. A separate Form 5471 and its applicable schedules are completed for each applicable foreign corporation. The form says all information must be in English and all amounts stated in U.S. dollars unless otherwise indicated.

You can fill it out free in your browser on this page and download the result without an account.

What's on Form 5471

Page 1 identifying information

The foreign corporation's annual accounting period, the filer's name, address and identifying number, and items B to H: category of filer, voting stock owned, final return, alternative information and persons the return is filed for.
Lines 1 and 2

The foreign corporation's name and address, EIN or reference ID number, country of incorporation, business activity, functional currency, U.S. branch or agent, statutory agent and custodian of books and records.

Schedules A and B

Schedule A lists each class of stock and the shares outstanding. Schedule B lists U.S. shareholders in Part I and direct shareholders in Part II.

Schedule C: Income Statement

Income, deductions, net income and other comprehensive income, reported in functional currency under U.S. GAAP and in U.S. dollars.

Schedules F and G

Schedule F is the balance sheet. Schedule G, Other Information, asks yes or no questions. The instructions say question 3b and line 21 of Schedule G are new in this revision.

Schedule I and separate schedules

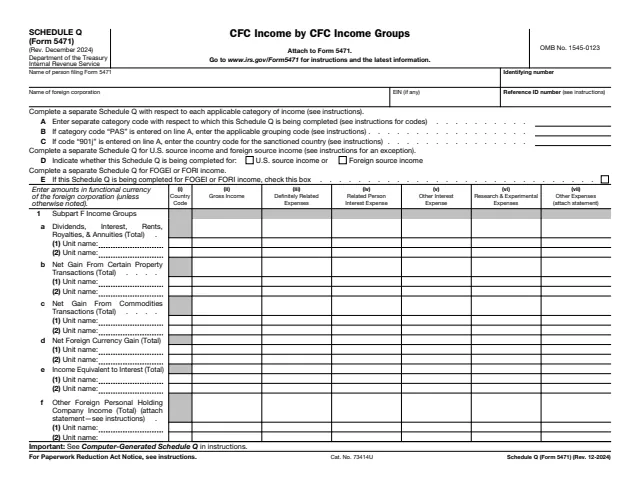
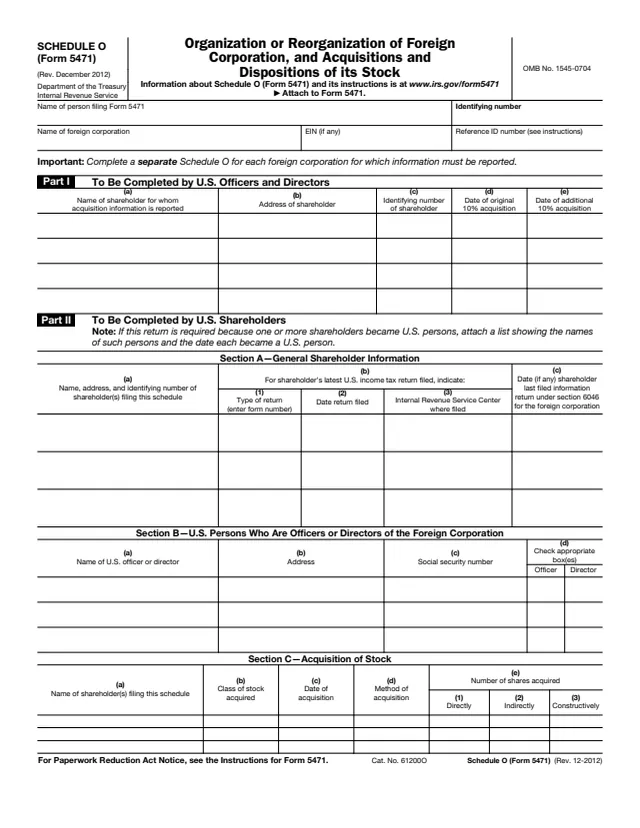
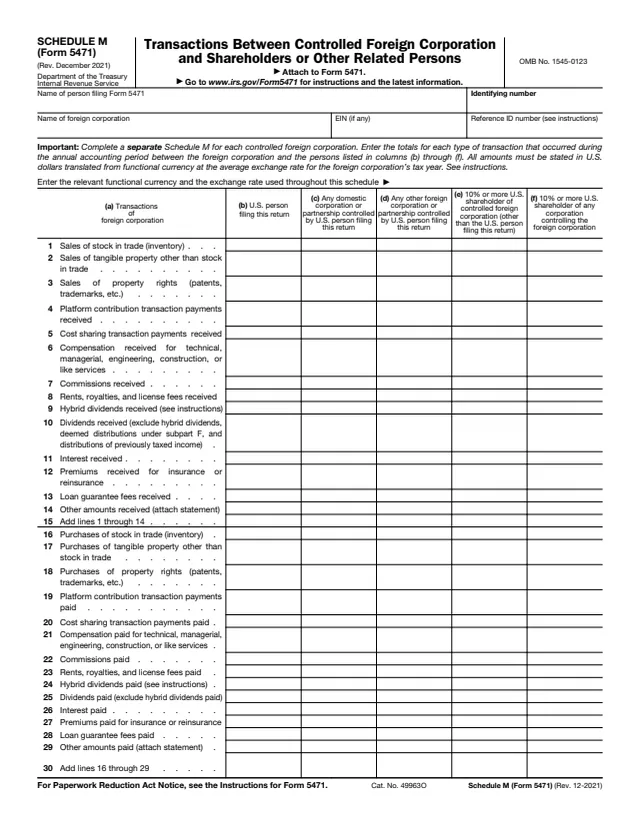
Schedule I summarizes the shareholder's income from the foreign corporation. Separate schedules, such as E, H, I-1, J, M, O, P, Q and R, are attached when the filing chart calls for them.

How to fill out Form 5471

  1. 1

    Accounting period and filer

    Enter the foreign corporation's annual accounting period below the title, then the filer's name and address. For a consolidated return, the instructions say to enter the U.S. parent's name and its EIN in item A.

  2. 2

    Item B: category of filer

    Check every category that applies. The instructions say a filer that meets both Category 4 and Category 5a checks only Category 4 and leaves 5a blank.

  3. 3

    Items C to H

    Enter the voting stock percentage owned at the end of the period. Check item D only for the foreign corporation's final year, and then complete Schedule O. Item G takes the alternative information code when item F is checked.

  4. 4

    Lines 1 and 2, Schedules A and B

    Describe the foreign corporation and its stock, then list the shareholders. The form says each class of stock in Schedule B should match the description entered in Schedule A, column (a).

  5. 5

    Schedules C, F, G and I

    Report Schedule C in functional currency under U.S. GAAP and translated to U.S. dollars. If the functional currency is the U.S. dollar, the form says to complete only the U.S. Dollars column.

  6. 6

    Additional sheets

    If a section needs more space, the instructions say to complete all entry spaces first and attach the rest on sheets that conform with the IRS version, rather than entering See attached.

The form says to fill in all applicable lines and schedules. The instructions say a required schedule with all zero amounts is still filed with one or more zero amounts.

Why fill Form 5471 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, deadlines and penalties

Attach to the return

The instructions say to attach Form 5471 to the filer's income tax return, or partnership or exempt organization return, and file both by the due date, including extensions, for that return.

One per foreign corporation

The instructions say to complete a separate Form 5471 and all applicable schedules for each applicable foreign corporation.

Section 6038(a) penalty

The instructions list a $10,000 penalty for each annual accounting period of each foreign corporation for failure to furnish the information required by section 6038(a) within the time prescribed.

Continued failure

If the information is not filed within 90 days after the IRS mails a notice, an additional $10,000 per foreign corporation applies for each 30-day period, limited to a maximum of $50,000 for each failure.

Section 6046 penalty

The instructions say failure to file or report all of the information requested by section 6046 is subject to a $10,000 penalty for each such failure for each reportable transaction.

Recent developments

The About page lists the implementation of new foreign tax allocation reporting in the Schedule E (Form 5471) instructions, dated SEP-14-2026.

Who files Form 5471?

  • Category 1: U.S. shareholders of a section 965 SFC

    A U.S. shareholder of a foreign corporation that was a section 965 specified foreign corporation during its tax year. The instructions describe types 1a, 1b and 1c.

  • Category 2: officers and directors

    A U.S. citizen or resident who is an officer or director of a foreign corporation in which a U.S. person acquired stock meeting the 10% stock ownership requirement, or an additional 10% or more.

  • Category 3: acquisitions and dispositions

    Among others, a U.S. person who acquires stock that meets the 10% stock ownership requirement, or who disposes of enough stock to fall below it.

  • Category 4: control

    A U.S. person who had control of a foreign corporation during the annual accounting period of the foreign corporation, as the instructions define control.

  • Category 5: U.S. shareholders of a CFC

    A U.S. shareholder who owned stock in a controlled foreign corporation (CFC) during its tax year and on the last day it was a CFC. The instructions describe types 5a, 5b and 5c.

  • Individuals and entities

    For Category 1, the instructions define a U.S. person as a citizen or resident, a domestic partnership, a domestic corporation, or an estate or trust that is not foreign.

The instructions say U.S. persons described in the categories of filers complete the schedules, statements and information the filing chart lists for their category, and attach the form to their own return.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 5471

Who files Form 5471?

The About page says certain U.S. citizens and residents who are officers, directors or shareholders in certain foreign corporations file it. The instructions describe five categories of filers.

Is Form 5471 filed on its own?

The instructions say to attach it to the filer's income tax return, or partnership or exempt organization return, and file both by the due date, including extensions.

Does one form cover several foreign corporations?

No. The instructions say to complete a separate Form 5471 and all applicable schedules for each applicable foreign corporation.

What if a required schedule has all zero amounts?

The instructions say the schedule should still be filed with one or more zero amounts.

What currency are amounts reported in?

The form says amounts are stated in U.S. dollars unless otherwise indicated. Schedule C is reported in functional currency and also translated to U.S. dollars.

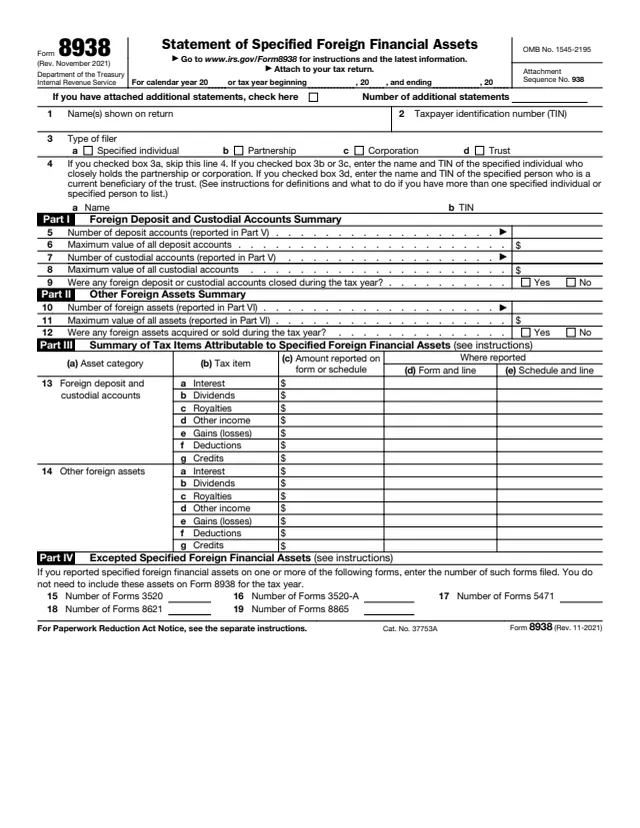
Do assets on Form 5471 also go on Form 8938?

The instructions say items reported on Form 5471 are not required on Form 8938. When item E is checked, only Form 8938, Part IV, line 17 is completed.

What is the penalty for not filing?

The instructions list a $10,000 penalty for each annual accounting period of each foreign corporation under section 6038(a), and a 10% reduction of the foreign taxes available for credit.