8858

Information Return of U.S. Persons With Respect To Foreign Disregarded Entities (FDEs) and Foreign Branches (FBs)

Agency
IRS
Revision
Rev. December 2024
Fillable fields
190
Pages
4
Official source
IRS form page
Checked
October 21, 2026
Fill 8858 online
Page 1 of form 8858

Form 8858: Information Return of U.S. Persons With Respect to FDEs and FBs

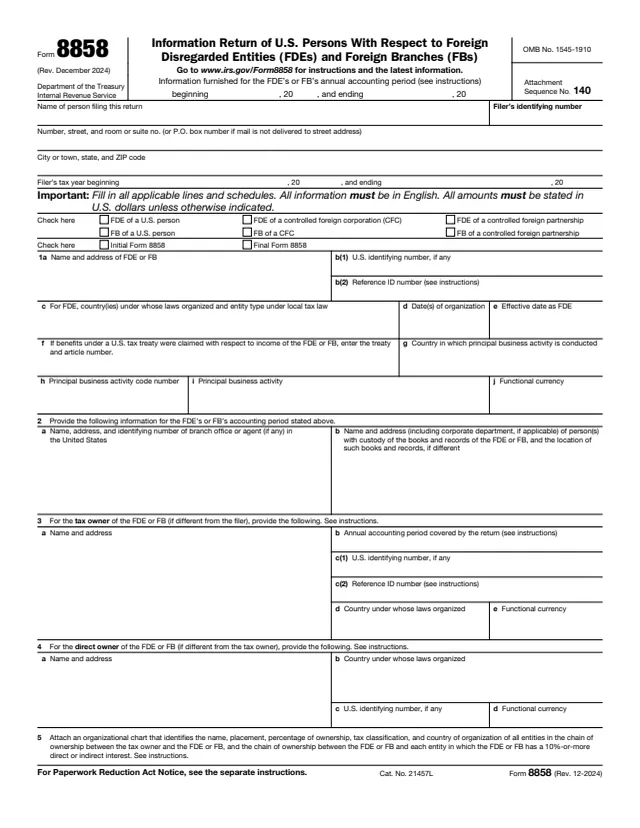
Form 8858 is the Information Return of U.S. Persons With Respect to Foreign Disregarded Entities (FDEs) and Foreign Branches (FBs). The IRS says certain U.S. persons that own an FDE or FB directly or, in certain circumstances, indirectly or constructively use the form and its schedules to satisfy the reporting requirements of sections 6011, 6012, 6031, and 6038.

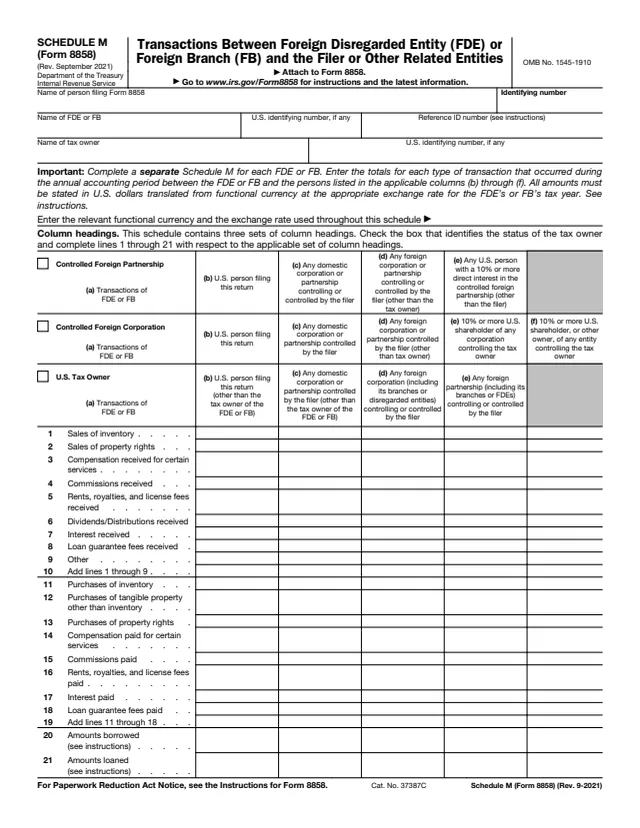
Page 1 identifies the filer, the FDE or FB, its tax owner and its direct owner, and calls for an organizational chart. The schedules that follow cover an income statement, section 987 gain or loss, a balance sheet, other information, current earnings and profits, a transferred loss amount and foreign income taxes. The instructions say to complete a separate Form 8858 and all applicable schedules for each FDE or FB. The separate Schedule M (Form 8858) reports transactions with the filer and related entities.

You can fill out Form 8858 free in your browser on this page and download the result without an account.

What's on Form 8858

Page 1: identifying information

The filer's name, address and tax year, boxes for the type of FDE or FB and for an initial or final Form 8858, then lines 1 to 4 for the FDE or FB, any U.S. branch office or agent, the books and records, the tax owner and the direct owner. Line 5 asks for an organizational chart.

Schedules C and C-1

Schedule C is an income statement in functional currency and U.S. dollars. Schedule C-1 covers remittances and section 987 gain or loss.

Schedule F: balance sheet

Assets, liabilities and owner's equity at the beginning and end of the annual accounting period, in U.S. dollars.

Schedule G: other information

Yes or No questions on trusts, foreign partnerships, section 901(m) and 909 taxes, base erosion payments, dual consolidated losses and Top-up Tax.

Schedule H: earnings and profits

Current earnings and profits or taxable income in functional currency, translated to U.S. dollars, with the exchange rate used.

Schedules I and J

Schedule I covers a transferred loss amount when FB assets are transferred to a foreign corporation. Schedule J lists foreign income taxes paid or accrued by country and foreign tax credit category.

How to fill out Form 8858

  1. 1

    Header and checkboxes

    Enter the FDE's or FB's annual accounting period and the filer's name, identifying number and address. The instructions say a U.S. corporation in a consolidated group lists the common parent. Check the box for the type of FDE or FB, and the initial or final box only in the year the FDE or FB was formed, acquired, terminated or disposed of.

  2. 2

    Line 1

    Enter the FDE's or FB's name and address, an EIN on line 1b(1) or a reference ID number on line 1b(2), and its country, dates, any treaty claim, principal business activity code and functional currency. The instructions say a reference ID number is alphanumeric, up to 50 characters, with no special characters or spaces.

  3. 3

    Lines 2 to 5

    Give any U.S. branch office or agent and where the books and records are kept. Lines 3 and 4 cover the tax owner and direct owner when they differ from the filer. Line 5 is the organizational chart of the chain of ownership.

  4. 4

    Schedules C, C-1 and F

    Report the income statement in functional currency under U.S. GAAP with U.S. dollar amounts, the section 987 lines, and the balance sheet in U.S. dollars.

  5. 5

    Schedules G, H, I and J

    Answer the Schedule G questions that apply, figure current earnings and profits on Schedule H, complete Schedule I if it applies, and list foreign taxes on Schedule J.

  6. 6

    Exchange rates

    The instructions say exchange rates are reported as the units of foreign currency that equal 1 U.S. dollar, rounded to at least four places.

Why fill Form 8858 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

When and where to file, and penalties

When it is due

The instructions say Form 8858 is due when the filer's income tax return or information return is due, including extensions.

Where it goes

A tax owner of the FDE or an operator of an FB attaches Form 8858, and Schedule M if required, to its income tax return or information return. Other filers attach it to the Form 5471 or Form 8865 filed for the CFC or CFP that is the tax owner.

Electronic filing

The instructions say Form 8858 is attached electronically to an e-filed Form 1120 or 1065. With an e-filed Form 1040, 1040-SR or 1041, it is attached to the applicable Form 8453.

Penalties

The instructions list a $10,000 penalty for each annual accounting period of each CFC or CFP for failing to furnish the information on time, additional penalties after an IRS notice up to a maximum of $50,000 for each failure, and a 10% reduction of foreign taxes available for credit.

Dormant FDEs

Announcement 2004-4 provides a summary filing procedure. The summary return completes only the identifying information before Schedule C and is labeled "Filed Pursuant to Announcement 2004-4 for Dormant FDE."

Who files Form 8858?

  • Direct tax owners and operators (category 1)

    A U.S. person that is directly a tax owner of an FDE or operates an FB at any time during its tax year or annual accounting period. The instructions say this filer completes the entire form and Schedule M (Form 8858).

  • Owners through tiers (category 2)

    A U.S. person that, through one or more tiers of FDEs, is a tax owner of an FDE or operates an FB. This filer also completes the entire form and Schedule M (Form 8858).

  • Form 5471 filers (category 3)

    Certain U.S. persons who file Form 5471 for a CFC that is a tax owner of an FDE or operates an FB. Category 4 filers of Form 5471 complete the entire form; category 5 filers of Form 5471 complete page 1 and Schedules G, H and J.

  • Form 8865 filers (category 4)

    Certain U.S. persons who file Form 8865 for a controlled foreign partnership (CFP) that is a tax owner of an FDE or operates an FB. Category 2 filers of Form 8865 complete page 1, Schedules G, H and J and Schedule M.

  • Partners in a partnership (categories 5 and 6)

    A U.S. partner that recognizes section 987 gain or loss for the partnership's FDE or FB completes page 1 and Schedule C-1. A U.S. corporation partner (other than a RIC, a REIT, or an S corporation) in a partnership that checked box 11 on Schedules K-2 and K-3 (Form 1065) completes lines 1 through 5 and parts of Schedule G.

The instructions list six categories of U.S. persons that are tax owners of FDEs, operate an FB, or own certain interests in tax owners of FDEs or FBs. How much of the form each completes depends on the category.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 8858

What is a foreign disregarded entity (FDE)?

The instructions define it as an entity that is not created or organized in the United States and that is disregarded as an entity separate from its owner for U.S. income tax purposes under Regulations sections 301.7701-2 and 301.7701-3.

Is Form 8858 filed on its own?

No. The instructions say it is attached to the filer's income tax return or information return, or to the Form 5471 or Form 8865 filed for the CFC or CFP that is the tax owner.

Is a separate form needed for each entity?

Yes. The instructions say to complete a separate Form 8858 and all applicable schedules for each FDE or FB, including lower tiers.

What if the FDE or FB has no EIN?

The instructions say a reference ID number goes on line 1b(2) when no EIN is entered on line 1b(1). An FB does not file Form 8832 and may not have an EIN.

Does a reference ID number come from the IRS?

No. The instructions say the filer establishes it, with no need to apply to the IRS, and uses it consistently from year to year for the same FDE or FB.

What are the penalties for not filing?

The instructions list a $10,000 penalty for each annual accounting period of each CFC or CFP, additional penalties after an IRS notice up to $50,000 for each failure, a reduction of foreign tax credits, and possible criminal penalties.