8865

Return of U.S. Persons With Respect to Certain Foreign Partnerships

Agency
IRS
Revision
2025
Fillable fields
461
Pages
6
Official source
IRS form page
Checked
October 21, 2026
Fill 8865 online
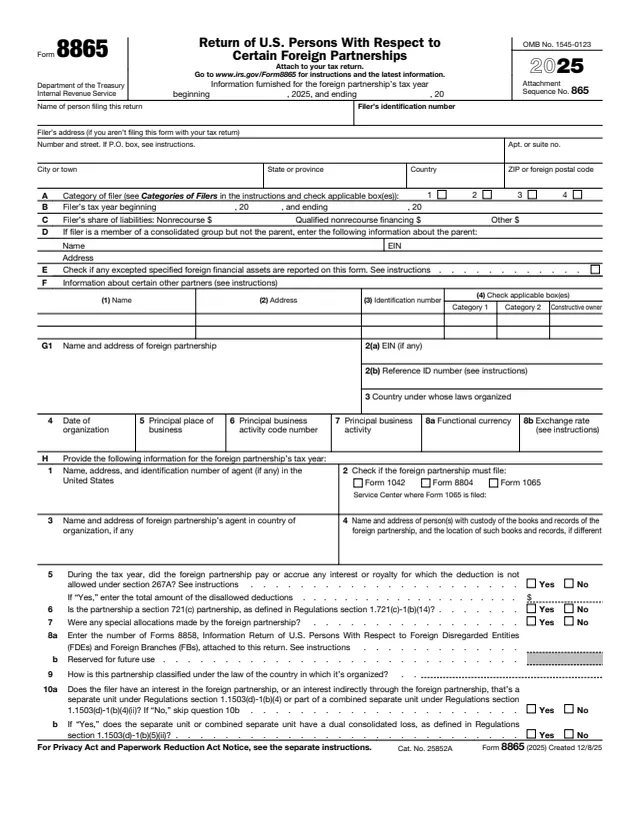
Page 1 of form 8865

Form 8865: Return of U.S. Persons With Respect to Certain Foreign Partnerships

Form 8865, Return of U.S. Persons With Respect to Certain Foreign Partnerships, is how a U.S. person reports the information required under section 6038 (controlled foreign partnerships), section 6038B (transfers to foreign partnerships) and section 6046A (acquisitions, dispositions and changes in foreign partnership interests).

The instructions sort filers into four categories, and each category completes a different set of pages and schedules. A separate Form 8865 is completed for each foreign partnership. The form is attached to the filer's income tax return, or to a partnership or exempt organization return, and filed by that return's due date, including extensions.

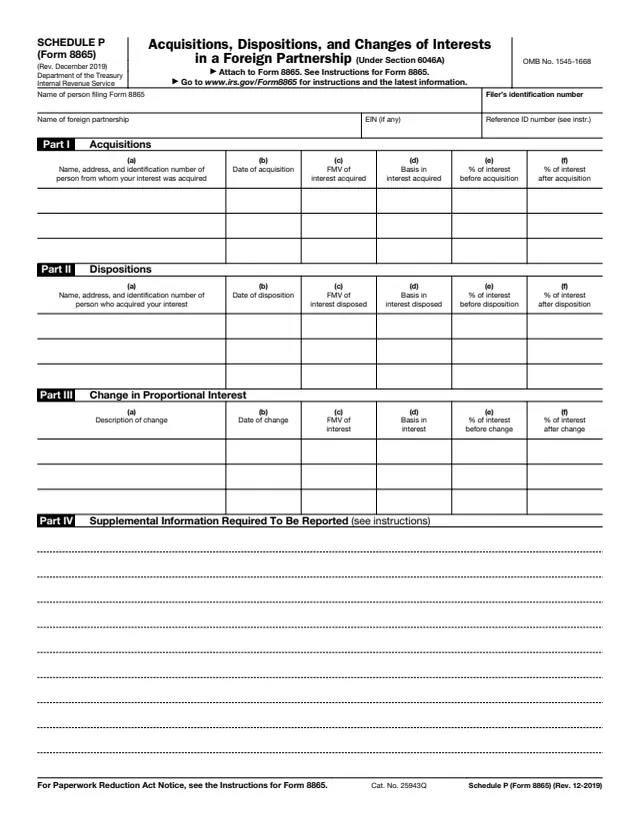
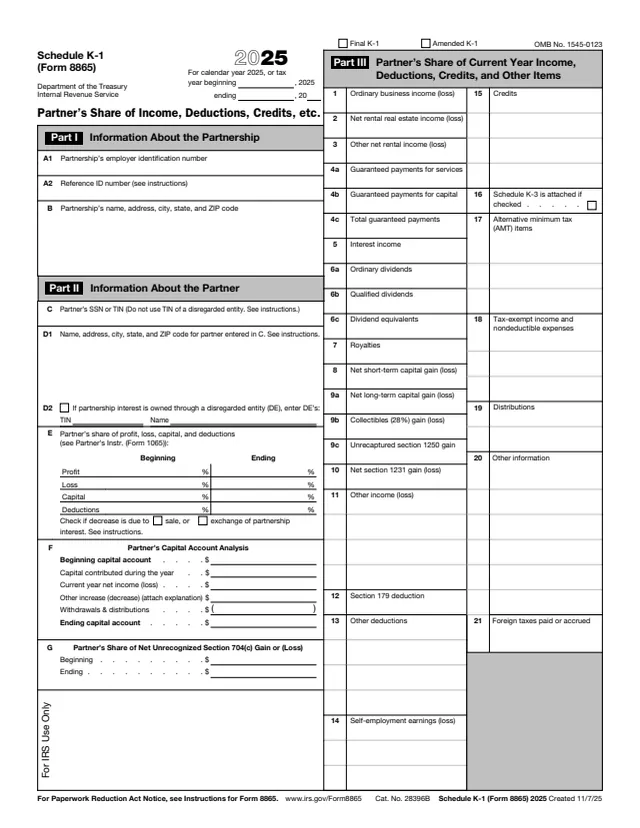
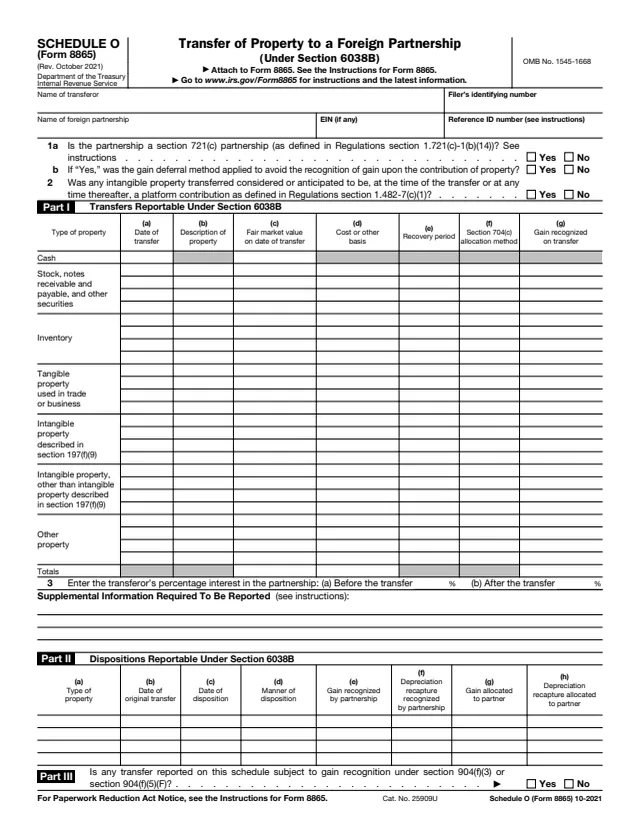
The 2025 form runs six pages, from identifying information and questions about the partnership to Schedules A through N. Schedules K-1, O and P (Form 8865) are separate PDFs. You can fill out the PDF free in your browser on this page and download it without an account.

What's on Form 8865

Page 1: filer and partnership

Filer name, identification number and address; items A to F on category, tax year, liabilities, consolidated parent, excepted assets and other partners; item G on the foreign partnership; item H on agents, records and other questions.
Page 2: questions, signature and Schedule A

Items H11 to H14, a signature area used only when the form is filed separately, and Schedules A, A-1, A-2 and A-3 on ownership, certain partners, foreign partners of a section 721(c) partnership and affiliations.

Schedule B

Income statement for trade or business income and expenses, lines 1a through 22.

Schedule K

Partners' distributive share items. The instructions say only Category 1 filers complete it.

Schedules L, M, M-1 and M-2

Balance sheets per books, balance sheets for interest allocation, a reconciliation of income, and partners' capital accounts. A Yes on item H11 (receipts under $250,000 and assets under $1 million) skips L, M-1 and M-2.

Schedule N

Transactions between the controlled foreign partnership and partners or other related entities, such as sales of inventory, royalties, distributions, interest and loan balances.

How to fill out Form 8865

  1. 1

    Tax year and filer

    Enter the foreign partnership's tax year that ended with or within the filer's tax year, then the filer's identifying number (an EIN for entities, an SSN or other number for individuals) and address.

  2. 2

    Item A: category

    Check the box for each category that describes the filer. The Filing Requirements for Categories of Filers chart in the instructions lists the schedules for each category.

  3. 3

    Item G: the partnership

    Enter the foreign partnership's name and address and its EIN, if any, or a reference ID number. The instructions say a reference ID is alphanumeric, up to 50 characters, and used consistently from year to year.

  4. 4

    Item G8: currency

    Enter the functional currency and the exchange rate. The instructions say the rate is reported as units of foreign currency that equal one U.S. dollar, rounded to at least four places.

  5. 5

    Schedules

    Complete the schedules for the category. For Schedules B, K, K-1, L, M-1 and M-2, the instructions point to the corresponding Form 1065 instructions. All amounts are in U.S. dollars and all information in English.

  6. 6

    Signature

    The instructions say to sign only if Form 8865 is filed separately because no U.S. income tax return is required. When it is attached to a return, the form and paid preparer area are left unsigned.

Why fill Form 8865 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, penalties and corrections

When and where

Attach Form 8865 to the income tax return (or partnership or exempt organization return) and file both by its due date, including extensions. A filer with no return files it separately at the time and place a return would be filed.

One form per partnership

The instructions say to complete a separate Form 8865 and the applicable schedules for each foreign partnership.

Category 1 and 2 penalty

The instructions list a $10,000 penalty for each tax year of each foreign partnership, and $10,000 more for each 30-day period after 90 days from an IRS notice, up to a maximum of $50,000 for each failure.

Category 3 penalty

The instructions list 10% of the fair market value of the property at the time of the contribution, subject to a $100,000 limit unless the failure is due to intentional disregard.

Category 4 penalty

The instructions list a $10,000 penalty, and $10,000 more for each 30-day period after 90 days from an IRS notice, not to exceed $50,000.

Corrections

File a corrected Form 8865 with an amended return, enter "corrected" at the top of the form, and attach a statement identifying and explaining the changes.

Who fills out Form 8865?

  • Category 1: control

    A U.S. person who controlled the foreign partnership at any time during its tax year, meaning ownership of more than a 50% interest. It also includes certain U.S. transferors to a section 721(c) partnership.

  • Category 2: 10% owners

    A U.S. person who owned a 10% or greater interest while the partnership was controlled by U.S. persons each owning at least 10%, unless the partnership had a Category 1 filer that year.

  • Category 3: contributors of property

    A U.S. person who contributed property for a partnership interest and owned at least a 10% interest right after, or whose contributions over the 12-month period exceeded $100,000.

  • Category 4: reportable events

    A U.S. person that had a reportable event under section 6046A during its tax year: an acquisition, a disposition or a change in proportional interest.

  • Exceptions

    The instructions describe exceptions for multiple Category 1 filers, certain constructive owners, members of a consolidated group, certain Category 4 filers, and trusts for state and local government employee retirement plans.

The instructions say a U.S. person qualifying under one or more of the categories of filers completes and files Form 8865. A U.S. person is a citizen or resident of the United States, a domestic partnership, a domestic corporation, and any estate or trust that isn't foreign.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 8865

Who files Form 8865?

The instructions say a U.S. person qualifying under one or more of the four categories of filers completes and files it.

Is Form 8865 filed on its own?

It is attached to the filer's income tax return. The instructions say a person without a return files it separately at the time and place a return would be filed.

What if more than one category applies?

The instructions say all items required for each category are submitted. A Category 2 and 3 filer submits the Category 2 schedules plus Schedules A-1 and O.

Can Form 1065 schedules replace Form 8865 schedules?

If the foreign partnership files Form 1065, the instructions say Category 1 and 2 filers may use a copy of the completed Form 1065 schedules in place of the equivalent Form 8865 schedules.

Which separate schedules go with Form 8865?

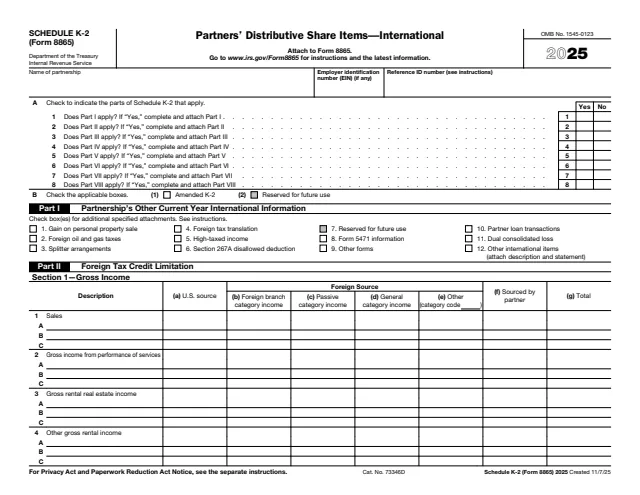
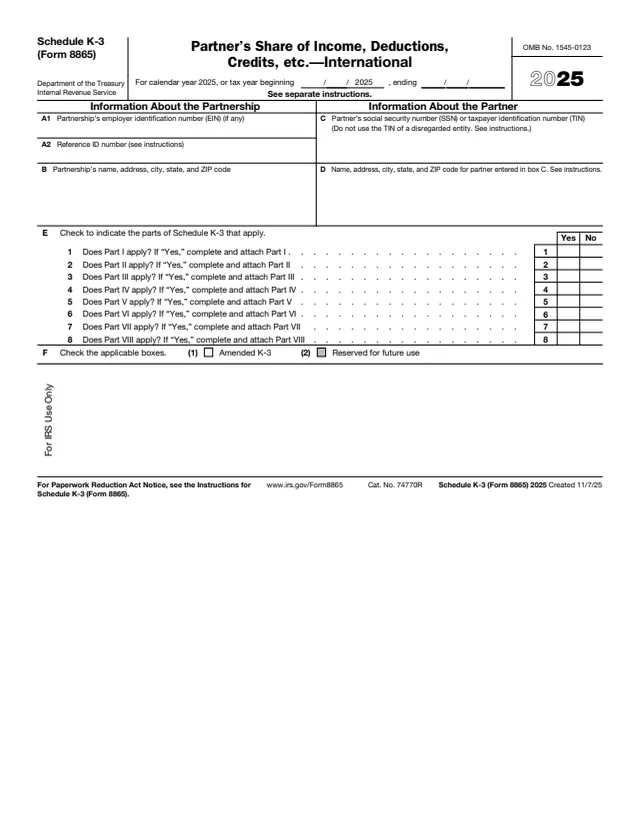
The About page lists Schedule K-1, Schedule O and Schedule P (Form 8865). The instructions also cover Schedules G, H, K-2 and K-3 (Form 8865).

What is a reference ID number?

A number the filer assigns to a foreign partnership to track it from year to year. It is required only when no EIN is entered, and the instructions say there is no need to apply to the IRS for one.