Header
Name of person filing Form 8865, filer's identification number, name of the foreign partnership, its EIN (if any) and the reference ID number.
8865 Sch. P
Acquisitions, Dispositions, and Changes of Interests in a Foreign Partnership (under section 6046A)
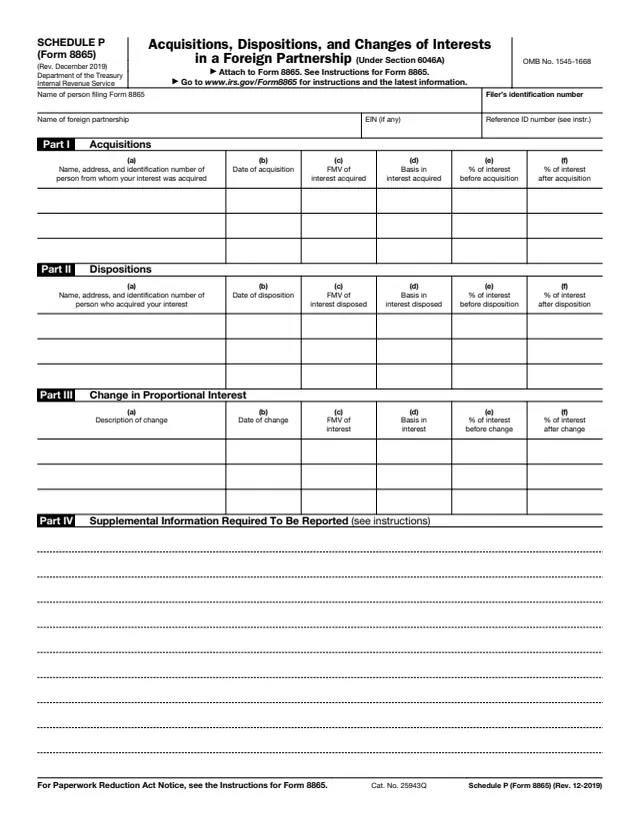
Schedule P (Form 8865) reports acquisitions, dispositions and changes of interests in a foreign partnership under section 6046A. It is a schedule of Form 8865, Return of U.S. Persons With Respect to Certain Foreign Partnerships, and the schedule says to attach it to Form 8865.
The Instructions for Form 8865 say every Category 4 filer completes Schedule P, unless they qualify under the exception for certain Category 4 filers. A Category 4 filer is a U.S. person that had a reportable event under section 6046A during that person's tax year: an acquisition, a disposition or a change in proportional interest. The instructions measure these events against a 10% direct interest in the partnership.
The schedule has four parts: acquisitions, dispositions, changes in proportional interest, and supplemental information. You can fill out Schedule P free in your browser on this page and download it without an account.
Name of person filing Form 8865, filer's identification number, name of the foreign partnership, its EIN (if any) and the reference ID number.
Columns (a) to (f): the person the interest was acquired from, date of acquisition, FMV and basis of the interest acquired, and percentage interest before and after.
The same six columns for the person who acquired the interest, date of disposition, FMV and basis of the interest disposed of, and percentages before and after.
Description of the change, date of change, FMV and basis of the interest, and percentage interest before and after the change.
Space for detail asked for in Parts I, II or III, with the part number and column identified next to each entry.
Enter the filer's name and identifying number, and the foreign partnership's name and EIN if any. The instructions say to use the reference ID number shown on Form 8865, item G2(b).
For each acquisition, enter the name, address and identifying number (if any) of the person the interest came from, the date, the FMV and basis as of that date, and the direct percentage interest before and immediately after.
For each disposition, enter the person the interest went to (unless it was a withdrawal from the partnership), the date, the FMV, the adjusted basis immediately before, and percentages before and after.
Briefly describe the event that changed the interest, such as the admission of a new partner, then enter the date, the FMV and basis immediately before the change, and percentages before and after.
If an acquisition, disposition or change took place over several dates, the instructions say to enter the date it was completed.
Where the percentage differs among capital, profits, losses or deductions, enter "See Below" in columns (e) and (f) and state the percentages here. State any recognized gain or loss on a disposition here too.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 8865. The instructions say Form 8865 is attached to the income tax return (or partnership or exempt organization return) and filed by its due date, including extensions.
If no income tax return is required, the instructions say Form 8865 is filed separately with the IRS at the time and place an income tax return would be filed.
For failing to report section 6046A information, the instructions list a $10,000 penalty, plus $10,000 for each 30-day period the failure continues after 90 days from an IRS notice, up to $50,000, unless due to reasonable cause.
The instructions say an acquisition or disposition of a section 721(c) partnership interest can also call for Schedule H, and in some cases Schedule G.
Schedule P has no separate instructions. Its line instructions are part of the Instructions for Form 8865, which also hold the Paperwork Reduction Act Notice.
8865
461 fields, 6 pages
8865 Sch. O
233 fields, 1 page
8865
108 fields, 1 page
8865 Sch. G
203 fields, 2 pages
8865 Sch. H
82 fields, 1 page
8858
190 fields, 4 pages
The Instructions for Form 8865 say every Category 4 filer must complete Schedule P, unless the exception for certain Category 4 filers applies. The schedule goes to the IRS attached to the filer's Form 8865.
No tool matches that search.
No. The schedule says to attach it to Form 8865, and the Instructions for Form 8865 cover it.
The instructions define it as a U.S. person that had a reportable event under section 6046A during that person's tax year: an acquisition, a disposition or a change in proportional interest.
The instructions say to use the reference ID number shown on Form 8865, item G2(b). It is a number the filer assigns to identify the foreign partnership from year to year.
The instructions say to enter "See Below" in columns (e) and (f) and state the different percentages in Part IV.
The instructions say to enter the date the acquisition, disposition or change was completed.