Header and lines 1a to 2
Name and identifying number of the transferor, the foreign partnership's name, EIN and reference ID number, and yes or no questions on section 721(c) partnerships, the gain deferral method and platform contributions.
8865 Sch. O
Transfer of Property to a Foreign Partnership (under section 6038B)
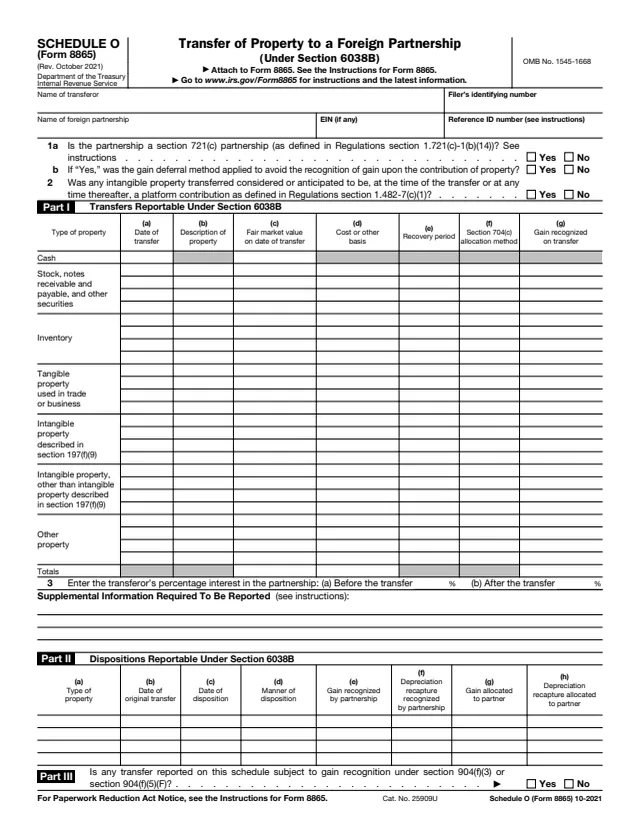
Schedule O (Form 8865) reports a transfer of property to a foreign partnership under section 6038B. It is not a stand-alone return: the schedule says "Attach to Form 8865" and points to the Instructions for Form 8865.
Form 8865 is the return a U.S. person files to report information on certain foreign partnerships. The instructions sort filers into four categories and say Category 3 filers complete Schedule O. A Category 3 filer is a U.S. person who contributed property to a foreign partnership in exchange for an interest in it, if that person owned at least a 10% interest right after the contribution, or the property contributed during the 12-month period ending on the date of transfer was worth more than $100,000.
The schedule lists each kind of property transferred, its value, basis and any gain recognized, the transferor's percentage interest before and after, and any later disposition of that property by the partnership. You can fill out the PDF free in your browser on this page and download it without an account.
Name and identifying number of the transferor, the foreign partnership's name, EIN and reference ID number, and yes or no questions on section 721(c) partnerships, the gain deferral method and platform contributions.
Rows for cash, securities, inventory, tangible property, two kinds of intangible property and other property, with columns (a) to (g) for date, description, fair market value, basis, recovery period, section 704(c) method and gain.
The transferor's percentage interest in the partnership before and after the transfer, and a blank area for the supplemental information the instructions require.
Columns (a) to (h) for the property type, original transfer date, disposition date, manner of disposition, gain and depreciation recapture recognized by the partnership and the amounts allocated to the partner.
One yes or no question: is any transfer reported on the schedule subject to gain recognition under section 904(f)(3) or section 904(f)(5)(F)?
Enter the transferor's name and identifying number and the foreign partnership's name and EIN, if any. The instructions say to use the reference ID number shown on Form 8865, item G2(b).
Report each contribution of property. The instructions say appreciated or intangible property is listed item by item, other property is grouped by the categories in Part I, and column (a) takes the date the transfer was completed if it took several dates.
Enter the method the partnership uses for section 704(c) allocations: traditional, traditional with curative allocations, or remedial. The instructions say the remedial method generally applies if the gain deferral method is used.
Enter capital interests by percentage right before and after the transfer. In the supplemental area, give a general description of each item, any differing profit, loss or deduction interests, and a short description of the wider transaction if there was one.
Report a disposition by the partnership of appreciated property the transferor reported earlier, while still a direct or constructive partner. For substituted basis property, the instructions say to enter "See Attached" and attach a statement.
Check yes or no. If gain recognition was required under section 904(f)(3) or (f)(5)(F) for a transfer in Part I, the instructions say to attach a statement naming the transfer and the gain recognized.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Schedule O is attached to Form 8865. The instructions say Form 8865 is attached to the income tax return (or partnership or exempt organization return) and both are filed by its due date, including extensions.
The instructions say a filer who has no income tax return to file sends Form 8865 separately, at the time and place an income tax return would be filed.
The instructions say a Category 3 filer reports on Schedule O the transactions that occurred during the filer's own tax year, not the partnership's tax year.
The instructions list extra filings when the gain deferral method applies: Schedule G (Form 8865), Schedule H (Form 8865) if certain events occur, Form 8838-P, and a copy of any Statement of Waiver of Treaty Benefits.
The instructions state a penalty equal to 10% of the fair market value of the property at the time of the contribution, limited to $100,000 unless the failure is due to intentional disregard, plus gain recognized as if the property had been sold.
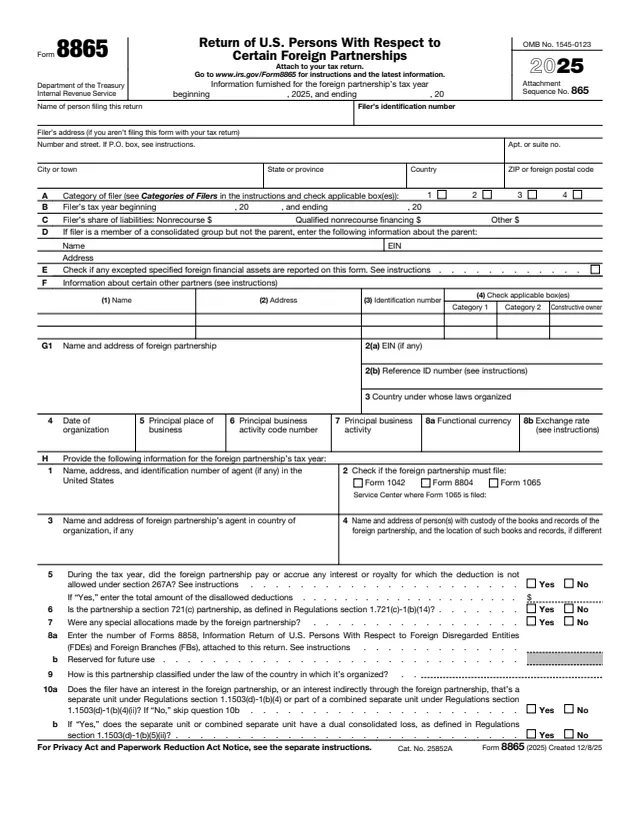
8865
461 fields, 6 pages
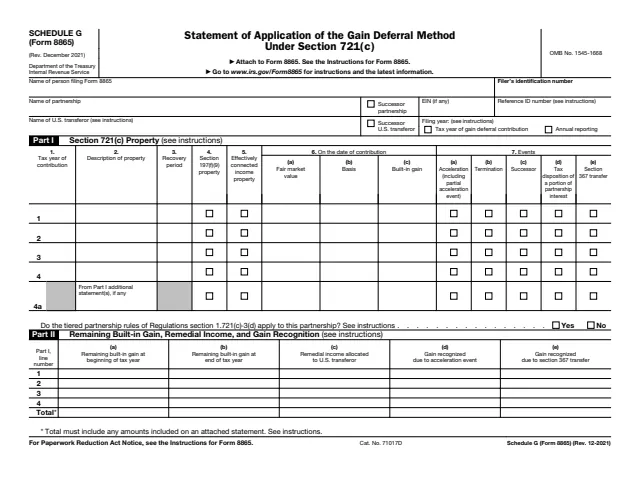
8865 Sch. G
203 fields, 2 pages
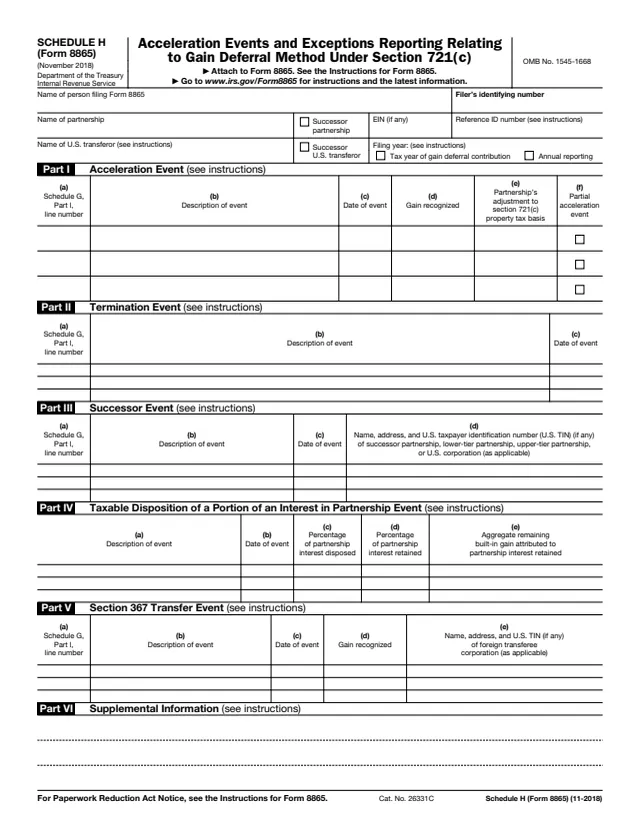
8865 Sch. H
82 fields, 1 page
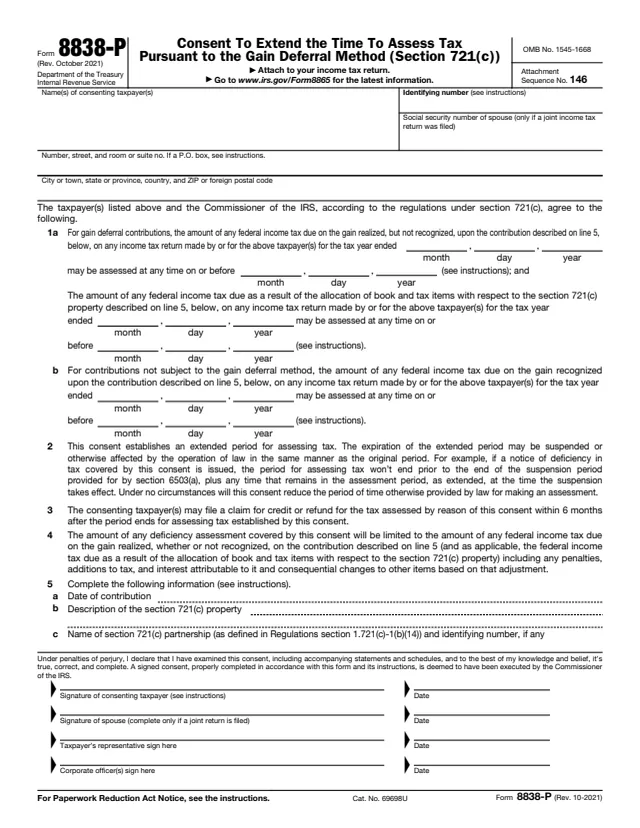
8838-P
27 fields, 3 pages
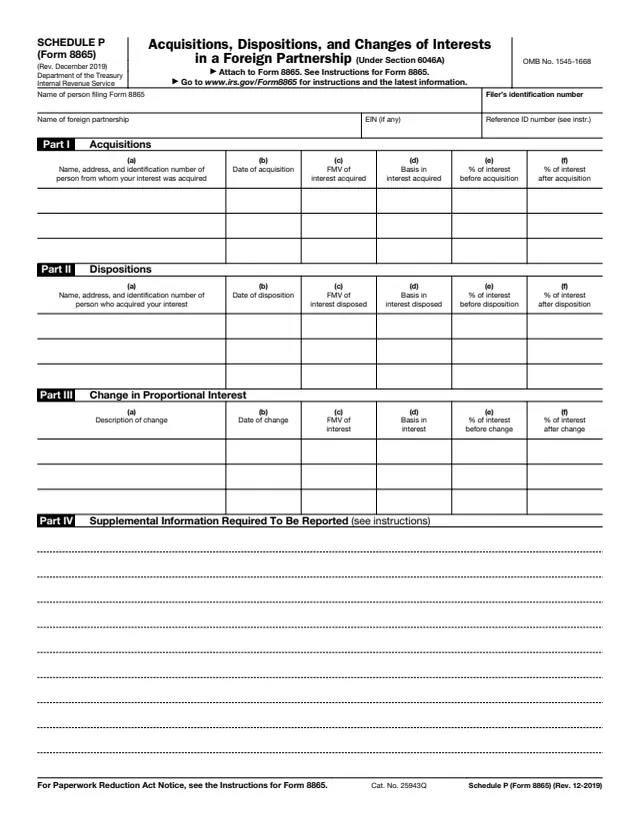
8865 Sch. P
69 fields, 1 page
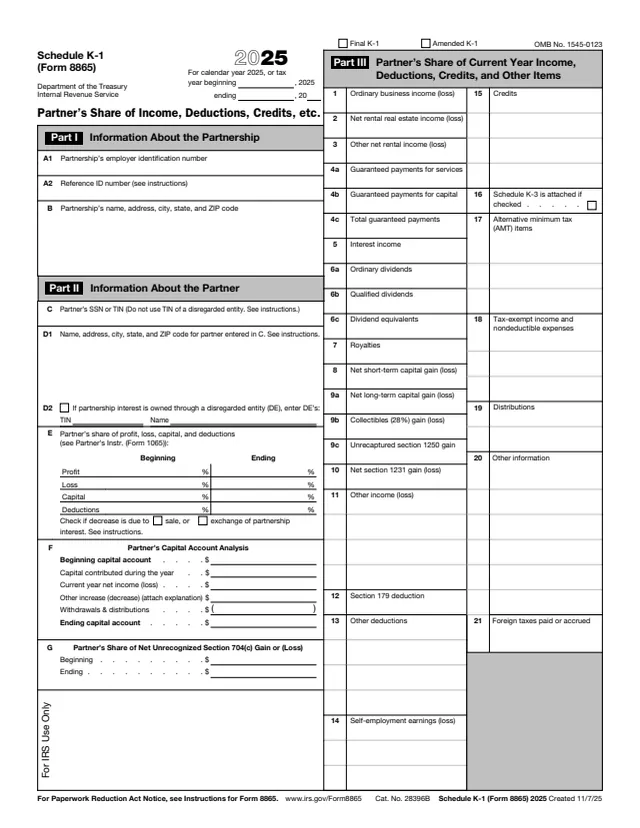
8865
108 fields, 1 page
The instructions say Category 3 filers complete Schedule O. A U.S. person, as the instructions define it, is a citizen or resident of the United States, a domestic partnership, a domestic corporation, or an estate or trust that is not foreign.
No tool matches that search.
No. The schedule says "Attach to Form 8865." It goes in with Form 8865, which is attached to the filer's income tax return.
The instructions say Category 3 filers complete Schedule O. That covers U.S. persons who contributed property to a foreign partnership and met the 10% interest or more than $100,000 test, and certain earlier transferors.
The instructions say to use the reference ID number shown on Form 8865, item G2(b). It is the number the filer assigns to the foreign partnership, mainly when the partnership has no EIN.
The instructions say appreciated property and intangible property are reported item by item, with limited exceptions, and all other property is grouped by the categories listed in Part I.
Part II reports a disposition by the partnership of appreciated property the transferor reported, if it happens while the transferor is still a direct or constructive partner.
The instructions name Schedule G (Form 8865), Schedule H (Form 8865) in certain cases, and Form 8838-P, Consent To Extend the Time To Assess Tax Pursuant to the Gain Deferral Method (Section 721(c)).