Taxpayer information
Name(s) of the consenting taxpayer(s), identifying number, the spouse's social security number only if a joint return was filed, and the address.
8838-P
Consent To Extend the Time To Assess Tax Pursuant to the Gain Deferral Method (Section 721(c))
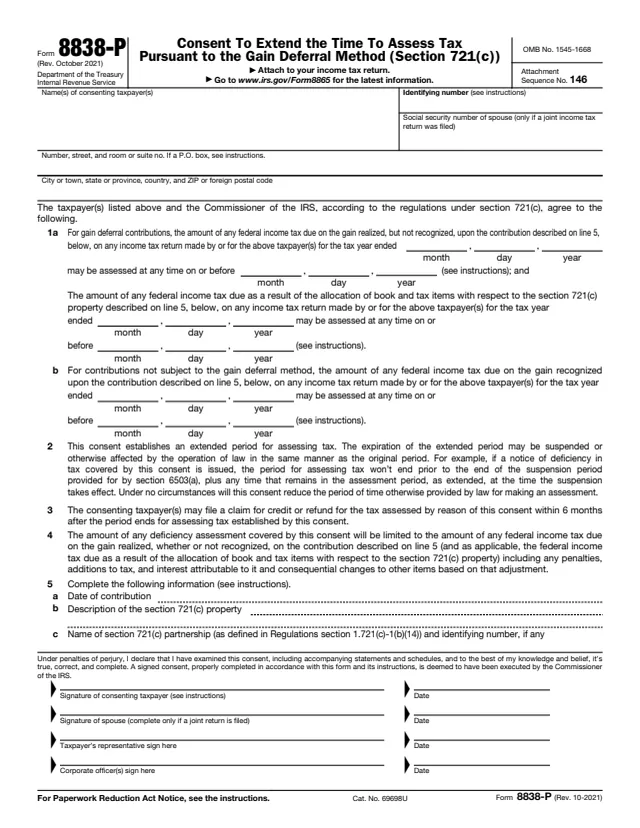
Form 8838-P is an agreement between the consenting taxpayer and the Commissioner of the IRS that extends the period for assessing tax on certain contributions of property to a partnership under section 721(c). The instructions on the form say it is used to apply the gain deferral method described in Regulations section 1.721(c)-3, for a gain deferral contribution and for certain later contributions of section 721(c) property to a section 721(c) partnership.
The filer is a U.S. transferor, which the instructions say includes a citizen or resident of the United States, a domestic corporation, and any estate or trust other than a foreign estate or trust. The form is attached to the U.S. transferor's income tax return. Its instructions are printed on page 2 of the PDF, and the form points to www.irs.gov/Form8865 for the latest information.
You can fill out Form 8838-P free in your browser on this page and download the result without an account.
Name(s) of the consenting taxpayer(s), identifying number, the spouse's social security number only if a joint return was filed, and the address.
Tax year and assessment dates for tax on the gain realized but not recognized on the contribution, and for tax from the allocation of book and tax items for the section 721(c) property.
Tax year and assessment date for tax on gain recognized on a contribution not subject to the gain deferral method.
How the extended period works with suspensions such as section 6503(a), a claim for credit or refund within 6 months after the period ends, and the limit on any deficiency assessment.
Date of contribution, description of the section 721(c) property, and the name and identifying number, if any, of the section 721(c) partnership.
Lines for the consenting taxpayer, a spouse on a joint return, the taxpayer's representative and corporate officers, each with a date.
Enter the name(s) and identifying number. The instructions say an individual uses the social security number and all other taxpayers use the employer identification number. Add the spouse's SSN only for a joint return.
Include the suite, room or other unit number after the street address. Show a P.O. box only if the Post Office doesn't deliver mail to the street address.
Enter the tax year and dates. The instructions describe an extension through the date 96 months after the close of the tax year that includes the contribution date, and for the next two years through the date 72 months after the close of such tax year.
For a contribution with recognized gain made within five partnership tax years after the year of a gain deferral contribution, the instructions describe an extension through the date 60 months after the close of the tax year that includes the contribution date.
Enter the contribution details. For more than one section 721(c) property, give line 5 information for each and indicate whether the gain deferral method is applied. Under the tiered partnership rules, identify all upper- and lower-tier partnerships.
The consenting taxpayer signs and dates. A spouse signs for a joint return, a responsible officer for a corporation, and a representative only with authority under a power of attorney.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8838-P to the U.S. transferor's income tax return for the tax year in which the gain deferral contribution is made and annually as required under Regulations section 1.721(c)-6(b)(5).
For a contribution of section 721(c) property that isn't a gain deferral contribution, attach it to the return for the tax year in which the contribution is made.
The instructions say that for a gain deferral contribution, failing to extend the period as required results in gain recognition. For other contributions, failing to file may be an acceleration event for a gain deferral contribution made within the five prior partnership tax years.
An attorney or agent attaches a copy of Form 2848. A trustee attaches Form 56 and the trust instrument. An executor or administrator attaches Form 56 and the certified copy of letters of testamentary or court certificate.
Line 3 says the consenting taxpayer(s) may file a claim for credit or refund for tax assessed under the consent within 6 months after the extended assessment period ends.
8865
461 fields, 6 pages

2848
92 fields, 2 pages
56
72 fields, 2 pages
8838
20 fields, 2 pages
8865 Sch. G
203 fields, 2 pages
The instructions say a U.S. transferor files Form 8838-P to apply the gain deferral method on a contribution of section 721(c) property to a section 721(c) partnership.
No tool matches that search.
A U.S. transferor applying the gain deferral method on a contribution of section 721(c) property to a section 721(c) partnership. The instructions say this includes U.S. citizens and residents, domestic corporations, and estates and trusts that are not foreign.
No. The form says "Attach to your income tax return," and the instructions say it goes with the U.S. transferor's income tax return.
The instructions say a taxpayer isn't required to extend the period under the form's terms, but for a gain deferral contribution, failing to do so as required under Regulations section 1.721(c)-6(b)(5) results in gain recognition.
They are printed on page 2 of the form itself. The form points to www.irs.gov/Form8865 for the latest information.
The instructions say both spouses sign, unless one, acting under a power of attorney, signs as agent for the other.
Line 3 says the consenting taxpayer(s) may file a claim for credit or refund within 6 months after the extended assessment period ends.