Taxpayer information
Names of the consenting taxpayers, identifying number, the spouse's social security number (only for a joint return) and the address.
8838
Consent To Extend the Time To Assess Tax Under Section 367--Gain Recognition Agreement
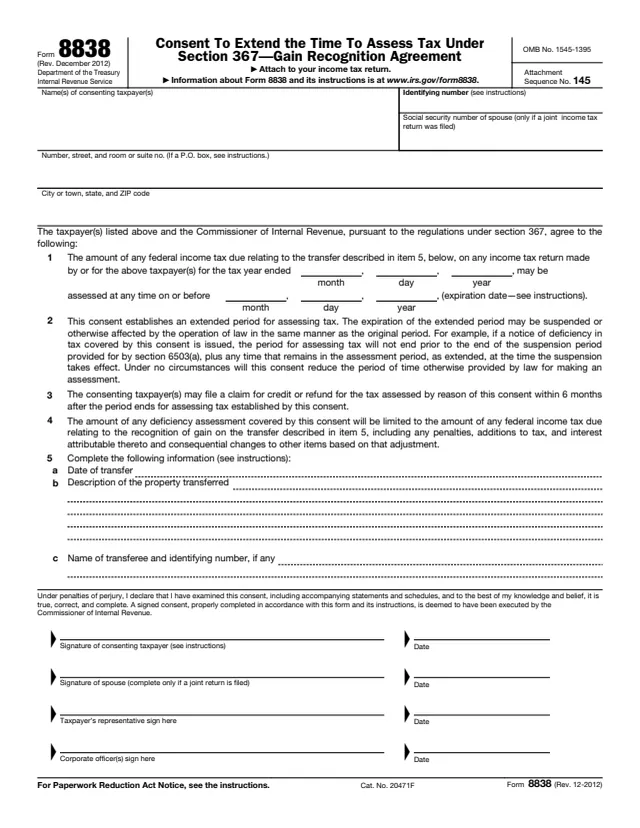
Form 8838, Consent To Extend the Time To Assess Tax Under Section 367, Gain Recognition Agreement, is used for gain recognition agreements under Internal Revenue Code sections 367(a) and 367(e)(2). By signing it, the taxpayer and the Commissioner of Internal Revenue agree that federal income tax relating to the transfer described on the form may be assessed at any time on or before an expiration date entered on line 1.
The instructions say that, although a taxpayer is not required to extend the period of limitations, failure to do so in a timely manner will invalidate the gain recognition agreement and the transfer of property will be treated as a taxable exchange. The form also says a signed consent, properly completed, is deemed to have been executed by the Commissioner.
The form says to attach it to the income tax return. Its instructions are on page 2. You can fill it out free in your browser on this page and download the result without an account.
Names of the consenting taxpayers, identifying number, the spouse's social security number (only for a joint return) and the address.
The tax year ended, and the month, day and year on or before which tax relating to the transfer may be assessed.
How the extended period may be suspended, the right to claim a credit or refund within 6 months after the period ends, and the limit on deficiency assessments to tax relating to the gain on the transfer.
The date of transfer, a description of the property transferred, and the name of the transferee and its identifying number, if any.
A penalties of perjury statement and signature lines for the consenting taxpayer, the spouse, the taxpayer's representative and corporate officers, each with a date.
The instructions say the identifying number of an individual is the social security number. For all other taxpayers, it is the employer identification number.
Include the suite, room or other unit number after the street address. Show a P.O. box only if the Post Office does not deliver mail to the street address.
The date depends on the transaction. The instructions say section 367(a) transfers extend the statute for at least 8 tax years after the tax year of the transfer. For section 367(e)(2) liquidations, at least 3 years after the distributed property is no longer used in a U.S. trade or business, and no more than 13 years from the filing of the original return for the year of the last distribution.
Enter the date of transfer, the property and the transferee. The instructions say that if a successor U.S. transferor files the form, lines a, b and c refer to the initial transfer.
The consenting taxpayer signs and dates, along with the spouse on a joint return or the authorized representative or officer. Attach Form 2848 or Form 56 when the instructions call for it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8838 to the U.S. transferor's income tax return for the tax year the transfer is made.
The instructions say failure to extend the period of limitations in a timely manner will invalidate the gain recognition agreement, and the transfer will be treated as a taxable exchange.
The instructions say Form 8838 "(or a similar statement)" is filed in the cases they describe.
Item 3 says the consenting taxpayers may file a claim for credit or refund for tax assessed because of this consent within 6 months after the extended period ends.
The form says a signed consent, properly completed in accordance with the form and its instructions, is deemed to have been executed by the Commissioner of Internal Revenue.

2848
92 fields, 2 pages
56
72 fields, 2 pages

1120
481 fields, 6 pages
1120-F
527 fields, 9 pages

1041
173 fields, 3 pages

1065
440 fields, 6 pages
The instructions say a United States transferor that enters into a gain recognition agreement under section 367(a) files Form 8838 (or a similar statement). The form is signed by the consenting taxpayer or someone authorized to sign for them.
No tool matches that search.
The About page says Form 8838 is used for gain recognition agreements under sections 367(a) and 367(e)(2). It extends the time the IRS has to assess tax relating to the transfer described on the form.
The instructions say a United States transferor that enters into a gain recognition agreement under section 367(a), or the domestic corporation and distributee foreign corporation in a section 367(e)(2) liquidation.
The instructions say to attach it to the U.S. transferor's income tax return for the tax year the transfer is made.
For section 367(a) transfers, the instructions say at least 8 tax years following the tax year of the transfer. For section 367(e)(2) liquidations, at least 3 years after all distributed property is no longer used in a trade or business within the United States, but not more than 13 years from the filing of the original return for the tax year of the last distribution.
The form says a signed consent, properly completed, is deemed to have been executed by the Commissioner of Internal Revenue.
The instructions say an attorney or agent may sign if specifically authorized by a power of attorney. Form 2848 provides the authority on line 5, and a copy is attached with Form 8838.