Identifying information
Name and identifying number of the person filing Form 5471, name and identifying number of the U.S. shareholder, name of the foreign corporation, its EIN if any, and a reference ID number.
5471 Sch. P
Previously Taxed Earnings and Profits of U.S. Shareholder of Certain Foreign Corporations
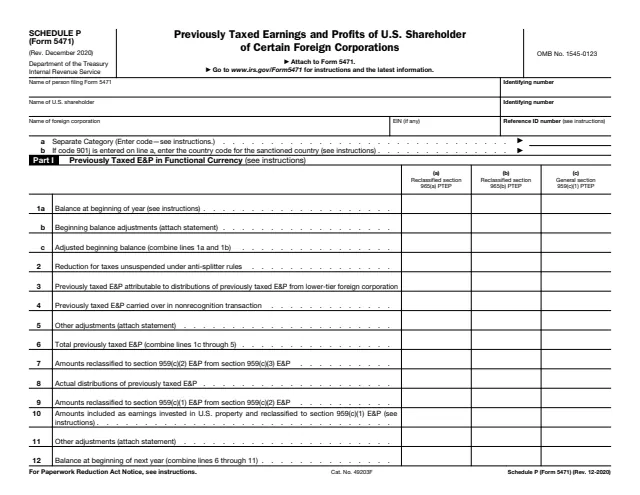
Schedule P (Form 5471), Previously Taxed Earnings and Profits of U.S. Shareholder of Certain Foreign Corporations, is one of the schedules filed with Form 5471. The instructions say to "use Schedule P to report the PTEP in the U.S. shareholder's annual PTEP accounts with respect to a CFC in the CFC's functional currency (Part I) and the U.S. shareholder's U.S. dollar basis in that PTEP (Part II)." PTEP stands for previously taxed earnings and profits, and CFC for controlled foreign corporation.
The schedule is completed by U.S. shareholders who are Category 1a, 1b, 4, 5a or 5b filers of Form 5471, and the form says "Attach to Form 5471." Each schedule covers one foreign corporation and one separate category of income, with columns for each PTEP group from section 965 PTEP to section 951A and section 959(c)(1) PTEP.
This page covers the December 2020 revision. You can fill it out free in your browser on this page and download the result without an account.
Name and identifying number of the person filing Form 5471, name and identifying number of the U.S. shareholder, name of the foreign corporation, its EIN if any, and a reference ID number.
Line a takes the separate category code. Line b takes the country code for the sanctioned country when code 901j is entered on line a.
Lines 1a to 12 run from the balance at beginning of year, through reductions, carryovers, reclassifications and actual distributions, to the balance at beginning of next year.
Reclassified section 965(a), 965(b), 951A and 245A(d) PTEP, general section 959(c)(1) PTEP, section 965(a), 965(b), 951A, 245A(d) and 951(a)(1)(A) PTEP, and a total column.
The same lines 1a to 12 and columns (a) to (k), stated in U.S. dollars on pages 3 and 4.
Enter the filer, the U.S. shareholder and the foreign corporation. The instructions say to use the reference ID number shown on Form 5471, page 1, item 1b(2), if applicable.
Complete a separate Schedule P for each separate category of income and enter its code, found under Categories of Income in the Instructions for Form 1118. The instructions add a separate schedule with code TOTAL when there is more than one category.
The instructions say not to complete a separate Schedule P for the section 951A category. That PTEP goes on the Schedule P completed for the general category.
If last year's ending balance differs from what it should be, include the difference on line 1b and attach an explanation. Multiple differences each get an explanation and amount on the attachment.
Enter amounts in the foreign corporation's functional currency as reported on Form 5471, page 1, item 1h. Columns (a) to (j) correspond to columns (e)(i) to (e)(x) of Schedule J.
Enter the U.S. shareholder's dollar basis in the PTEP. The instructions say it is generally equal to the U.S. dollar amount of E&P previously included in gross income.
The Instructions for Form 5471 have a section on Schedule P.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says "Attach to Form 5471." The instructions say to attach Form 5471 to the income tax return (or partnership or exempt organization return) and file both by its due date, including extensions.
The instructions say a required schedule with all zero amounts is still filed with one or more zero amounts, and for schedules completed by category, a single instance for any separate category meets the requirement.
If a U.S. shareholder wholly owns the CFC, the instructions say Schedule P should include the same information as column (e) of Schedule J, Part I. With more than one shareholder the amounts might differ.
Amounts in column (d) of Schedule R (Form 5471) are also included on Part I, line 8, of Schedule P, the instructions say.
The schedule PDF is the December 2020 revision. The Instructions for Form 5471 that cover it are revised 12/2025.

5471
437 fields, 6 pages
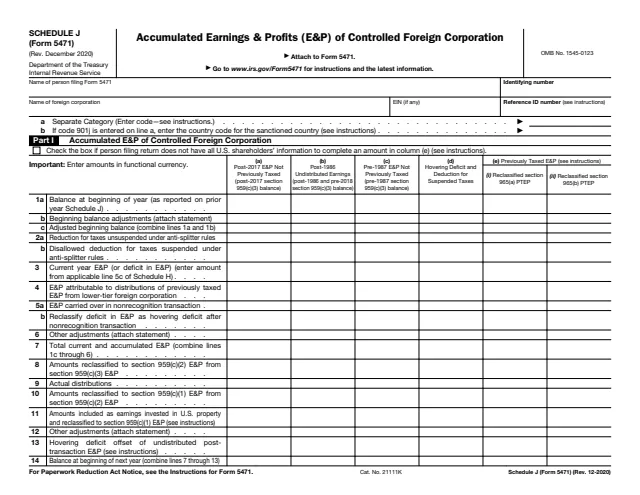
5471 Sch. J
282 fields, 3 pages
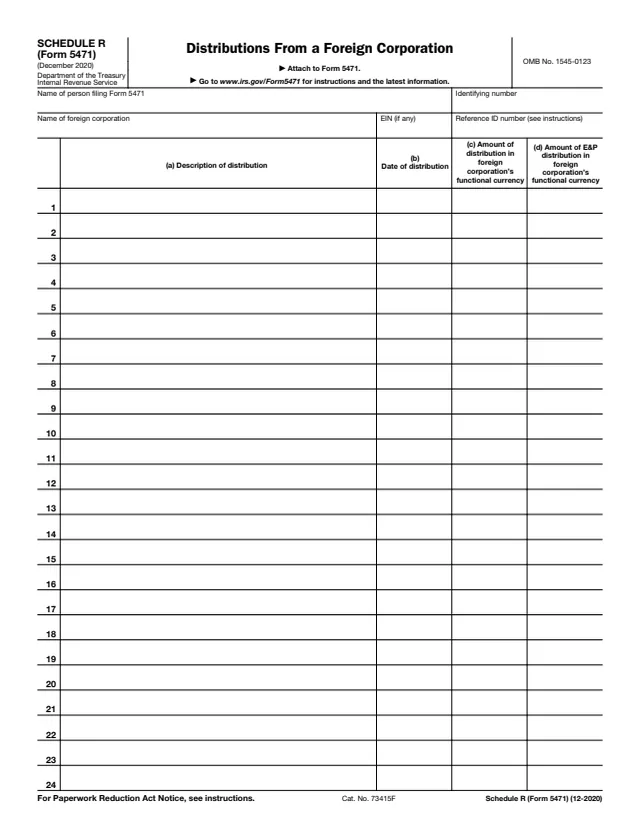
5471 Sch. R
101 fields, 1 page
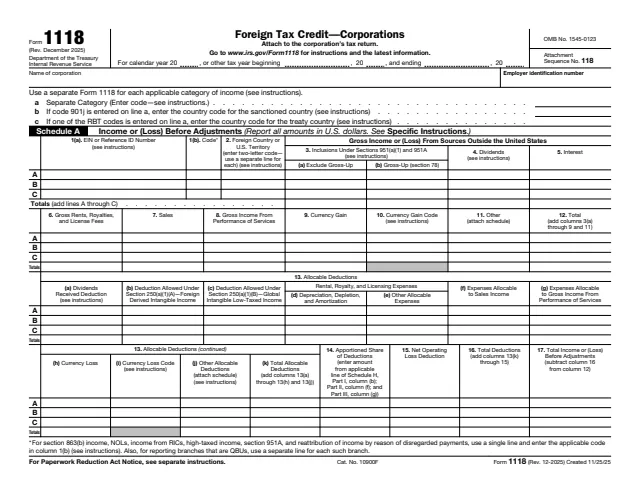
1118
1,263 fields, 12 pages
5471 Sch. Q
691 fields, 4 pages
5471 Sch. H
41 fields, 1 page
The instructions say a separate Schedule P is completed by each Category 1a, 1b, 4, 5a or 5b filer. The categories are defined in the Instructions for Form 5471.
No tool matches that search.
The instructions say each Category 1a, 1b, 4, 5a or 5b filer completes a separate Schedule P. Other categories of Form 5471 filers are not listed for it.
No. The schedule says "Attach to Form 5471," and Form 5471 is attached to the filer's income tax return.
One for each separate category of income for each foreign corporation, plus one with code TOTAL that aggregates the others when there is more than one category, the instructions say.
Part I reports the PTEP in the CFC's functional currency. Part II reports the U.S. shareholder's U.S. dollar basis in that PTEP, which the instructions say is used to determine foreign currency gain or loss under section 986(c).
Columns (a) through (j) of Schedule P correspond to columns (e)(i) through (e)(x) of Schedule J, and the instructions point to Schedule J for specific line instructions.
The instructions say that when a schedule is required but all amounts are zero, it should still be filed with one or more zero amounts.