Lines a, b and c: category of income
Line a takes the code for the separate category the form covers, such as 951A, FB, PAS, 901j, GEN or an RBT code. Lines b and c take a country code for the 901j and RBT categories.
1118
Foreign Tax Credit—Corporations
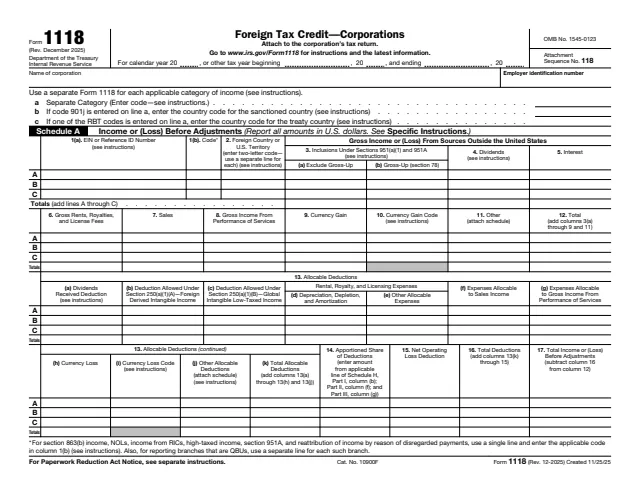
Form 1118 is the foreign tax credit form for corporations. The instructions say it is used to compute a corporation's foreign tax credit for certain taxes paid or accrued to foreign countries or U.S. territories. The form says to attach it to the corporation's tax return and to use a separate Form 1118 for each applicable category of income.
The 12-page form holds Schedules A through H, with Schedule F reserved. Schedules I, J, K and L (Form 1118) are separate schedules with their own PDFs, listed on the About Form 1118 page.
The instructions also say Form 1118 is not used to determine foreign tax credits for the corporate alternative minimum tax; Form 4626 is used for that. This page covers the December 2025 revision. You can fill it out free in your browser on this page and download it without an account.
Line a takes the code for the separate category the form covers, such as 951A, FB, PAS, 901j, GEN or an RBT code. Lines b and c take a country code for the 901j and RBT categories.
Gross income from sources outside the United States by foreign country or U.S. territory, then allocable and apportioned deductions and any net operating loss deduction, all in U.S. dollars.
Part I lists foreign taxes paid, accrued and deemed paid. Part II figures the separate credit and its limitation. Part III adds the separate credits and gives the total foreign tax credit.
Tax deemed paid with respect to section 951(a)(1) inclusions (Schedule C), section 951A income (Schedule D), and previously taxed earnings and profits (PTEP) (Schedule E).
Lines A through I reduce taxes paid, accrued or deemed paid, for example for foreign oil and gas taxes, international boycott provisions and taxes suspended under section 909. Part II has two check boxes for disqualified taxes.
Research and experimental deductions, deductions allocated and apportioned based on assets, and other deductions. The form says to complete it only once for all categories of income.
The instructions say to compute a separate credit on a separate Form 1118 for each applicable category and enter its code on line a. With a 901j or RBT code, line b or c takes a country code from IRS.gov/CountryCodes.
The instructions say to report foreign source gross income for the category in columns 3(a) through 11, deductions in columns 13 and 14, and any net operating loss carryover in column 15. Amounts are in U.S. dollars.
Check whether the credit is claimed for taxes paid or accrued, then enter the foreign taxes by type. The form says to attach a schedule showing amounts in foreign currency and the conversion rate(s) used.
Line 6 totals the foreign taxes. Lines 7 through 13 figure the credit limitation from the limitation fraction and the U.S. income tax. Line 14 is the smaller of line 6 or line 13.
Enter the line 14 credit for each category on lines 1 through 6, apply any reduction for international boycott operations on line 9, and enter line 10 on the corporation's tax return.
The instructions say Schedule B, Part III, Schedule H, Schedule J (Form 1118) and Schedule L (Form 1118), Part IV are completed only once, while the other schedules are completed for each category.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the corporation's tax return. The instructions point to Where To File in the instructions for the return it is filed with.
The instructions say a corporation may choose either a credit or a deduction for eligible foreign income taxes paid or accrued, and the choice is made annually.
The instructions say the election to claim the credit may be made or changed at any time before the end of a special 10-year period described in section 6511(d)(3).
Excess taxes in a category are carried back 1 year, then carried forward 10 years, in the same category. The instructions say this does not apply to taxes assigned to section 951A category income.
Receipts or a foreign tax return are not attached, but the instructions say proof is presented on IRS request. For tax accrued but not paid, the IRS may require a bond on Form 1117.
A corporation relying on a treaty to claim a credit completes Form 8833 and attaches it to Form 1118. The instructions say failure to report may result in a $10,000 penalty.
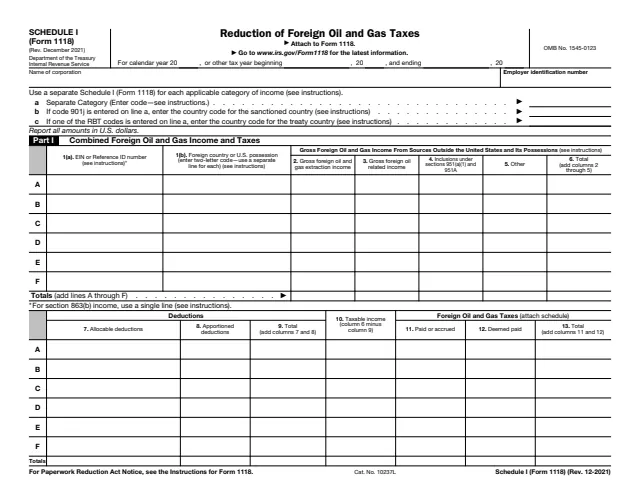
1118 Sch. I
113 fields, 2 pages
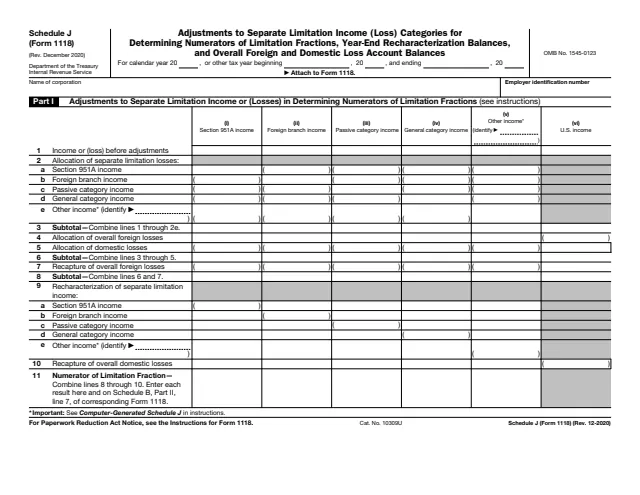
1118 Sch. J
227 fields, 2 pages
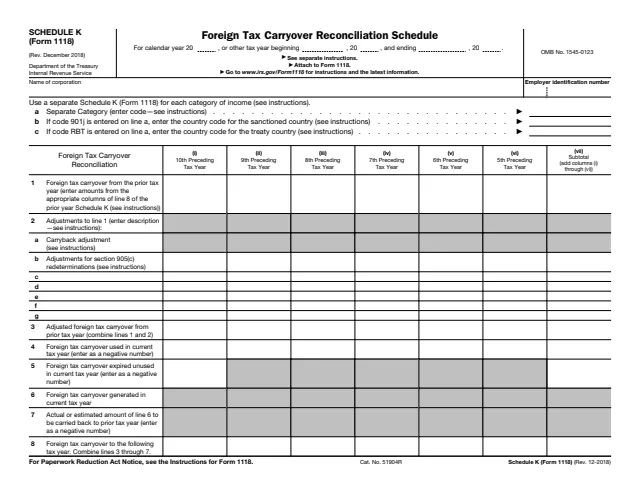
1118 Sch. K
231 fields, 2 pages
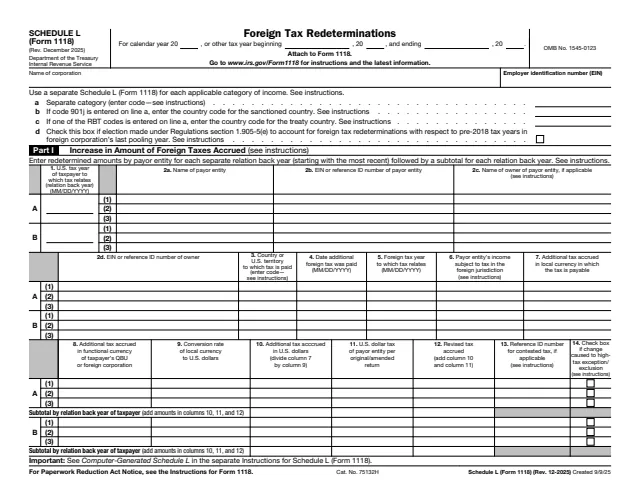
1118 Sch. L
317 fields, 4 pages
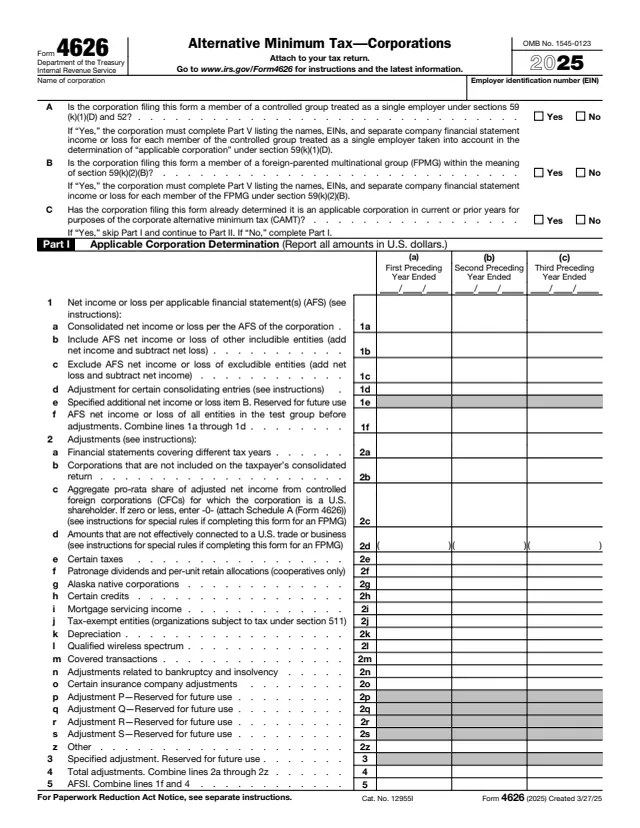
4626
813 fields, 8 pages
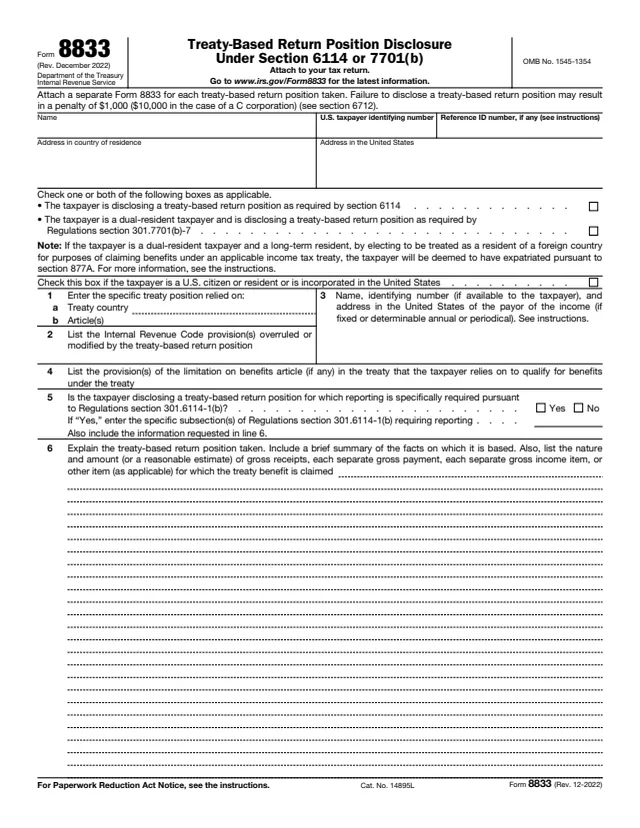
8833
41 fields, 5 pages
The instructions name corporations first. Individuals use it only in the section 962 case described below.
No tool matches that search.
No. The form says to attach it to the corporation's tax return.
The instructions say a separate Form 1118 for each applicable separate category of income, such as section 951A, foreign branch, passive or general category income.
The instructions say individuals who make the section 962 election attach Form 1118 to their income tax return to claim a credit based on their share of foreign income taxes paid or accrued by a controlled foreign corporation.
No. The instructions say corporations use the revised Form 4626 to determine foreign tax credits for the corporate alternative minimum tax.
The instructions say documentation such as receipts or a foreign tax return is not attached, but proof is presented if the IRS asks for it.
The instructions say a computer-generated Form 1118 may be submitted if it conforms to the IRS version and the software is approved for substitute forms. They point to Pub. 1167.