Items A, B and C
Whether the corporation is in a controlled group under sections 59(k)(1)(D) and 52, is an FPMG member, and has already determined it is an applicable corporation.
4626
Alternative Minimum Tax—Corporations
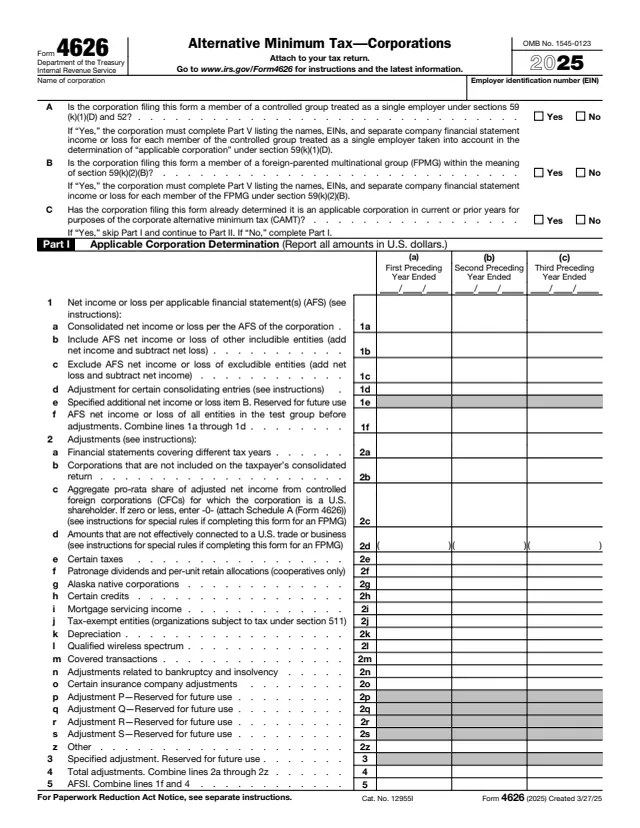
Form 4626, Alternative Minimum Tax for Corporations, is a corporate form. The instructions say it is used to determine whether a corporation is an applicable corporation under section 59(k) and to calculate the corporate alternative minimum tax (CAMT) under section 55 for applicable corporations. This page covers the 2025 form, which the corporation attaches to its income tax return.
The form starts with three yes or no items, then Part I tests applicable corporation status from adjusted financial statement income (AFSI) over the three preceding tax years. Part II figures the tax, starting from net income on the applicable financial statement (AFS) and multiplying AFSI by 15%. Parts III to VI hold the supporting schedules for certain taxes, the CAMT foreign tax credit, group members and controlled foreign corporations (CFCs).
The What's New section of the instructions lists a new Item C and a new optional interim simplified method for checking applicable corporation status. You can fill out Form 4626 free in your browser on this page and download it without an account.
Whether the corporation is in a controlled group under sections 59(k)(1)(D) and 52, is an FPMG member, and has already determined it is an applicable corporation.
AFS net income and adjustments for the first, second and third preceding years, the 3-year average annual AFSI, the $1 billion question on line 8 and the FPMG $100 million test on lines 10 to 16.
Current-year AFSI, the financial statement net operating loss, 15% of AFSI, the CAMT foreign tax credit, tentative minimum tax, regular tax, base erosion minimum tax and the alternative minimum tax on line 13.
Foreign and federal current and deferred income tax provisions and taxes in equity method investment income, totaled on line 7 and carried to Part II, line 2g.
Section I figures the credit, Section II lists allowable CFC CAMT foreign income taxes by CFC, and Section III reconciles the carryover for CFCs.
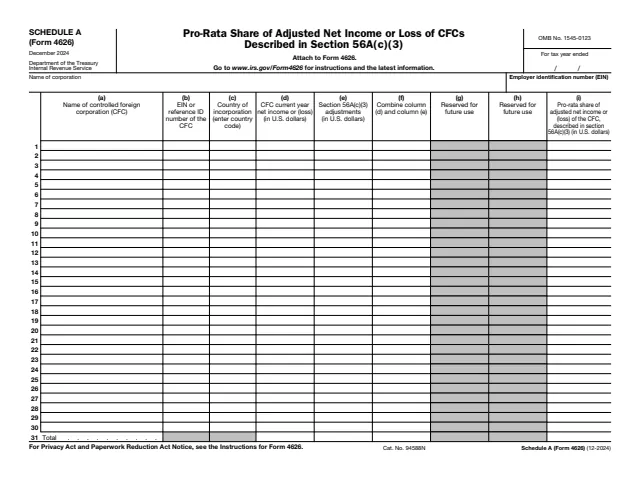
Part V lists controlled group and FPMG members with EINs and financial statement income. Part VI lists each CFC's pro-rata share of adjusted net income or loss.
Answer the three questions. A Yes on Item A or Item B means Part V is completed. A Yes on Item C means Part I is skipped and the corporation continues to Part II.
Enter AFS net income or loss and adjustments in columns (a), (b) and (c) for the 3-tax-year period before the current year, then divide line 6 by the number of tax years to get the average on line 7.
The instructions say that if line 7 is $1 billion or less, check No, stop and attach the form to the return. FPMG members continue to the $100 million test, which ends on line 16.
Complete Part III for line 2g, Part VI for line 2e, and Part IV if the corporation elects the section 901 foreign tax credit for regular tax. Their totals carry into Part II.
Figure AFSI, multiply line 6 by 15% (0.15), subtract the CAMT foreign tax credit, then subtract regular tax and base erosion minimum tax. Line 13 goes on Form 1120, Schedule J, line 3, or the matching line of the return.
The instructions say corporations include with Form 4626 a statement describing the approach taken and the guidance relied upon, such as the sections of the proposed regulations applied.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 4626 to the corporation's income tax return (or exempt organization business income tax return, if applicable) and file by the due date, including extensions, for that return.
Under Notice 2025-27, the instructions say a corporation with average annual AFSI under $800 million for the three preceding tax years that was not an applicable corporation in a prior year generally is not one and is not required to file Form 4626.
The instructions include an Interim Simplified Method (Safe Harbor) Calculation Worksheet. They say not to complete it if the corporation already determined it is an applicable corporation.
The instructions say incomplete or nonspecific responses, including phrases such as "available upon request", are not sufficient responses in Part V.
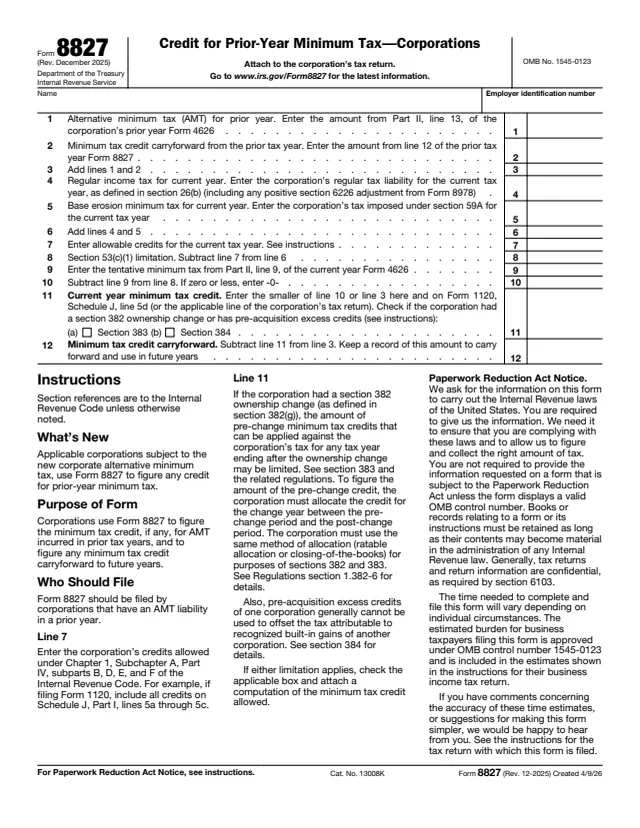
The instructions point to Form 8827, Credit for Prior Year Minimum Tax, Corporations, for a credit against regular tax and base erosion minimum tax for alternative minimum tax from prior years.
The About page lists updates to the 2025 instructions with additional interim guidance (20-FEB-2026) and a new simplified method for determining CAMT status (17-SEPT-2025).
8827
16 fields, 1 page
4626 Sch. A
283 fields, 1 page

1120
481 fields, 6 pages
1118
1,263 fields, 12 pages

3800
1,921 fields, 9 pages
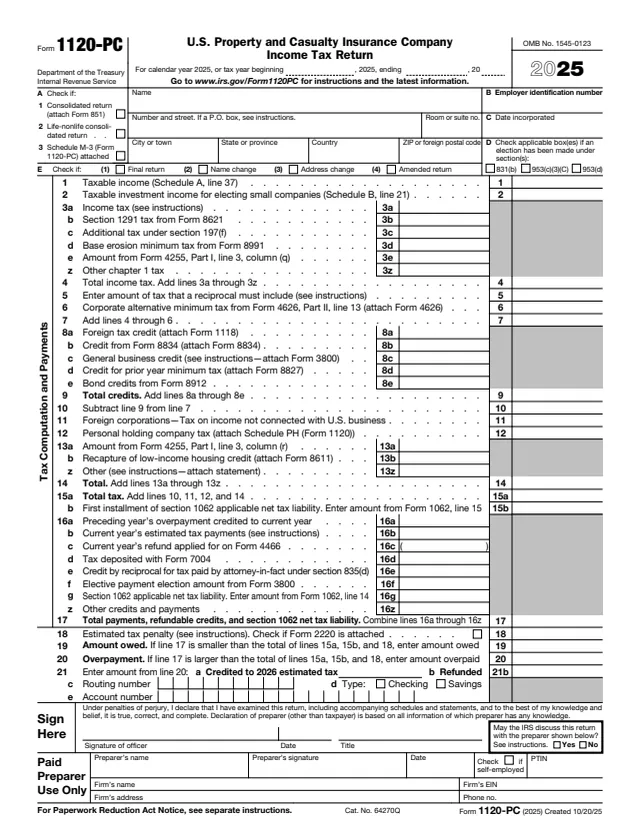
1120-PC
565 fields, 9 pages
Corporations complete the form, and it goes to the IRS attached to the corporation's own return. The instructions say a corporation files it, unless a filing exclusion applies, to determine whether it is an applicable corporation and, if so, to calculate CAMT.
No tool matches that search.
The instructions say it is used to determine whether a corporation is an applicable corporation under section 59(k) and to calculate the corporate alternative minimum tax under section 55 for applicable corporations.
The instructions list S corporations, regulated investment companies, real estate investment trusts, tax-exempt entities with no unrelated business taxable income, and corporations not applicable under a simplified method they choose to apply.
The instructions say a corporation meets the general AFSI test when its average annual AFSI for the prior 3-tax-year period exceeds $1 billion. An FPMG member also faces a $100 million test.
Line 7 of Part II multiplies AFSI by 15% (0.15). The CAMT foreign tax credit is then subtracted to get the tentative minimum tax.
The form says to enter it on Form 1120, Schedule J, line 3, or the appropriate line of the corporation's income tax return.
No. The form says to attach it to the tax return, filed by that return's due date including extensions.
Item C is new for 2025. It asks whether the corporation already determined it is an applicable corporation in current or prior years. If Yes, Part I is skipped.