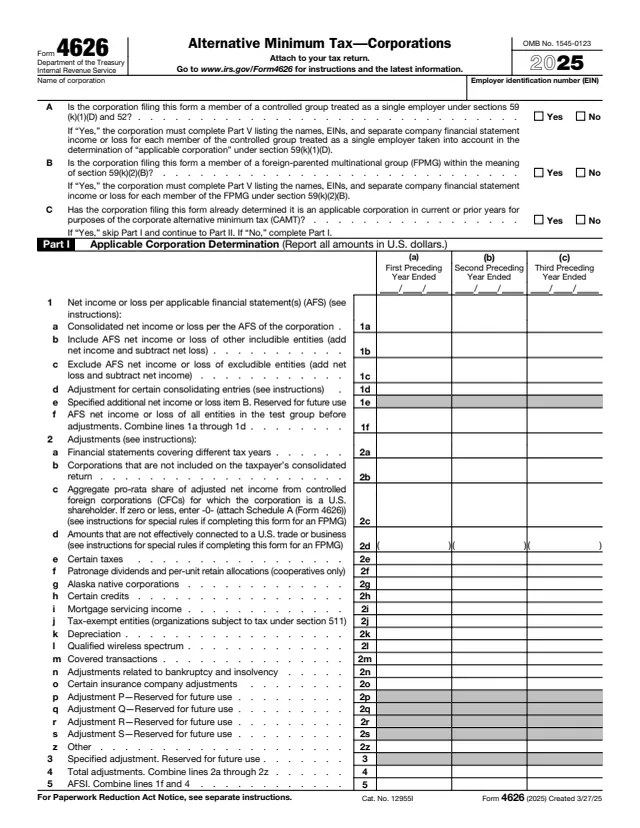
Lines 1 to 3: prior-year amounts
AMT for the prior year from Part II, line 13, of the prior year Form 4626, plus the carryforward from line 12 of the prior year Form 8827.
8827
Credit for Prior-Year Minimum Tax—Corporations
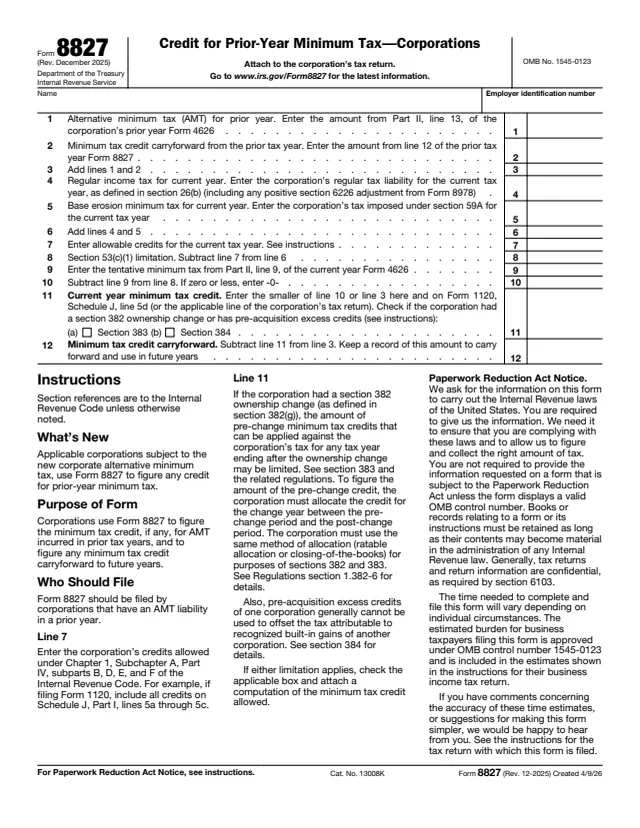
Form 8827 is the IRS form corporations use to figure the minimum tax credit, if any, for alternative minimum tax (AMT) incurred in prior tax years, and to figure any minimum tax credit carryforward to future years. It is a one-page form with its instructions printed on the same page.
The instructions say Form 8827 should be filed by corporations that have an AMT liability in a prior year. Under What's New, they say applicable corporations subject to the new corporate alternative minimum tax use Form 8827 to figure any credit for prior-year minimum tax. The form says to attach it to the corporation's tax return.
The credit figured on line 11 goes on Form 1120, Schedule J, line 5d, or the applicable line of the corporation's return. You can fill it out free in your browser on this page and download the result without an account.
AMT for the prior year from Part II, line 13, of the prior year Form 4626, plus the carryforward from line 12 of the prior year Form 8827.
Regular income tax for the current year, as defined in section 26(b), plus the base erosion minimum tax under section 59A.
Allowable credits for the current tax year, subtracted from line 6.
The tentative minimum tax from Part II, line 9, of the current year Form 4626, subtracted from line 8.
The smaller of line 10 or line 3, with boxes for section 383 and section 384.
Line 3 minus line 11. The form says to keep a record of this amount to carry forward and use in future years.
Enter the prior year AMT from the prior year Form 4626, Part II, line 13, and the carryforward from line 12 of the prior year Form 8827. Add them on line 3.
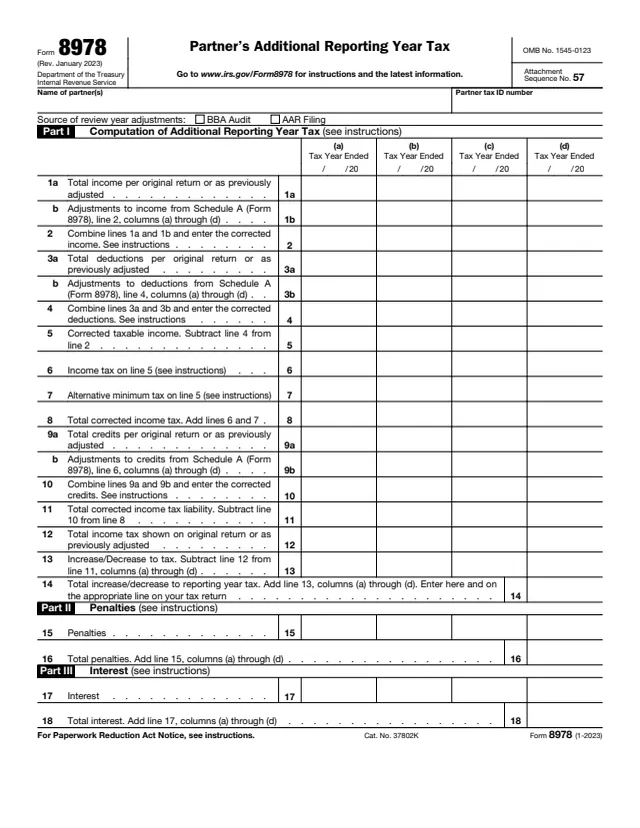
Enter the corporation's regular tax liability for the current year, including any positive section 6226 adjustment from Form 8978, and its section 59A tax. Add them on line 6.
The instructions say to enter credits allowed under Chapter 1, Subchapter A, Part IV, subparts B, D, E, and F. For Form 1120, that includes all credits on Schedule J, Part I, lines 5a through 5c.
Subtract line 7 from line 6, enter the tentative minimum tax from the current year Form 4626, Part II, line 9, and subtract it. If zero or less, the form says to enter -0-.
Enter the smaller of line 10 or line 3 here and on Form 1120, Schedule J, line 5d, or the applicable line. Check box (a) or (b) if a section 383 or 384 limitation applies and attach a computation.
Subtract line 11 from line 3 and keep a record of the carryforward, as the form says.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the corporation's tax return.
The form says to enter line 11 on Form 1120, Schedule J, line 5d, or the applicable line of the corporation's tax return.
The instructions say that after a section 382 ownership change, the pre-change minimum tax credits that can be applied against the corporation's tax may be limited. See section 383 and the related regulations.
The instructions say pre-acquisition excess credits of one corporation generally cannot be used to offset the tax attributable to recognized built-in gains of another corporation.
The form says to keep a record of the line 12 carryforward to use in future years.
The form and its instructions are written for corporations. It is attached to the corporation's tax return.
No tool matches that search.
The instructions say it should be filed by corporations that have an AMT liability in a prior year. Applicable corporations subject to the new corporate AMT also use it.
The form says to enter line 11 on Form 1120, Schedule J, line 5d, or the applicable line of the corporation's tax return.
Line 1 comes from Part II, line 13, of the prior year Form 4626, and line 9 from Part II, line 9, of the current year Form 4626.
Line 12 figures the minimum tax credit carryforward. The form says to keep a record of it to carry forward and use in future years.
No separate instructions are linked. The instructions are printed on the form itself, below the lines.