Header and source of adjustments
Name of partner(s), partner tax ID number, and two boxes for the source of review year adjustments: BBA Audit or AAR Filing.
8978
Partner's Additional Reporting Year Tax
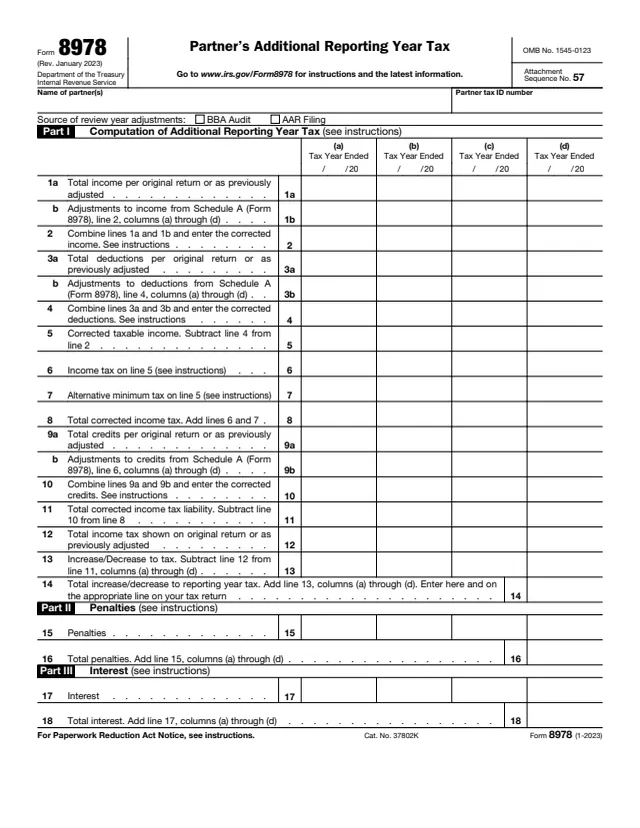
Form 8978, Partner's Additional Reporting Year Tax, is used by partners other than pass-through partners (such as partnerships or S corporations) to report adjustments shown on Forms 8986 they received from partnerships that elected to push out adjustments to partnership-related items to their partners. The IRS About page says these partners use it to re-figure their tax liabilities for the affected years and any intervening years, up to the adjustment year.
The form works with Schedule A (Form 8978), which lists each adjustment. Part I carries the Schedule A totals for income, deductions and credits into up to four columns, one per tax year, and figures the increase or decrease to tax. Parts II and III hold penalties and interest. The instructions say Form 8978 is filed with the partner's federal income tax return for the reporting year.
You can fill out Form 8978 free in your browser on this page and download the PDF without an account.
Name of partner(s), partner tax ID number, and two boxes for the source of review year adjustments: BBA Audit or AAR Filing.
Income and deductions per the original return or as previously adjusted, the adjustments from Schedule A, lines 2 and 4, and corrected taxable income, in columns (a) through (d), one per tax year ended.
Income tax and alternative minimum tax on line 5, credits per the return plus the Schedule A, line 6 adjustments, corrected income tax liability, tax as previously shown, and the increase or decrease for each column.
The sum of line 13, columns (a) through (d). The form says to enter it here and on the appropriate line of the tax return.
Line 15 holds penalties for each tax year column and line 16 their total.
Line 17 holds interest for each tax year column and line 18 their total.
Check BBA Audit or AAR Filing. The instructions say adjustments from an AAR and from a BBA audit go on separate Forms 8978 and Schedules A, and the AAR-related form is completed first when both apply.
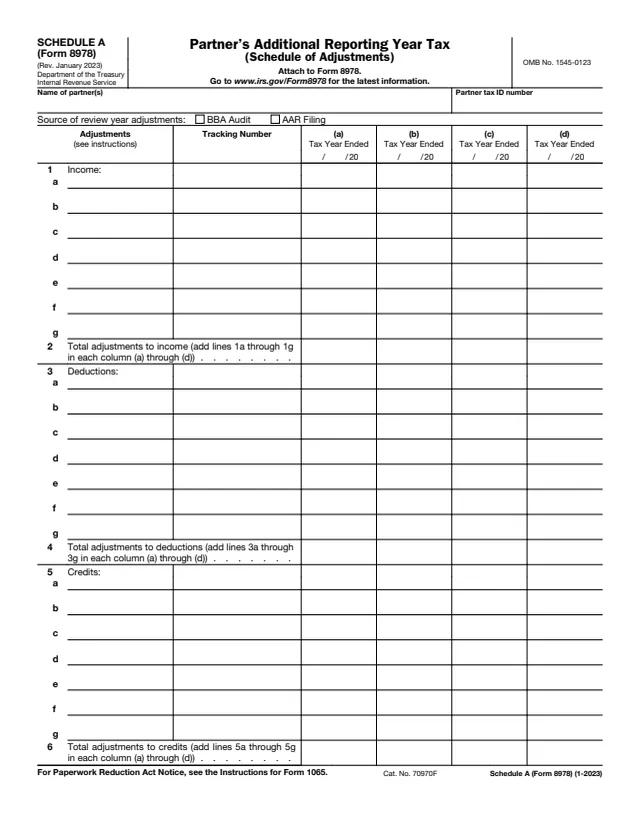
List each adjustment from Form 8986, Part V, on Schedule A (Form 8978). Its totals on lines 2, 4 and 6 go to Form 8978, lines 1b, 3b and 9b.
For each tax year column, enter income and deductions as shown on the original or amended return or as adjusted by the IRS, add the adjustments, and subtract line 4 from line 2.
The instructions ask for a separate statement showing how corrected income tax and any AMT were figured. Combine the credits, subtract to get corrected liability, then subtract line 12 from line 11.
Add line 13 across all columns and carry the total to the reporting year income tax return. With more than 4 applicable tax years, the instructions say to prepare additional Forms 8978.
Enter penalties listed on Form 8986, Part V, with a statement showing how they were figured, and interest for each year with the computation attached. The instructions say interest is not figured on decreases in tax.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 8978 is filed with the federal income tax return for the partner's reporting year, along with Schedule A (Form 8978) and the calculation statements.
The partner's tax year that includes the date the partnership furnished the Forms 8986. That date is on Form 8986, Part II, item G.
The instructions say interest on an increase in tax uses the underpayment rate with five percentage points in place of three. For a Form 8986 from an AAR, that substitution is not made.
The instructions say penalties and interest are included in the net payment for the reporting year but are not reported on the return and are not part of the additional reporting year tax.
Credit changes reported on Form 8978 are not repeated on Form 3800. Supporting Forms 3800 may be attached when each is labeled "Form 3800 for Form 8978 Calculation Only."
The instructions say Form 8978 is only for income tax. Related changes such as self-employment tax go on an amended return for the first affected year.
8978 Sch. A
154 fields, 1 page
8082
59 fields, 2 pages

3800
1,921 fields, 9 pages
1040-X
166 fields, 2 pages

1065
111 fields, 1 page
1065
2,862 fields, 21 pages
The instructions say every partner (except pass-through partners) that receives a Form 8986 from a pass-through entity files Form 8978 to report any additional reporting year tax from its share of the reviewed year adjustments.
No tool matches that search.
The instructions say every partner, except pass-through partners, that receives a Form 8986 from a pass-through entity files it to report additional reporting year tax.
No. The instructions say it is filed with the partner's federal income tax return for the reporting year, together with Schedule A (Form 8978) and the supporting statements.
Each source type goes on its own Form 8978 and Schedule A. The instructions say to complete the AAR-related form first and report the sum of all line 14 amounts on the return.
The instructions say to prepare additional Forms 8978, each with its own Schedule A, and report the total of all line 14 amounts on the return.
Only applicable tax years: the first affected year and any intervening year with related changes. The instructions say a year that is not impacted does not have to be shown.
On the appropriate line of the partner's income tax return for the reporting year, following the instructions for that return.