Header and lines a to c
Name of corporation, EIN, tax year, the separate category code on line a, a sanctioned country code for code 901j on line b, and a treaty country code for code RBT on line c.
1118 Sch. K
Foreign Tax Carryover Reconciliation Schedule
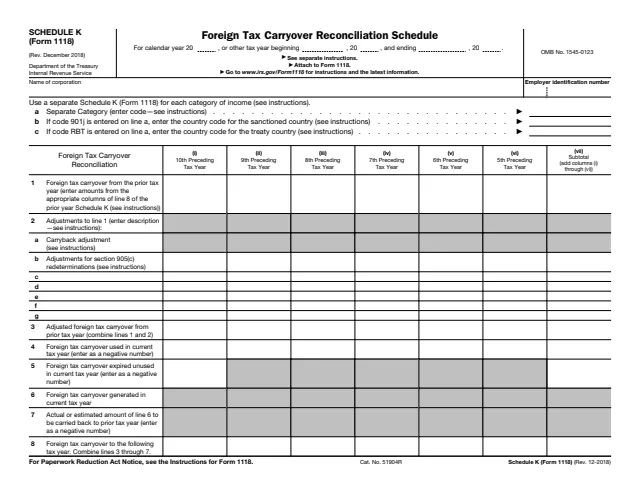
Schedule K (Form 1118) is the Foreign Tax Carryover Reconciliation Schedule. The instructions say it is used to reconcile the corporation's prior year foreign tax carryover with its current year foreign tax carryover, so corporations report running balances of their foreign tax carryovers showing all activity since the filing of the prior year income tax return.
It is a corporate schedule, attached to Form 1118, the foreign tax credit form for corporations. The form says to use a separate Schedule K for each category of income. Its columns run from the 10th preceding tax year through the current tax year, with a subtotal on page 1 and totals on page 2, and its eight lines trace the carryover from the prior year to the following year.
This page has the December 2018 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
Name of corporation, EIN, tax year, the separate category code on line a, a sanctioned country code for code 901j on line b, and a treaty country code for code RBT on line c.
Page 1 covers the 10th through 5th preceding tax years, with a subtotal in column (vii). Page 2 carries that subtotal, the 4th through 1st preceding years, the current tax year, and totals in column (xiv).
Carryover from the prior tax year, adjustments on lines 2a to 2g (carryback adjustment, section 905(c) redeterminations and others), and the adjusted carryover on line 3.
Carryover used in the current tax year and carryover expired unused in the current tax year, both entered as negative numbers.
Carryover generated in the current tax year, the actual or estimated amount carried back to the prior tax year (as a negative number), and the carryover to the following tax year.
Enter the same separate category code, and any country code, shown on the Form 1118 this schedule is attached to. The instructions say all information is in English and all amounts in U.S. dollars.
Enter amounts from line 8 of the prior year Schedule K, moved one column. The instructions give the example of prior year line 8, column (ii) going on current year line 1, column (i).
Report adjustments from events between the prior and current year returns: the carryback adjustment on 2a, section 905(c) redeterminations on 2b, and others such as reorganizations or domestic audit adjustments on 2c onward, each with a brief description.
Combine lines 1 and 2. The instructions say the column (xiv) total is included on Form 1118, Schedule B, Part II, line 5.
Line 4 is completed only with a current year excess limitation, starting with column (i). Line 5 is completed only for the 10th preceding tax year and the subtotal and totals columns.
Line 6 is completed only with current year excess foreign taxes, in columns (xiii) and (xiv). Line 7 holds any carryback, which may be estimated. Line 8 combines lines 3 through 7.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 1118 and to see the separate instructions. Its instructions give no separate mailing address.
The line 3, column (xiv) total is included on Form 1118, Schedule B, Part II, line 5, as the adjusted carryover available for credit in the current tax year.
If an estimated line 7 amount differs from the actual carryback, the instructions say the difference is entered on line 2a of the next year's Schedule K (Form 1118).
The instructions note that to carry back amounts to the first preceding tax year, that year must be an excess limitation year.
The instructions point to section 904(c), Regulations section 1.904-2 and Temporary Regulations section 1.904-2T.
1118
1,263 fields, 12 pages
1118 Sch. J
227 fields, 2 pages
1118 Sch. L
317 fields, 4 pages
1118 Sch. I
113 fields, 2 pages
Corporations that file Form 1118 complete this schedule. It is not a form individuals file.
No tool matches that search.
The instructions say any corporation filing Form 1118 that has a foreign tax carryover in the prior tax year, the current tax year, or both, files it for that separate category of income.
One for each category of income, the form says. Each uses the same separate category code as the Form 1118 it is attached to.
No. The instructions say not to complete it for section 951A category income, because the section 904(c) carryover provisions do not apply to those foreign taxes.
The instructions say a corporation has excess limitation when its foreign tax credit limitation (Schedule B, Part II, line 11) exceeds its current year foreign taxes available for credit (Schedule B, Part II, lines 1 through 4).
The form says to enter lines 4, 5 and 7 as negative numbers. They reduce the carryover: amounts used, amounts expired unused and amounts carried back.
The instructions say the difference between the estimated line 7 amount and the actual carryback is entered on line 2a of the following year's Schedule K.