Header: name and EIN
The corporation's name and employer identification number (EIN), under the 2025 tax year printed at the top.
1120
Foreign Operations of U.S. Corporations
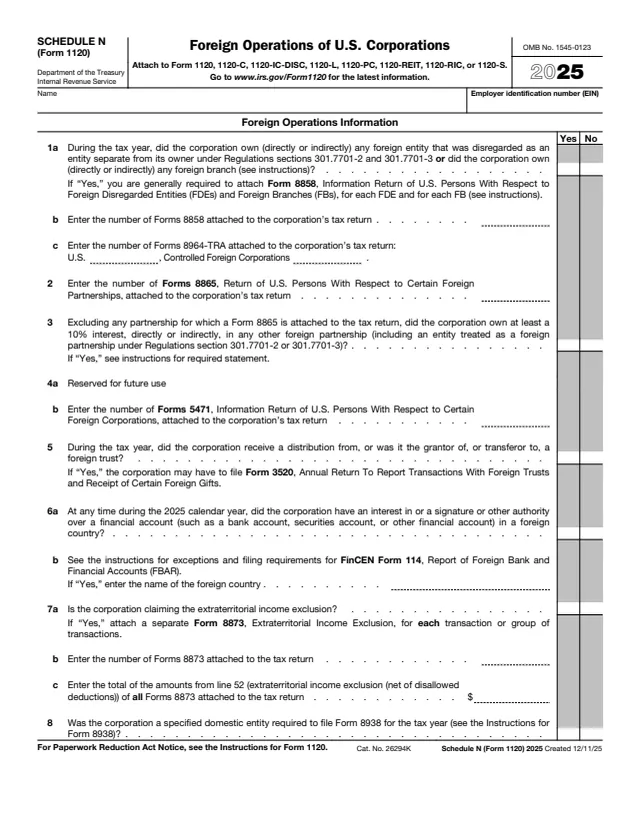
Schedule N (Form 1120) collects information about a corporation's foreign operations. Its questions cover foreign disregarded entities and foreign branches, foreign partnerships, foreign corporations, foreign trusts, financial accounts in a foreign country, the extraterritorial income exclusion and Form 8938.
The schedule is not a return on its own. The form says to attach it to Form 1120, 1120-C, 1120-IC-DISC, 1120-L, 1120-PC, 1120-REIT, 1120-RIC, or 1120-S. The instructions on page 2 say corporations that, at any time during the tax year, had assets in or operated a business in a foreign country or a U.S. territory may have to file it, and that a corporation answering "Yes" to any question on page 1 attaches Schedule N and the applicable forms and schedules to its return.
This is the 2025 version. You can fill it out free in your browser on this page and download the result without an account.
The corporation's name and employer identification number (EIN), under the 2025 tax year printed at the top.
Ownership of foreign disregarded entities or foreign branches, the number of Forms 8858 attached, and the number of Forms 8964-TRA attached for U.S. and controlled foreign corporations.
The number of Forms 8865 attached, and whether the corporation owned at least a 10% interest, directly or indirectly, in any other foreign partnership.
Line 4a is reserved for future use. Line 4b counts the Forms 5471 attached. Question 5 asks about a distribution from, or being the grantor of or transferor to, a foreign trust.
Whether the corporation had an interest in or a signature or other authority over a financial account in a foreign country during the 2025 calendar year, and the name of the country.
Whether the corporation claims the extraterritorial income exclusion, the number of Forms 8873 and their line 52 total, and whether it was a specified domestic entity required to file Form 8938.
Enter the corporation's name and employer identification number at the top, then answer each question with Yes, No or a count.
The instructions say to check Yes on 1a if the corporation is the tax owner of an FDE or FB, or files Form 5471 or Form 8865 for a controlled foreign corporation or partnership that is. They describe an exception and a statement in lieu of Form 8858 listing each FDE or FB's name, country and EIN. For 1c, they say that for tax years 2025 and 2026 the count covers Forms 8964-TRA attached to the entire return.
For a 10% or greater interest in a foreign partnership with no Form 8865 attached, the instructions say to attach a statement with the partnership's name and EIN, which of Forms 1042, 1065 or 8804 it filed, its partnership representative, and its tax year dates.
The instructions say the corporation may be required to file Form 3520 if it transferred money or property to a foreign trust, is treated as an owner of trust assets under the grantor trust rules, or received a distribution from a foreign trust.
The instructions say to check Yes if the corporation had a foreign account interest or authority with a combined value of more than $10,000 at any time during the calendar year, not at a U.S. military banking facility, or if it owns more than 50% of the stock in a corporation that would answer Yes. Enter the country or countries.
For 7a, the form says to attach a separate Form 8873 for each transaction or group of transactions, then enter their count and line 52 total. For 8, the instructions point to the Instructions for Form 8938 for the definition of a specified domestic entity.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1120, 1120-C, 1120-IC-DISC, 1120-L, 1120-PC, 1120-REIT, 1120-RIC, or 1120-S.
The questions refer to Forms 8858, 8964-TRA, 8865, 5471, 3520, 8873 and 8938. The instructions on page 2 explain when each one applies.
The instructions say FinCEN Form 114 is filed electronically with the Department of the Treasury using FinCEN's BSA e-Filing System, and because it is not a tax form, it is not filed with the return.
The instructions say an owner of a foreign trust ensures that the trust files an annual information return on Form 3520-A.

1120
481 fields, 6 pages
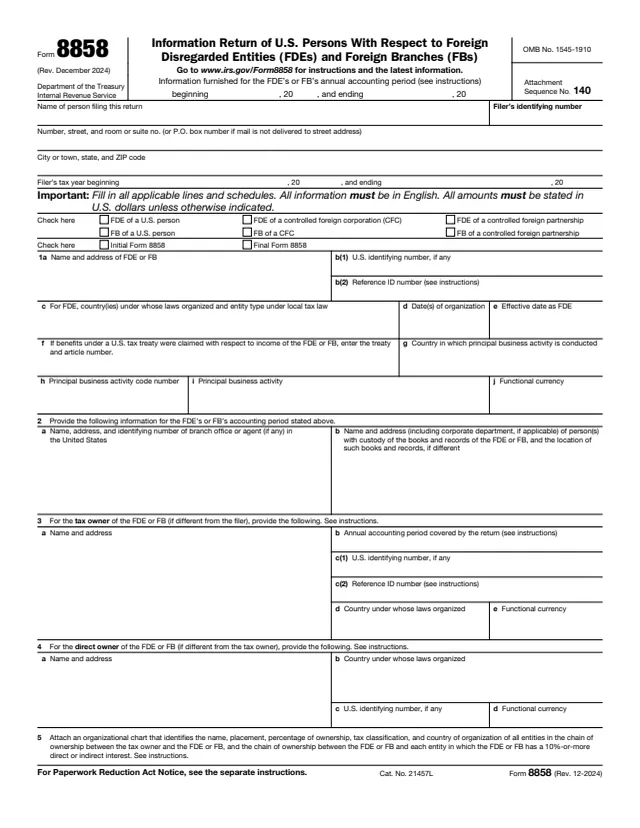
8858
190 fields, 4 pages
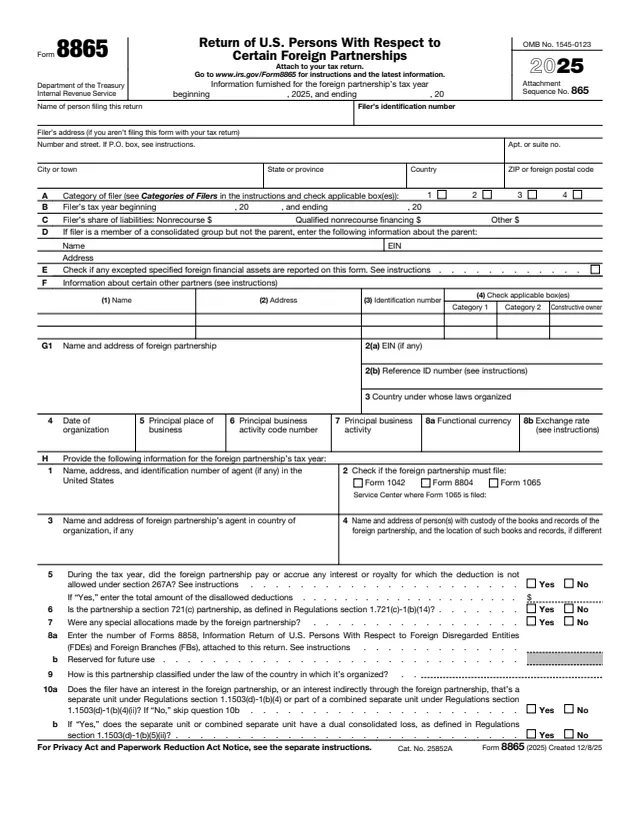
8865
461 fields, 6 pages

5471
437 fields, 6 pages
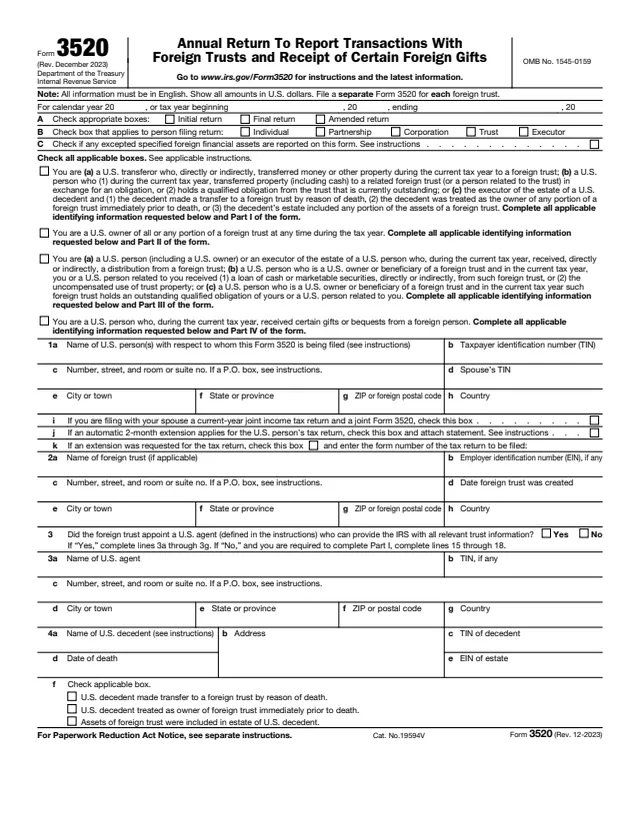
3520
462 fields, 6 pages
8938
131 fields, 2 pages
Schedule N is completed by a corporation and attached to its corporate income tax return. It is not a form individuals file.
No tool matches that search.
No. The form says to attach it to Form 1120, 1120-C, 1120-IC-DISC, 1120-L, 1120-PC, 1120-REIT, 1120-RIC, or 1120-S.
The instructions say a corporation that answers "Yes" to any question on page 1 attaches Schedule N and the applicable forms and schedules to its return.
No. The instructions say FinCEN Form 114 is filed electronically through FinCEN's BSA e-Filing System and is not filed with the return, because it is not a tax form.
The instructions define it as the person treated as owning the assets and liabilities of the foreign disregarded entity or foreign branch for purposes of U.S. income tax law.
Nothing. The 2025 form marks line 4a as reserved for future use. Line 4b asks for the number of Forms 5471 attached.
This page hosts the 2025 Schedule N (Form 1120). The PDF says to go to www.irs.gov/Form1120 for the latest information.