Header and amended report box
The name of the taxpayer or REIT, the identifying number, the taxable year of reporting, and a box to check if this is an amended report.
965-B
Corporate and Real Estate Investment Trust (REIT) Report of Net 965 Tax Liability and Electing REIT Report of 965 Amounts
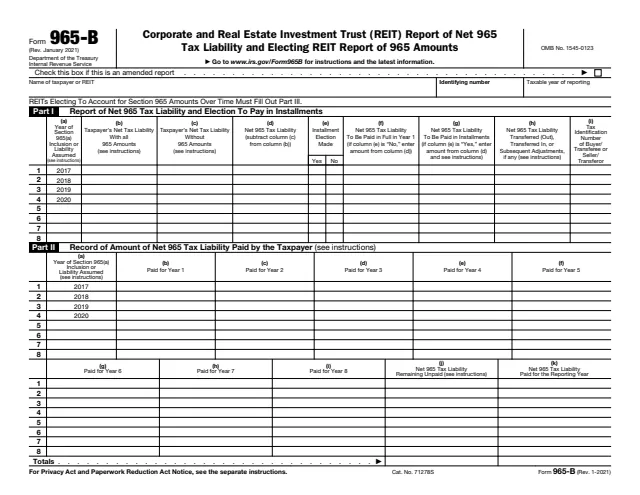
Form 965-B, Corporate and Real Estate Investment Trust (REIT) Report of Net 965 Tax Liability and Electing REIT Report of 965 Amounts, is used by corporate taxpayers and REITs. The IRS page says it reports a taxpayer's net 965 tax liability for each tax year in which a taxpayer accounts for section 965 amounts.
The instructions call it a cumulative report: it shows how the net 965 tax liability was figured, whether it is paid in installments, each payment made, and any transfers or adjustments, until the liability is paid in full. An electing REIT also uses Part III to track the section 965 amounts it takes into account over an 8-year period.
Form 965-B is filed with the taxpayer's income tax return, not on its own. Individuals have a separate report, Form 965-A. You can fill out Form 965-B free in your browser on this page and download it without an account.
The name of the taxpayer or REIT, the identifying number, the taxable year of reporting, and a box to check if this is an amended report.
The year of the section 965(a) inclusion or liability assumed, net tax liability with all 965 amounts, net tax liability without 965 amounts, and the difference, which is the net 965 tax liability.
Whether an installment election was made, the amount paid in full in year 1 or paid in installments, amounts transferred out, transferred in or adjusted, and the other party's identification number.
A record of the net 965 tax liability paid by the taxpayer: Paid for Year 1 through Paid for Year 8, the amount remaining unpaid, the amount paid for the reporting year, and totals.
Lines 1a through 4b for the 2017 to 2020 section 965(a) inclusion and section 965(c) deduction, with the amount elected, the portion for each of years 1 through 8, the amount remaining and this year's portion.
Open lines in Parts I and II for other amounts of net 965 tax liability, such as installment liabilities transferred in. The form says to attach additional sheets if more lines are needed.
The instructions say to check it when Form 965-B is filed with an amended return that changes section 965 reporting, and on any amended Form 965-B filed with Form 1139 for an NOL carryback.
Column (b) is net income tax liability with all section 965 amounts included, column (c) is the same liability without section 965, and column (d) is the excess of (b) over (c).
Check Yes if an election under section 965(h) to pay in installments over 8 years was made, then enter the column (d) amount in column (g). If No, enter it in column (f) instead.
A liability transferred out goes in column (h) as a negative number, a liability transferred in as a positive number on lines 5 to 8, and later adjustments such as audit changes as positive or negative. Column (i) holds the other party's identification number.
The instructions give the general installment schedule: 8% in each of years 1 to 5, 15% in year 6, 20% in year 7 and 25% in year 8. Actual payments are reported, column (j) shows what is left unpaid and column (k) only this year's payment.
Column (b) is the amount the election covers, columns (c) to (j) the portion taken into account each year on the same 8-year schedule, column (k) the amount remaining and column (l) this year's portion.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 965-B with the taxpayer's income tax return for the reporting year. If that return is filed electronically, Form 965-B is filed with it.
It is due with the income tax return, by the return's due date including any extensions. The instructions add that the first installment payment is due by the return's due date without extension.
The instructions say the form is completed for every tax year in which any net 965 tax liability is outstanding and not fully paid at any point in the year, and for every year an electing REIT still has amounts to take into account.
The form says to attach additional sheets if more lines are needed. The instructions say an additional Form 965-B is used if lines 5 through 8 are not enough.
For tax year 2020, the instructions say corporations carry Part I, column (d), line 4 and Part II, column (k), line 4 to Form 1120, Schedule J, or the matching line of other corporate returns.
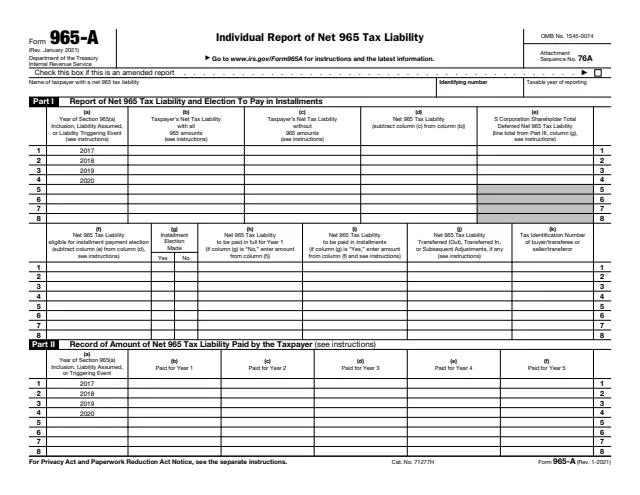
965-A
413 fields, 3 pages
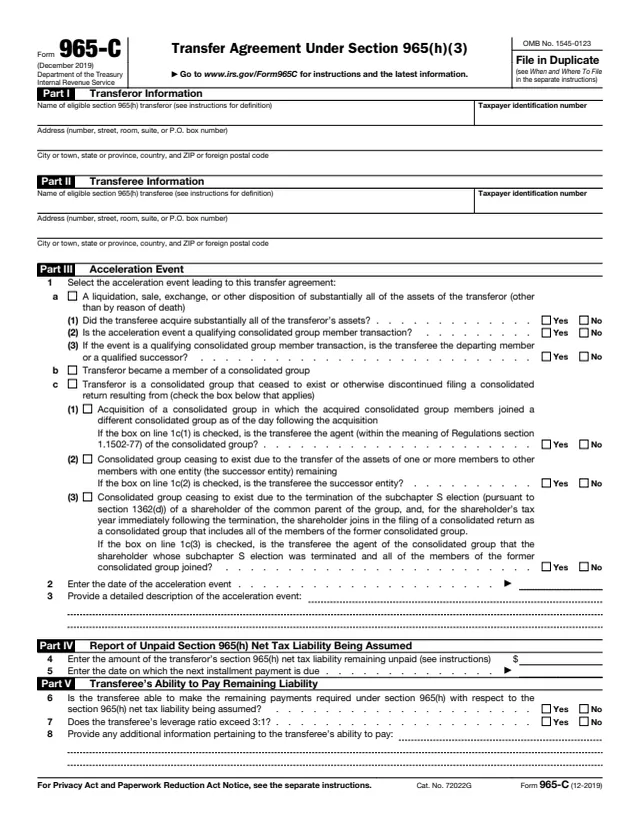
965-C
49 fields, 2 pages
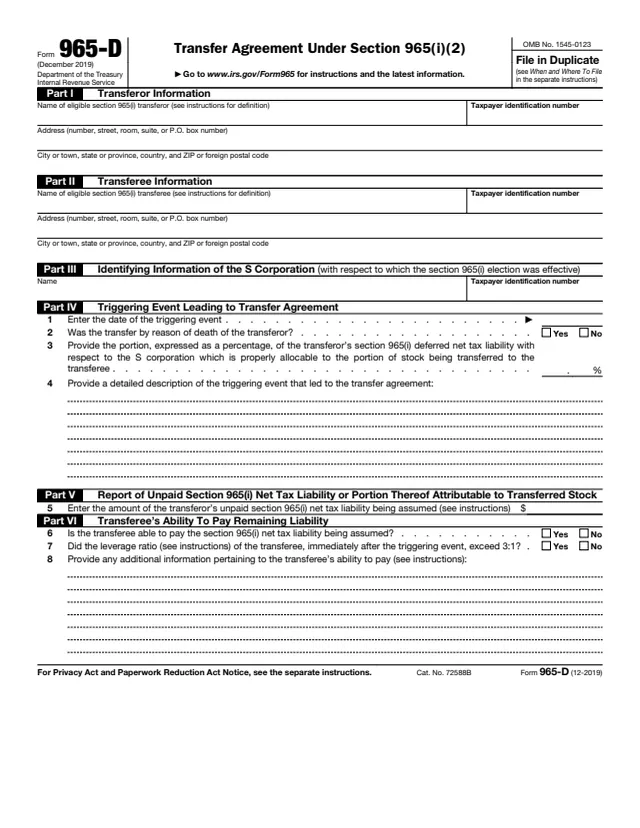
965-D
44 fields, 2 pages
965-E
33 fields, 2 pages
1139
162 fields, 2 pages

1120
481 fields, 6 pages
The instructions say the form should be used by corporate taxpayers and REITs. It is completed by the corporation or REIT and goes to the IRS with its income tax return.
No tool matches that search.
The instructions say corporate taxpayers and REITs. Individuals have a separate form, Form 965-A.
No. It is filed with the taxpayer's income tax return for the reporting year, by that return's due date including extensions.
The instructions define it as the excess of net income tax liability figured with all section 965 amounts over net income tax liability figured without section 965.
The instructions list 8% of the net 965 tax liability in each of years 1 through 5, 15% in year 6, 20% in year 7 and 25% in year 8. Actual payments are reported if they differ.
A REIT that elected to account for its section 965 amounts over time completes Part III. The form says such REITs fill out Part III.
When the form goes with an amended return that changes section 965 reporting, and on an amended Form 965-B filed with Form 1139 after an NOL carryback to a section 965 year.