Part I: liability and installment election
Year by year: net tax liability with and without 965 amounts, net 965 tax liability, S corporation deferrals, the installment election, transfers and adjustments, and a transferee or transferor TIN.
965-A
Individual Report of Net 965 Tax Liability
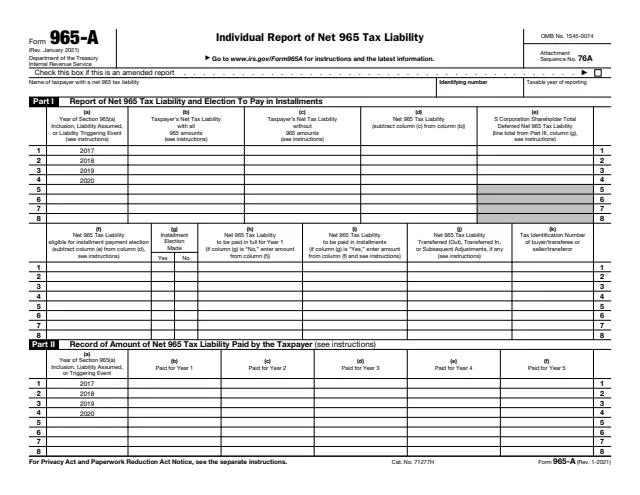
Form 965-A, Individual Report of Net 965 Tax Liability, is filed with an income tax return. The IRS About page says it is used by individual taxpayers and entities taxed like individuals to report a taxpayer's net 965 tax liability for each tax year in which section 965 amounts are accounted for.
The instructions explain that section 965 was amended on December 22, 2017, so certain taxpayers include in income an amount based on the accumulated post-1986 deferred foreign income of certain foreign corporations. The net 965 tax liability is the excess of the net income tax liability with all section 965 amounts over the liability without them.
The instructions call the form a cumulative report of a taxpayer's net 965 tax liabilities through payment in full. It records the liability, any election to pay over 8 years, the payments made each year, transfers and adjustments, and S corporation shareholder deferrals. You can fill out Form 965-A free in your browser on this page and download it without an account.
Year by year: net tax liability with and without 965 amounts, net 965 tax liability, S corporation deferrals, the installment election, transfers and adjustments, and a transferee or transferor TIN.
A cumulative record of what was paid for Year 1 through Year 8, the amount still unpaid in column (j) and the payment for the reporting year in column (k).
For each S corporation: its name and EIN, tax with only its 965 amounts, tax without 965 amounts, the related net 965 tax liability and the deferral election.
Deferred S corporation-related liabilities, required every year until fully paid: beginning balance, amounts triggered, transfers out or in, and the end-of-year balance.
Enter the taxpayer's name, identifying number and taxable year of reporting. Check the amended report box when the form goes with an amended return that changes section 965 reporting.
Enter tax with all 965 amounts in (b) and without them in (c). Column (d) is (b) minus (c). Subtract any S corporation deferral in (e) to get the amount in (f).
Check Yes in (g) if the 8-year installment election was made and carry (f) to (i), otherwise check No and carry it to (h). Report transfers and adjustments in (j) and a TIN in (k).
Record actual payments in the year columns. The instructions list the general schedule as 8% in each of years 1 to 5, 15% in year 6, 20% in year 7 and 25% in year 8.
S corporation shareholders figure the liability for each S corporation in Part III, total any deferrals into Part I, column (e), and report deferred balances in Part IV each year.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 965-A with the taxpayer's income tax return for the reporting year by the due date, taking into account extensions, if any.
The instructions say that if the income tax return is filed electronically, Form 965-A is filed with the electronic income tax return.
The instructions say the form is completed for every tax year with any net 965 tax liability outstanding and not fully paid at any point, including deferred S corporation-related liabilities.
The instructions say that if required section 965(i)(7) information is not reported by the return due date, 5% of the deferred net 965 tax liability is assessed as an addition to tax.
The form says to attach additional sheets if more lines are needed for any part. The instructions say to use an additional Form 965-A when Part I, lines 5 to 8, run out.
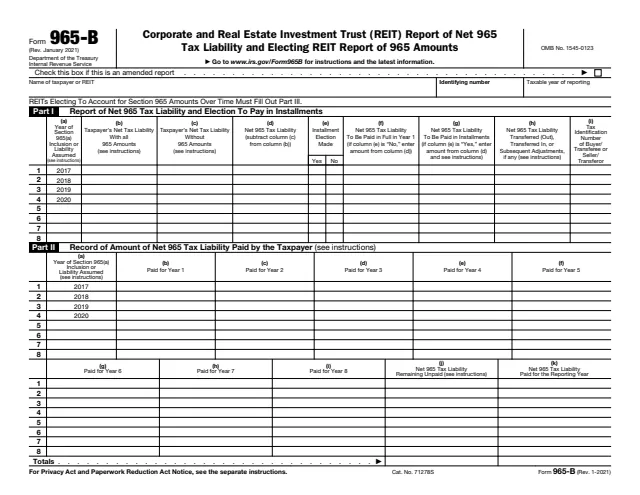
965-B
272 fields, 2 pages
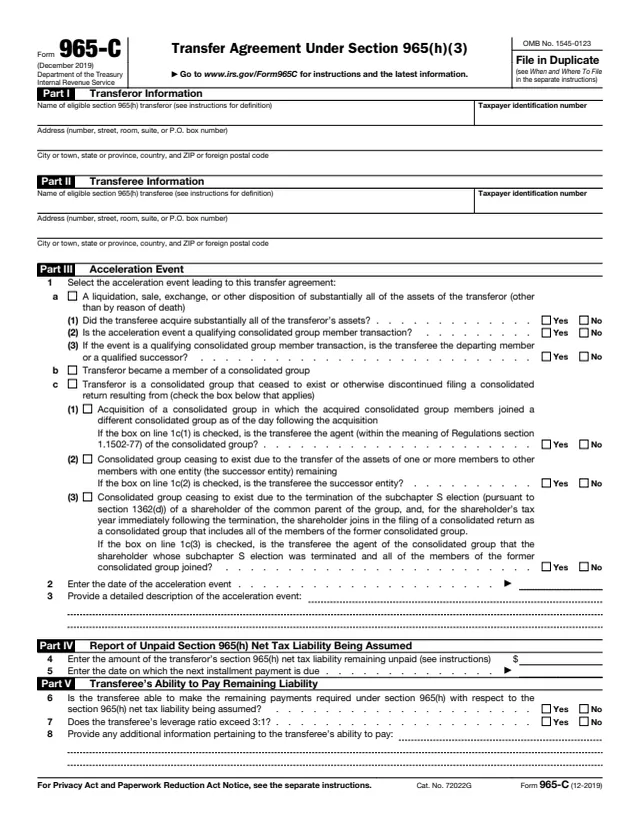
965-C
49 fields, 2 pages
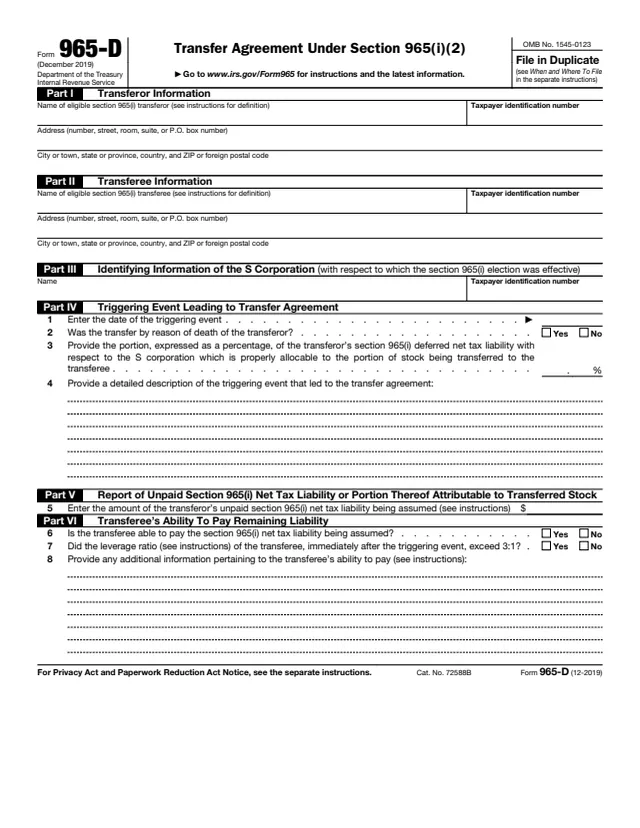
965-D
44 fields, 2 pages
965-E
33 fields, 2 pages
1045
193 fields, 2 pages
1040
63 fields, 2 pages
The instructions say Form 965-A is filed by any individual taxpayer, or taxpayer taxed like an individual, who has a net 965 tax liability for any tax year or has any net 965 tax liability remaining unpaid at any time during a tax year.
No tool matches that search.
The instructions define it as the excess of the taxpayer's net income tax liability computed with all section 965 amounts over the net income tax liability without regard to section 965.
No. The instructions call it a cumulative report through payment in full, completed for every tax year with any net 965 tax liability outstanding at any point during the year.
The instructions say the taxpayer still completes the appropriate line in Part I and reports the payment on the corresponding line in Part II, column (b).
The instructions say the first installment is due no later than the due date of the return for the tax year without extension, even if the election is made on a return filed by the extended due date.
The instructions say that for tax year 2020, individuals enter the amount from Part II, column (k), line 4, on Schedule 2 (Form 1040), line 9. Other filers follow their own return's instructions.
The instructions say a taxpayer applying for a tentative refund from carrying an NOL back to a section 965 year includes an amended Form 965-A and a statement of explanation with Form 1045.