Parts I and II: transferor and transferee
Name, taxpayer identification number and address of each side.
965-D
Transfer Agreement Under Section 965(i)(2)
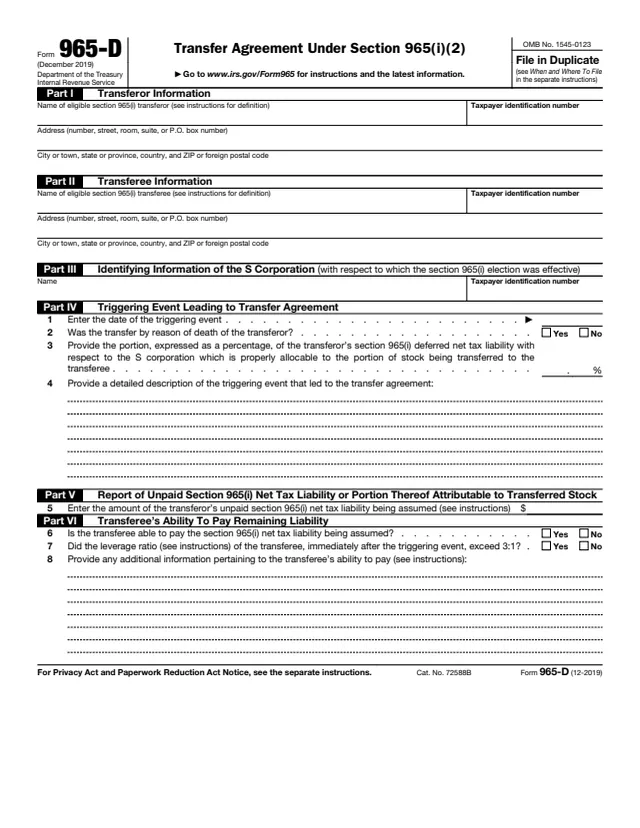
Form 965-D, Transfer Agreement Under Section 965(i)(2), is used by an eligible section 965(i) transferor and an eligible section 965(i) transferee to enter into a transfer agreement under section 965(i)(2). The instructions explain the background: an S corporation shareholder may elect to defer payment of a section 965(i) net tax liability until a triggering event occurs, and a covered triggering event does not trigger the liability if the transferee agrees to be liable for it in the same manner as if the transferee were the original electing taxpayer.
The two-page form identifies the transferor, the transferee and the S corporation, describes the triggering event, reports the unpaid liability being assumed, and asks about the transferee's ability to pay. Part VII sets out the terms both sides agree to, and each side signs. The form is marked File in Duplicate.
You can fill out Form 965-D free in your browser on this page and download it without an account.
Name, taxpayer identification number and address of each side.
Name and TIN of the S corporation with respect to which the section 965(i) election was effective.
Line 1 is the date, line 2 asks whether the transfer was by reason of the transferor's death, line 3 is the percentage of the deferred liability allocable to the transferred stock, and line 4 is a detailed description.
Line 5 is the dollar amount of the transferor's unpaid section 965(i) net tax liability being assumed.
Line 6 asks whether the transferee is able to pay, line 7 whether its leverage ratio exceeded 3:1 immediately after the triggering event, and line 8 takes other information.
The terms of the agreement, including that the transferor stays jointly and severally liable, then separate signature blocks for the transferor and the transferee.
Enter the transferor's complete legal name, TIN and street address or post office box, the transferee's name, TIN and address, and the S corporation's name and TIN.
Enter the date of the covered triggering event. Line 2 is Yes only if the event is the transferor's death. The instructions say a transfer from an estate to the beneficiaries is not that kind of event.
For a partial transfer, enter the percentage of the liability attributable to the transferred stock. For all of the stock, the instructions say to enter 100.00%. Then describe the event, such as a sale, gift or death.
Enter the dollar amount of the transferor's section 965(i) net tax liability being assumed by the transferee. The instructions note the Commissioner may adjust it.
The instructions say a No on line 6 means the requirements for a valid transfer agreement are not met. Line 7 uses the leverage ratio defined in the instructions. Line 8 may cover income, assets and access to capital.
Each side signs through a person authorized to sign a return for it. The transferor certifies Parts I, III, IV and V; the transferee certifies Parts II, III, IV, V and VI.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Except when the event is the transferor's death, the instructions say the original Form 965-D is mailed within 30 days of the covered triggering event. No extension of time to file is granted.
The instructions say the transfer agreement is filed by the unextended due date for the transferor's final income tax return.
The 2019 instructions print an address for Memphis CSCO. The About page lists a 2021 recent development, Change to the Mailing Address for Filing Forms 965-D and 965-E, so check that notice before mailing.
Both the transferor and the transferee attach a duplicate copy to their tax returns for the tax years during which the covered triggering event occurs, filed by the due date (with regard to any extension).
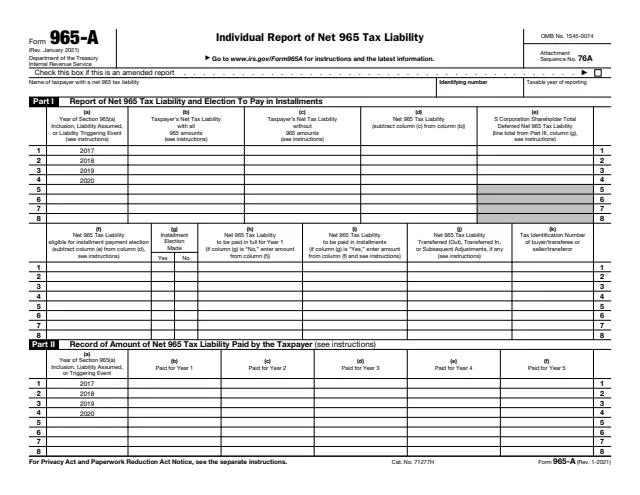
The instructions say a copy of the transferor's most recent Form 965-A is required to be included with Form 965-D.
The Commissioner may ask for more information and may reject the agreement for a material misrepresentation or omission, or if requested information is not provided in time.
965-A
413 fields, 3 pages
965-C
49 fields, 2 pages
965-E
33 fields, 2 pages
965-B
272 fields, 2 pages
The instructions say the form is filed by the eligible section 965(i) transferor and the eligible section 965(i) transferee for a covered triggering event, and may only be filed by them.
No tool matches that search.
Both sides. The transferor and the transferee each sign through a person authorized to sign a return on their behalf.
No. The instructions say an S corporation cannot file Form 965-D on behalf of its shareholders.
The instructions say within 30 days of the covered triggering event, except when the event is the transferor's death. Then it is the unextended due date for the transferor's final income tax return.
The instructions say no extension of time to file is granted, and relief under Regulations section 301.9100-2 or 301.9100-3 is not available to enter into a transfer agreement late.
Part VII says the transferor and any successor remain jointly and severally liable for the section 965(i) net tax liability being assumed by the transferee.
The instructions say the ratio is a factor in judging ability to pay, and a ratio in excess of three to one does not by itself determine whether a transfer agreement is valid.