Part I: shareholder information
Name of shareholder, taxpayer identification number, and address with city, state or province, country and ZIP or foreign postal code.
965-E
Consent Agreement Under Section 965(i)(4)(D)
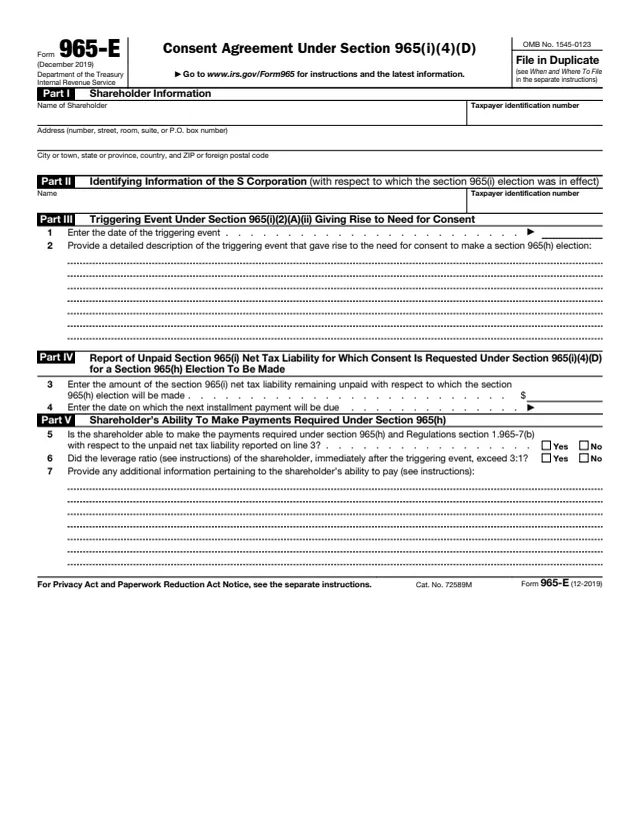
Form 965-E, Consent Agreement Under Section 965(i)(4)(D), is filed by a shareholder in an S corporation. The instructions say it is used by a shareholder who has an outstanding section 965(i) net tax liability with respect to which a section 965(i)(2)(A)(ii) triggering event has occurred, to obtain consent to make a section 965(h) election.
A section 965(i) election lets an S corporation shareholder defer payment of the section 965(i) net tax liability until a triggering event. The instructions define that triggering event as the liquidation, sale, exchange or other disposition of substantially all of the assets of the S corporation, the cessation of its business, or the S corporation ceasing to exist. A section 965(h) election pays the liability in installments over 8 years.
The instructions say Form 965-E is only the consent agreement; the section 965(h) election itself is made separately. You can fill out Form 965-E free in your browser on this page and download the result without an account.
Name of shareholder, taxpayer identification number, and address with city, state or province, country and ZIP or foreign postal code.
Name and taxpayer identification number of the S corporation with respect to which the section 965(i) election was in effect.
Line 1 asks for the date of the triggering event and line 2 for a detailed description of the event that gave rise to the need for consent.
Line 3 is the amount of section 965(i) net tax liability remaining unpaid for which the section 965(h) election will be made. Line 4 is the date the next installment payment will be due.
Lines 5 and 6 are yes or no questions on the shareholder's ability to make the section 965(h) payments and whether its leverage ratio exceeded 3:1. Line 7 is for additional information.
The terms of agreement, followed by the shareholder's signature, date, printed name and title, email address and daytime phone.
Enter the shareholder's complete legal name, taxpayer identification number and street address or post office box, then the name and taxpayer identification number of the S corporation.
Enter the date the triggering event occurred and describe it in detail. For a disposition of substantially all of the assets, the instructions say to describe the type of disposition, including any steps in the transaction.
Enter the dollar amount of the outstanding section 965(i) net tax liability for the election, and the date the first installment payment will be due after the section 965(h) election is made. The instructions note the Commissioner may adjust the amount.
The instructions say checking No on line 5 means the requirements for a valid consent agreement are not met. Line 6 asks whether the leverage ratio exceeded three to one. Line 7 can cover income, assets and access to capital.
The shareholder or a person authorized to sign for the shareholder signs under penalties of perjury and certifies the authority to execute the agreement.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to mail the original to Memphis CSCO, 5333 Getwell Road MS 81, Memphis, TN 38118. The About page also lists a 2021 notice titled Change to the Mailing Address for Filing Forms 965-D and 965-E.
The instructions say the original is mailed within 30 days of the triggering event, and that no extension of time to file Form 965-E will be granted.
The form says "File in Duplicate." The instructions say a duplicate copy is attached to the shareholder's tax return for the year the triggering event occurs, filed by its due date including extensions.
The instructions say Form 965-E does not include the section 965(h) election. If that election is not properly made, the full liability is payable for the year of the triggering event.
The instructions say the Commissioner may ask for more information and may reject the agreement for a material misrepresentation or omission, making the entire liability due for the year of the triggering event.
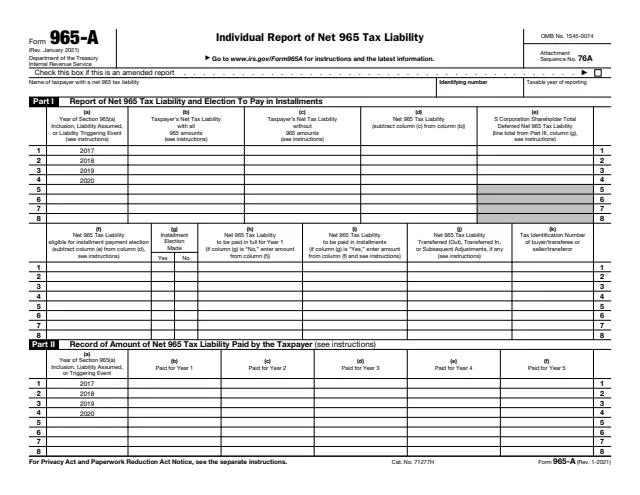
965-A
413 fields, 3 pages
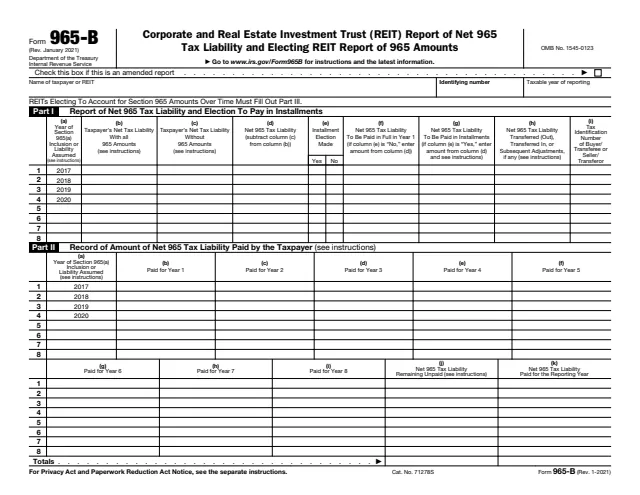
965-B
272 fields, 2 pages
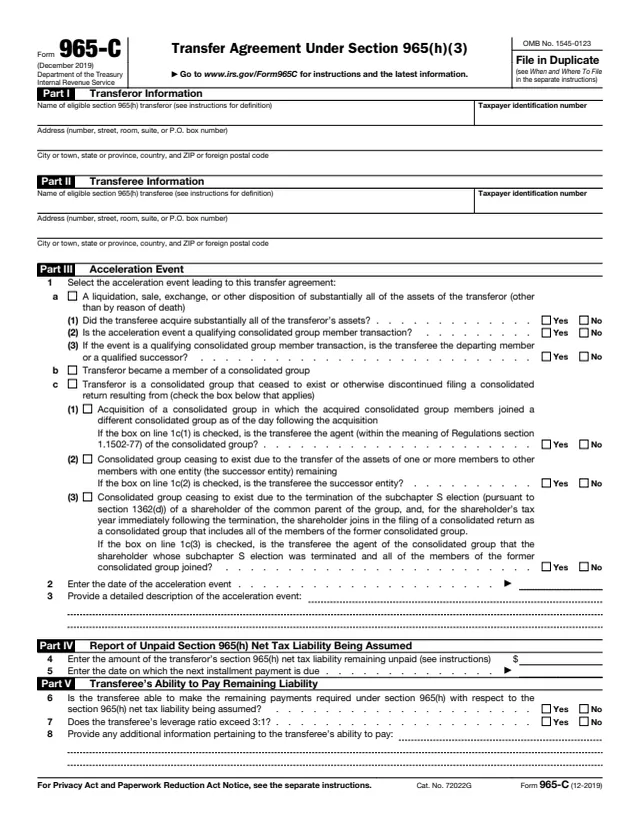
965-C
49 fields, 2 pages
965-D
44 fields, 2 pages

1120-S
390 fields, 5 pages
The instructions say an S corporation shareholder with an outstanding section 965(i) net tax liability, with respect to which a section 965(i)(2)(A)(ii) triggering event has occurred, files Form 965-E to obtain consent to make a section 965(h) election.
No tool matches that search.
The instructions say an S corporation shareholder uses it to obtain consent to make a section 965(h) election after a section 965(i)(2)(A)(ii) triggering event.
No. The instructions say an S corporation cannot file Form 965-E or make section 965(h) elections on behalf of its shareholders.
The instructions say within 30 days of the triggering event, with no extension of time to file.
No. The instructions say it is only the consent agreement, and the section 965(h) election is made separately.
The instructions define it as the ratio of the shareholder's total indebtedness to the sum of its money and all other assets, reduced but not below zero by the total indebtedness.
The original is mailed to the IRS and a duplicate copy is attached to the shareholder's tax return for the year of the triggering event.