Corporation information
Name, employer identification number, address, date of incorporation and a daytime phone number.
1139
Corporation Application for Tentative Refund
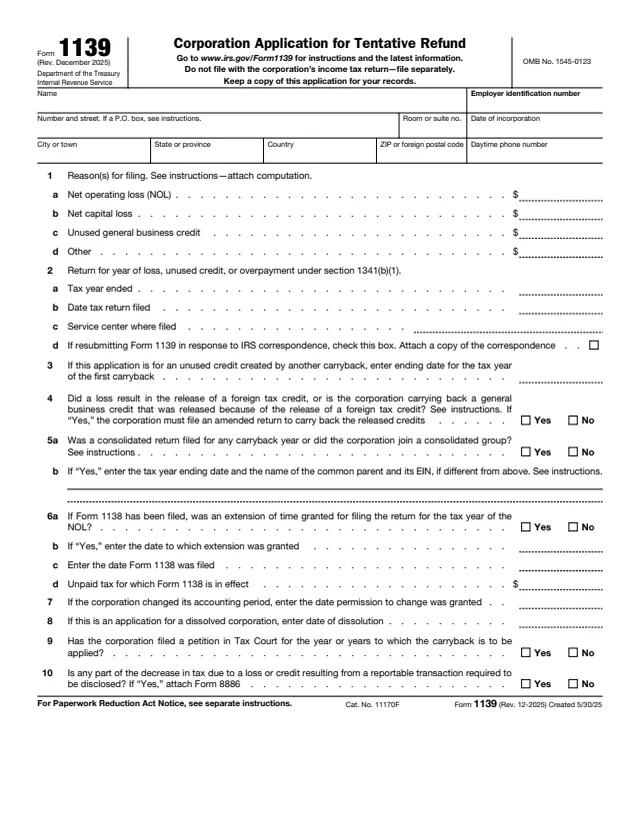
Form 1139, Corporation Application for Tentative Refund, is used by corporations other than S corporations. The IRS About Form 1139 page says it applies for a quick refund of taxes from the carryback of a net operating loss (or a loss from operations of a life insurance company), the carryback of a net capital loss, the carryback of an unused general business credit, or an overpayment of tax from a claim of right adjustment under section 1341(b)(1).
Page 1 gives the reason for filing and facts about the loss year. Page 2 computes the decrease in tax for up to three carryback years, before and after the carryback, and is signed by an officer of the corporation. The form says it is filed separately, not with the corporation's income tax return.
You can fill out Form 1139 free in your browser on this page and download it without an account.
Name, employer identification number, address, date of incorporation and a daytime phone number.
Amounts for a net operating loss, net capital loss, unused general business credit or other, and the tax year, filing date and service center of the loss year return.
Questions on released foreign tax credits, consolidated returns, Form 1138, accounting period changes, dissolution, Tax Court petitions and reportable transactions.
Before and after carryback columns for up to three preceding tax years, from taxable income through total tax liability and the decrease in tax.
An overpayment under section 1341(b)(1), and the routing number, account type and account number for direct deposit of any refund.
The signature, date and title of an officer under penalties of perjury, and the Paid Preparer Use Only section.
The instructions say to include the room or suite number, use a P.O. box only if the Post Office does not deliver to the street address, and write C/O for mail received through a third party.
Enter the amount for each reason that applies and attach a computation. For line 1c, the instructions say to attach the credit form for the year the credit arose.
Give the loss year return details and answer each question. Line 10 asks about reportable transactions and, if Yes, says to attach Form 8886.
The instructions say to start with the earliest carryback year, enter the ordinal year and end date above each pair of columns, and enter original amounts in columns (a), (c) and (e).
Enter refigured amounts after the carryback in columns (b), (d) and (f), attaching a computation of the refigured tax and any forms used, then subtract to get the decrease in tax.
Complete line 30 for direct deposit of any refund from lines 28 and 29, then have an officer sign, date and enter a title.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 1139 with the Internal Revenue Service Center where the corporation files its income tax return, and not with the return itself.
The instructions say Form 1139 is generally filed within 12 months of the end of the tax year in which the loss, credit or claim of right adjustment arose, and the income tax return for that year is filed no later than Form 1139.
The instructions list the first two pages of the loss year return, the forms and schedules a carryback results from, any Forms 8886, election statements and refigured carryback year forms.
The instructions say the IRS will process the application within 90 days of the later of the date the complete application is filed or the last day of the month that includes the return's due date, including extensions.
The instructions say a tentative refund application is not treated as a claim for credit or refund, but the corporation can file a regular claim, such as Form 1120-X.
1120-X
70 fields, 2 pages

1120
481 fields, 6 pages
1138
26 fields, 2 pages

3800
1,921 fields, 9 pages
8886
98 fields, 2 pages
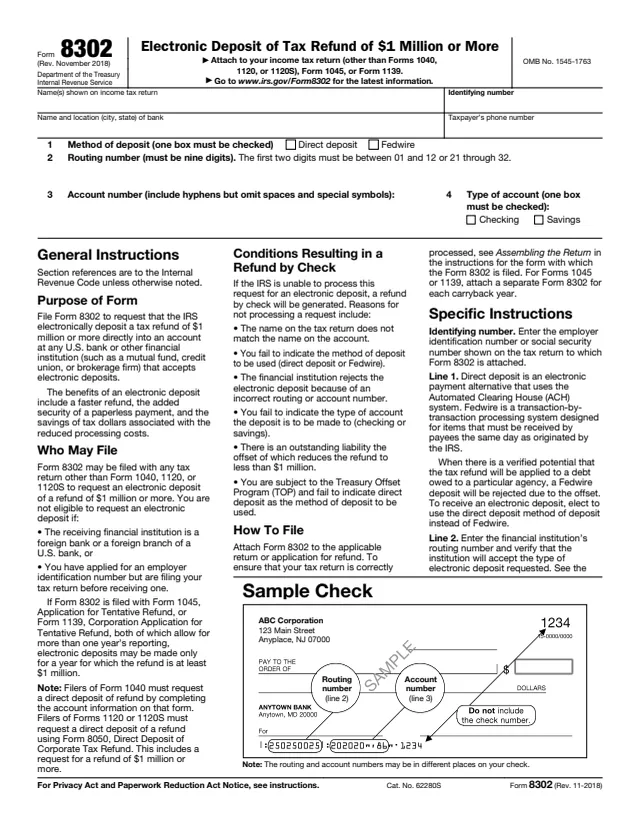
8302
10 fields, 2 pages
The form is filed by a corporation and signed by one of its officers. It is not an individual form.
No tool matches that search.
No. The About page and instructions say Form 1139 is for corporations other than S corporations.
The instructions say the IRS will process the application within 90 days of the later of the complete filing date or the last day of the month that includes the return's due date, including extensions.
The instructions say that for losses in tax years beginning after December 31, 2020, only farming losses and losses of insurance companies other than life insurance companies can be carried back, generally for 2 years.
The instructions say a corporation can get a refund with Form 1120-X instead, generally filed within 3 years after the loss year return was due, but the IRS is not required to process it within 90 days. Some carrybacks, such as a released foreign tax credit, use Form 1120-X.
No. The instructions say payment of the requested refund does not mean the IRS has accepted the application as correct, and interest is charged on amounts erroneously refunded.
The instructions say to attach Form 2848 to Form 1139 to designate an attorney or representative.