Header
The name of the U.S. parent corporation and its employer identification number.
8992 Sch. B
Calculation of Global Intangible Low‐Taxed Income (GILTI) for Members of a U.S. Consolidated Group Who Are U.S. Shareholders of a CFC
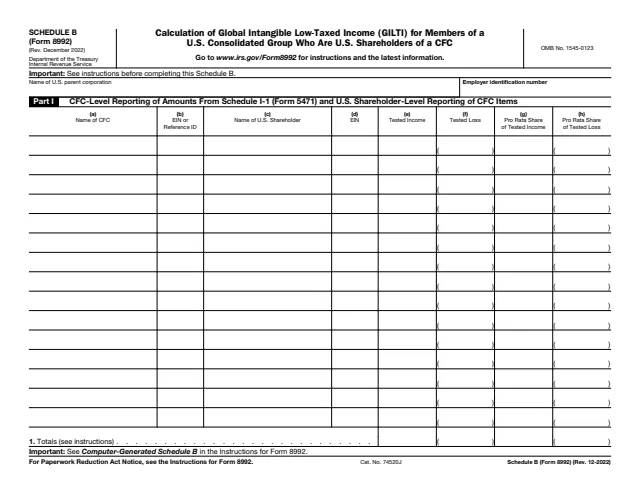
Schedule B (Form 8992), Calculation of Global Intangible Low-Taxed Income (GILTI) for Members of a U.S. Consolidated Group Who Are U.S. Shareholders of a CFC, is a four-page schedule. The Instructions for Form 8992 say it is used to report amounts used in determining the GILTI inclusion amount of each member of a U.S. consolidated group that is a U.S. shareholder of any controlled foreign corporation (CFC).
Part I reports amounts from Schedule I-1 (Form 5471) for each CFC owned by any member of the group, along with each member's pro rata shares. Part II holds the shareholder-level calculations that carry over to each member's Form 8992. The instructions say only one Schedule B is completed for the group, and a copy is provided to each member. Members that are not part of a consolidated group use Schedule A (Form 8992) instead.
This page hosts the December 2022 revision. You can fill out Schedule B free in your browser on this page and download it without an account.
The name of the U.S. parent corporation and its employer identification number.
Name and EIN or reference ID of each CFC, name and EIN of the U.S. shareholder, tested income, tested loss, and the shareholder's pro rata shares of each.
Pro rata share of QBAI, pro rata share of the tested loss QBAI amount, and tested interest expense and tested interest income with their pro rata shares.
Under the heading GILTI Allocated to Tested Income CFCs: the GILTI allocation ratio and the GILTI allocated to each tested income CFC.
U.S. Shareholder-Level Calculations: each shareholder's name and EIN, aggregate tested income, GILTI allocation ratio, aggregate tested loss and allocable share of consolidated tested loss.
Consolidated QBAI and its allocable share, deemed tangible income return (DTIR), consolidated tested interest expense and income, and consolidated specified interest expense with its allocable share.
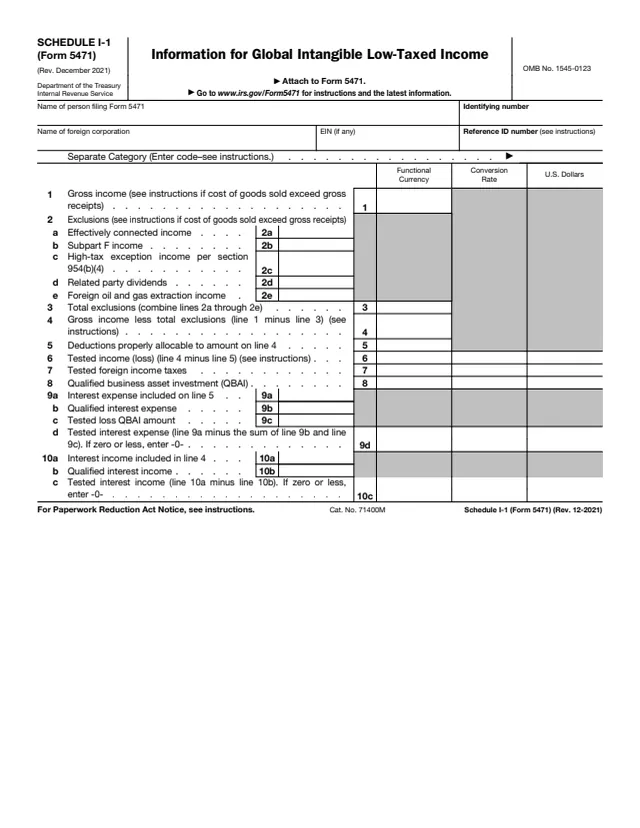
List each CFC with prior names from the past 3 years in parentheses, its EIN or a reference ID number, and the member that is its U.S. shareholder. Enter tested income or tested loss from line 6 of the CFC's Schedule I-1 (Form 5471) and the pro rata shares.
Enter totals on line 1. The instructions say that if the column (h) total equals or exceeds the column (g) total, the rest of Schedule B is not completed and the next step is the consolidated Form 8992.
If the column (g) total is larger, enter QBAI from Schedule I-1, line 8, the tested loss QBAI amount from line 9c, tested interest expense from line 9d and tested interest income from line 10c, with pro rata shares. Skip columns (o) and (p) for now.
Use one line per U.S. shareholder. Sum each shareholder's Part I amounts, then apply the column (d) GILTI allocation ratio. The instructions say column (i) is the column (h) amount multiplied by 10% (0.10).
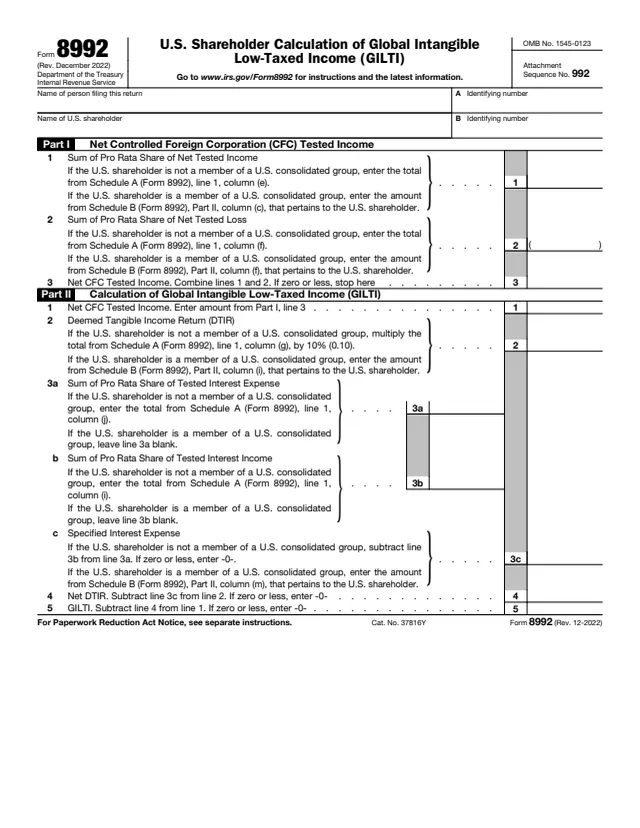
Complete a separate Form 8992 for each U.S. shareholder in Part II, then a consolidated Form 8992. The instructions say the member forms are kept for your records, not filed.
For tested income CFCs only, divide the column (g) amount by that shareholder's Part II, column (c) amount to four decimal places. Multiply by that shareholder's Form 8992, Part II, line 5 and enter whole dollars.
The instructions set out a fixed order of steps for Schedule B and Form 8992. The summary below follows that order.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Schedule B and one consolidated Form 8992 to the U.S. consolidated group's income tax return and file both by the due date (including extensions) for that return.
The Forms 8992 completed for each U.S. shareholder are not filed. The instructions say to keep them so they are available on request, for example in an examination.
The instructions say a computer-generated Schedule B can be filed if it conforms to the IRS version, and the schedule can be expanded when there are more CFCs or shareholders than lines.
The instructions say not to enter "APPLIED FOR" or "FOREIGNUS" in column (b), and the reference ID used for a CFC on Schedule B and on Form 5471 must be the same.
A corrected Form 8992 is filed with an amended return. The instructions say to write "Corrected" at the top and attach a statement identifying the changes.
The instructions say penalties under sections 6038(b) and (c) may apply for failure to report the information required.
8992
14 fields, 1 page
8992 Sch. A
268 fields, 2 pages
5471 Sch. I-1
35 fields, 1 page

5471
437 fields, 6 pages
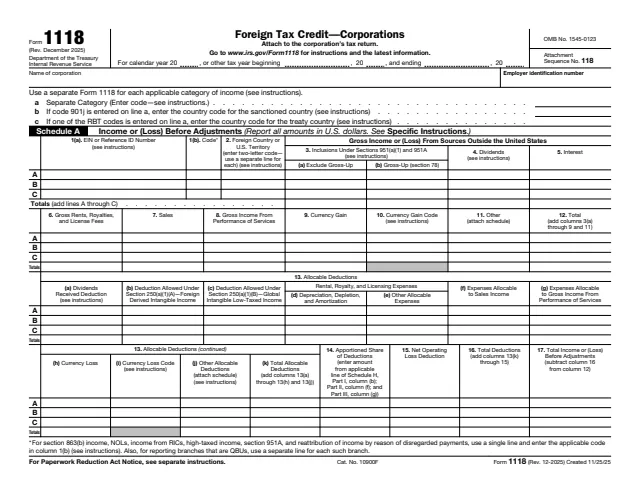
1118
1,263 fields, 12 pages
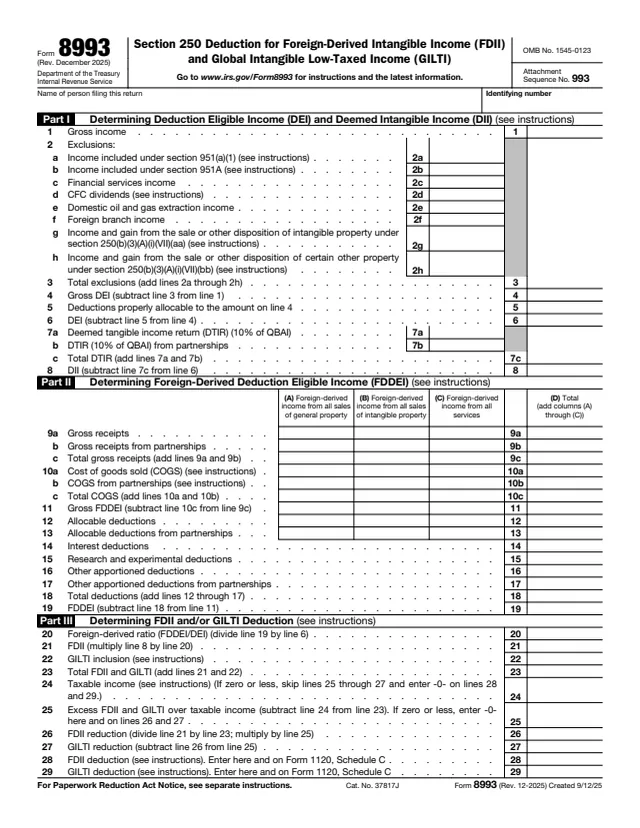
8993
71 fields, 1 page
The instructions say one Schedule B is completed for all members of a U.S. consolidated group that are U.S. shareholders of a CFC. It is filed with one consolidated Form 8992 and the group's income tax return.
No tool matches that search.
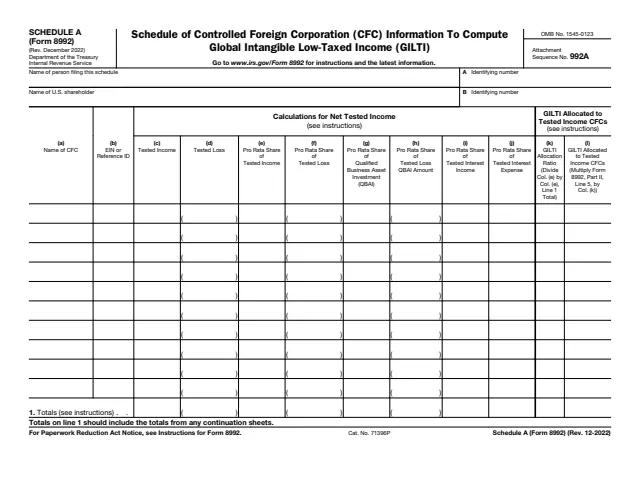
The instructions say Schedule A is generally completed with Form 8992, but a U.S. shareholder that is a member of a U.S. consolidated group completes Schedule B instead.
One. The instructions say to complete only one Schedule B for the group and provide a copy to each member.
Yes. If more than one member owns an interest in the same CFC, the instructions say to list it on a separate line for each member. Totals for columns (e), (f), (k) and (m) count each CFC only once.
The instructions say each shareholder enters its Part II, column (c) amount on Form 8992, Part I, line 1; column (f) on Part I, line 2; column (i) on Part II, line 2; and column (m) on Part II, line 3c.
The instructions say the Part II, column (d) ratio follows Regulations section 1.1502-51(e)(10) and differs from the Part I, column (o) ratio, which follows section 951A(f)(2).
No. If the line 1 total for column (h) equals or exceeds the total for column (g), the instructions say the remainder of Schedule B is not completed.