Part I: DEI and DII
Lines 1 to 8: gross income, exclusions, gross DEI, allocable deductions, DEI, deemed tangible income return (10% of QBAI) and DII.
8993
Section 250 Deduction for Foreign-Derived Intangible Income (FDII) and Global Intangible Low-Taxed Income (GILTI)
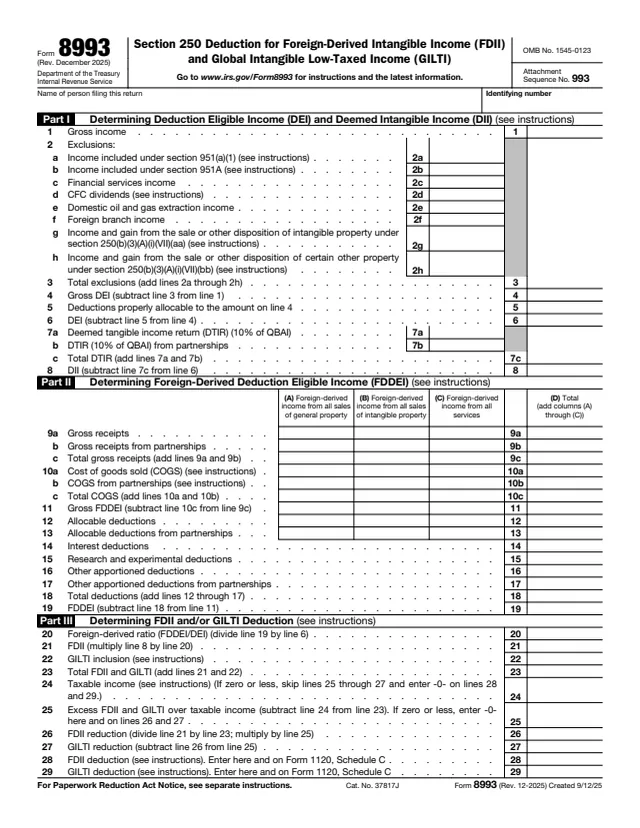
Form 8993 is used to figure the amount of the eligible deduction for foreign-derived intangible income (FDII) and global intangible low-taxed income (GILTI) under section 250. The About page says domestic corporations use it. The instructions add U.S. individual shareholders of controlled foreign corporations (CFCs) who make a section 962 election.
The form works in three parts. Part I finds deduction eligible income (DEI) and deemed intangible income (DII). Part II finds foreign-derived deduction eligible income (FDDEI) from sales of general property, sales of intangible property and services. Part III turns those into the FDII deduction and the GILTI deduction, with reductions when FDII and GILTI together exceed taxable income.
The instructions call this a continuous use revision for tax year 2025 and later years until a superseding revision is issued. You can fill out Form 8993 free in your browser on this page and download it without an account.
Lines 1 to 8: gross income, exclusions, gross DEI, allocable deductions, DEI, deemed tangible income return (10% of QBAI) and DII.
Section 951(a)(1) and 951A income, financial services income, CFC dividends, domestic oil and gas extraction income, foreign branch income, and gain from sales of intangible and certain other property.
Lines 9 to 19 in columns for general property, intangible property and services: gross receipts, cost of goods sold, allocable and apportioned deductions, and FDDEI.
Lines 20 to 27: foreign-derived ratio, FDII, GILTI inclusion, taxable income, and reductions when FDII and GILTI exceed taxable income.
The FDII deduction and the GILTI deduction, each entered here and on Form 1120, Schedule C.
Enter the name of the person filing the return and the identifying number.
Enter gross income from Form 1120, line 11, subtract the line 2 exclusions and allocable deductions to reach DEI, then subtract 10% of QBAI to reach DII. If DII is zero or less, the instructions say to enter zero on lines 8, 21 and 28.
Enter foreign-derived gross receipts, cost of goods sold and deductions in columns A to C, with partnership amounts on their own lines, then subtract to reach FDDEI on line 19.
Divide line 19 by line 6 for the foreign-derived ratio, which the instructions say may not exceed 1. Multiply line 8 by it for FDII, and enter GILTI from Form 8992, Part II, line 5.
Enter taxable income determined without regard to section 250. If FDII plus GILTI exceeds it, the Line 26 and Line 27 Worksheets in the instructions split the reduction between them.
The instructions say to multiply FDII less its reduction by 37.5% for line 28, and GILTI less its reduction, plus any section 78 dividend attributable to GILTI, by 50% for line 29.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8993 to the income tax return and file both by the due date (including extensions) for that return.
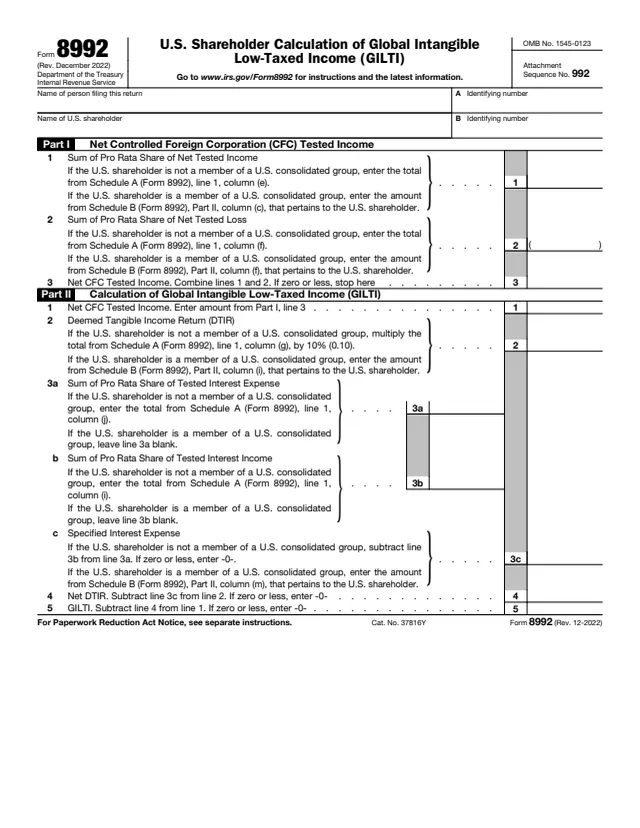
For the GILTI inclusion on line 22, the instructions say to attach Form 8992 to the income tax return.
Corporate partners attach a statement listing each partnership's name, EIN, the partner's share of QBAI on line 7b and other FDDEI items on lines 9b, 10b, 13 and 17.
The instructions say a corrected Form 8993 is filed with an amended tax return, with "Corrected" entered at the top.
For tax years beginning on or after January 1, 2018, and before January 1, 2026, the instructions say section 250 generally allows 37.5% of FDII plus 50% of GILTI, reduced after that to 33.34% and 40%.
Public Law 119-21 added an exclusion from DEI for income and gain from the sale or other disposition of intangible property and certain other property, for dispositions after June 16, 2025.
8992
14 fields, 1 page

1120
481 fields, 6 pages
1118
1,263 fields, 12 pages
1065
2,862 fields, 21 pages
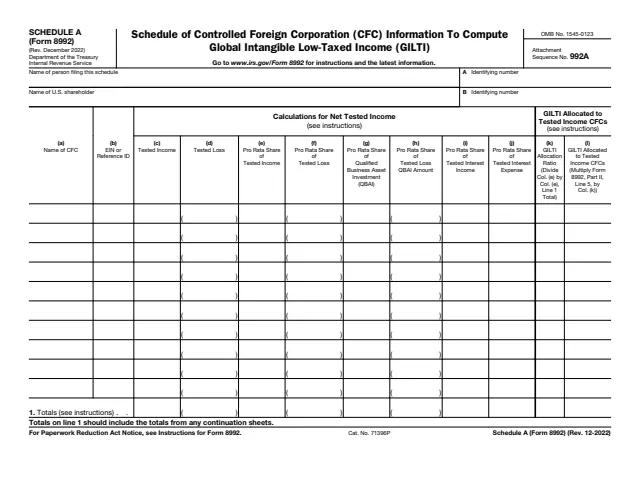
8992 Sch. A
268 fields, 2 pages
The instructions say all domestic corporations, and U.S. individual shareholders of CFCs making a section 962 election, use Form 8993 to determine the allowable deduction under section 250.
No tool matches that search.
Domestic corporations, and U.S. individual shareholders of CFCs making a section 962 election, according to the instructions. REITs, RICs and S corporations are not allowed the deduction.
Lines 28 and 29 say to enter the FDII deduction and the GILTI deduction on Form 1120, Schedule C.
The instructions say to enter the GILTI reported on Form 8992, Part II, line 5, and to attach Form 8992 to the income tax return.
The instructions say the section 250 deduction is then limited to taxable income, and lines 25 to 27 split the reduction between FDII and GILTI.
Qualified business asset investment. The instructions define it as the average of the corporation's adjusted bases, as of the close of each quarter, in specified tangible property used in its trade or business and of a type for which a deduction is allowable under section 167. Line 7a uses 10% of it.
The instructions say to use them for tax year 2025 and subsequent years until a superseding revision is issued.