Header
The name of the person filing the schedule with its identifying number in item A, and the name of the U.S. shareholder with its identifying number in item B.
8992 Sch. A
Schedule of Controlled Foreign Corporation (CFC) Information to Compute Global Intangible Low-Taxed Income (GILTI)
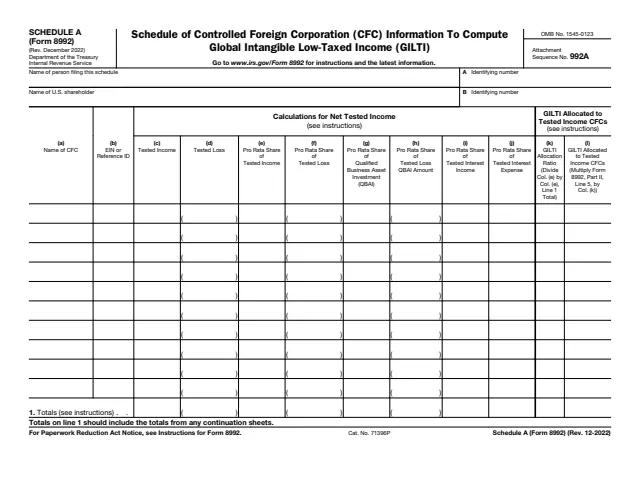
Schedule A (Form 8992), Schedule of Controlled Foreign Corporation (CFC) Information To Compute Global Intangible Low-Taxed Income (GILTI), is a two-page schedule with ten rows for CFCs on page 1 and a continuation sheet on page 2. The Instructions for Form 8992 say a U.S. shareholder that is not a member of a U.S. consolidated group files it to report its pro rata share of amounts for each CFC from that CFC's Schedule I-1 (Form 5471), to determine its GILTI inclusion amount, if any, and how much of that amount is allocated to each CFC.
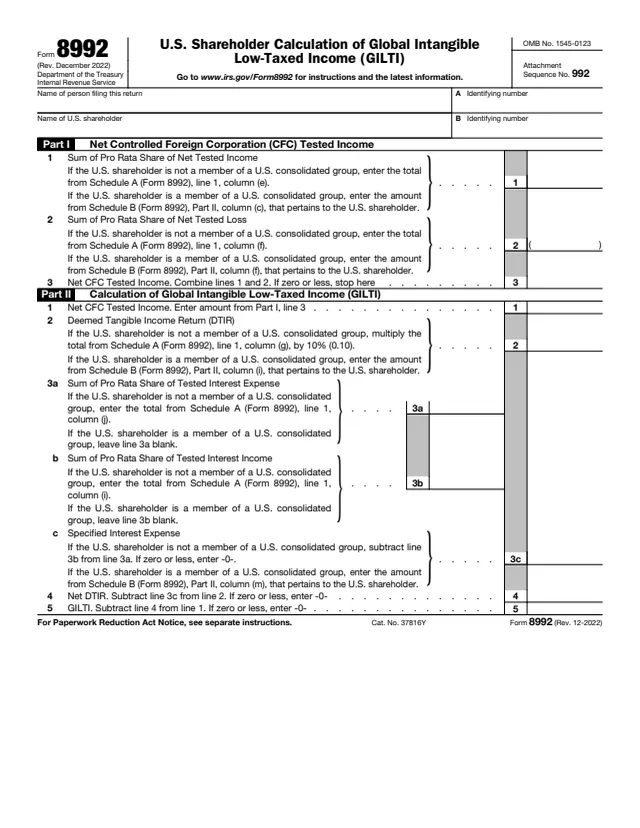
The instructions say Schedule A is generally completed and attached to Form 8992. A member of a U.S. consolidated group completes Schedule B (Form 8992) instead. Columns (a) through (f) feed Form 8992, Part I. Columns (g) through (l) are completed only when Form 8992, Part I, line 3 is greater than zero.
This page hosts the December 2022 revision, used with the Instructions for Form 8992. You can fill out Schedule A free in your browser on this page and download it without an account.
The name of the person filing the schedule with its identifying number in item A, and the name of the U.S. shareholder with its identifying number in item B.
The name of each CFC and its EIN or reference ID number.
Each CFC's tested income and tested loss, then the shareholder's pro rata share of each, under the heading Calculations for Net Tested Income.
Pro rata shares of qualified business asset investment (QBAI), the tested loss QBAI amount, tested interest income and tested interest expense.
Column (k) is the GILTI allocation ratio, column (e) divided by the column (e) total on line 1. Column (l) multiplies Form 8992, Part II, line 5 by column (k).
Line 1 holds the totals, including totals from any continuation sheets. Page 2 is the Schedule A Continuation Sheet, used only when more space is needed.
Enter the filer's name and identifying number in item A. The Form 8992 instructions say an individual's identifying number is the SSN and all others use the EIN. If the U.S. shareholder is a different person, enter its name and number in item B.
List each CFC, with any prior names from the past 3 years in parentheses. Enter the CFC's EIN, or a reference ID number if it has none. The instructions say not to enter "APPLIED FOR" or "FOREIGNUS" in column (b).
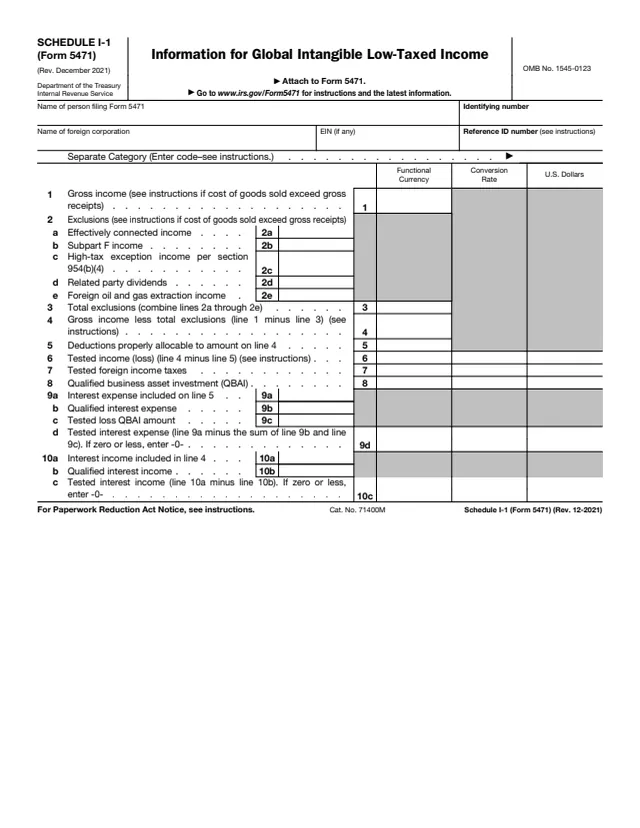
Enter the U.S. dollar amount of tested income or tested loss from line 6 of the CFC's Schedule I-1 (Form 5471), then the shareholder's pro rata share of each.
Enter the column totals on line 1 and complete Form 8992, Part I. The instructions say that if Part I, line 3 is zero or negative, columns (g) through (l) and Form 8992, Part II are not completed.
Enter pro rata shares of QBAI from Schedule I-1, line 8 for each tested income CFC, the tested loss QBAI amount from line 9c, tested interest income from line 10c and tested interest expense from line 9d.
After Form 8992, Parts I and II are done, divide each CFC's column (e) amount by the line 1, column (e) total, to four decimal places. Multiply that ratio by Form 8992, Part II, line 5 and enter whole dollars in column (l).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8992 and Schedule A to the income tax return, or exempt organization return, and file both by the due date (including extensions) for that return.
If more CFCs need listing, attach Schedule A Continuation Sheets. The instructions say not to write "See attached" on Schedule A and attach other sheets.
The instructions say the reference ID number used for a CFC on Schedule A and on Form 5471 must be the same.
The instructions say the column (l) amounts are used in completing Schedule J (Form 5471) and Schedule P (Form 5471) for each CFC.
A corrected Form 8992 is filed with an amended return. The instructions say to write "Corrected" at the top and attach a statement identifying the changes.
The instructions say penalties under sections 6038(b) and (c) may apply for failure to report the information required.
8992
14 fields, 1 page
8992 Sch. B
499 fields, 4 pages
5471 Sch. I-1
35 fields, 1 page

5471
437 fields, 6 pages
8993
71 fields, 1 page
5471 Sch. J
282 fields, 3 pages
The instructions say a U.S. shareholder that is not a member of a U.S. consolidated group files Schedule A with Form 8992. The schedule reports amounts for each CFC whose tax year ends with or within the shareholder's tax year.
No tool matches that search.
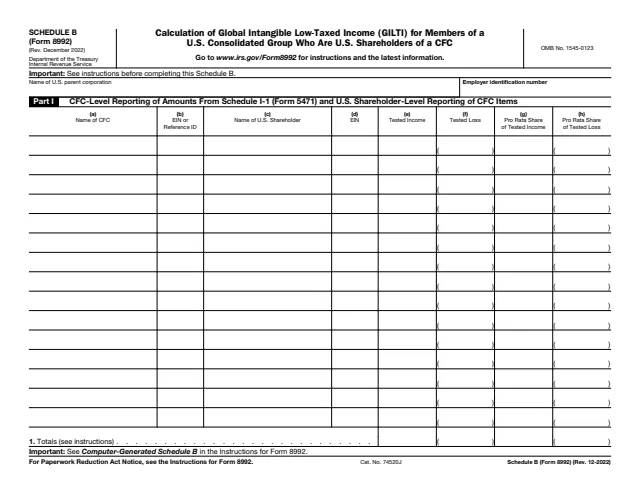
The instructions say a U.S. shareholder that is a member of a U.S. consolidated group completes Schedule B (Form 8992). Other U.S. shareholders generally use Schedule A.
From each CFC's Schedule I-1 (Form 5471), lines 6, 8, 9c, 9d and 10c. The instructions say a shareholder that does not file Schedule I-1 for a CFC still provides the amounts as if it had.
No. The instructions say they are completed only when Form 8992, Part I, line 3 is greater than zero.
Use the continuation sheet on page 2. The form says the line 1 totals on page 1 include the totals from any continuation sheets.
The instructions say domestic partnerships no longer complete Form 8992 or Schedule A. They complete Part VI of Schedules K-2 and K-3 (Form 1065) instead.