Part I, lines 1 to 4
Decedent's name and social security number, and the beneficiary's name and TIN.
8971 Sch. A
Beneficiary Information Regarding Property Acquired From a Decedent
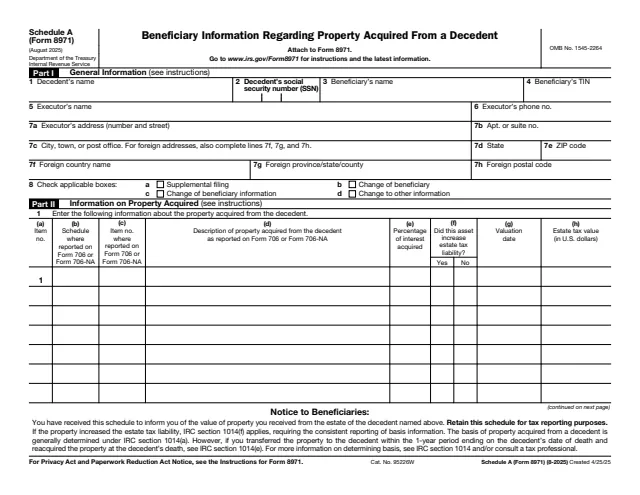
Schedule A (Form 8971) is titled Beneficiary Information Regarding Property Acquired From a Decedent. The IRS About page says it is used to report beneficiary-specific information regarding property acquired from a decedent and the corresponding estate tax values as reported on Form 706 or Form 706-NA. The instructions say Schedule A provides basis information to beneficiaries who acquire certain property from the decedent.
The executor completes it, not the beneficiary. The instructions say to furnish each Schedule A only to the beneficiary named on it, attach a copy of each one to Form 8971 filed with the IRS, and not give a copy of Form 8971 to any beneficiary. The About page says executors file Form 8971 if the estate tax return is filed after July 2015.
The schedule has Part I, General Information, and Part II, Information on Property Acquired, with a Notice to Beneficiaries on page 1. This page has the August 2025 edition. The PDF can be filled out free in the browser on this page and downloaded without an account.
Decedent's name and social security number, and the beneficiary's name and TIN.
Executor's name, phone number and address, with lines 7f to 7h for a foreign country, province and postal code.
Supplemental filing, change of beneficiary, change of beneficiary information, and change to other information.
Item number, the schedule and item number where the property was reported on Form 706 or Form 706-NA, and the description of the property as reported there.
Percentage of interest acquired, whether the asset increased estate tax liability (Yes or No), valuation date and estate tax value in U.S. dollars.
Totals of column (h), including totals from additional Parts II, and the Notice to Beneficiaries about consistent basis reporting under IRC section 1014(f).
The instructions say a copy of Form 706 or Form 706-NA is needed to complete this schedule, since the descriptions and values come from that return.
Enter the decedent's and beneficiary's names and numbers, and the executor's contact details. On line 8, check the first box only if this supplements an earlier Schedule A, then each box that gives the reason.
Number each property and use the same description, schedule and item number used on Form 706 or Form 706-NA. The instructions say to type information directly onto the schedule and not attach Form 706 schedules or property appraisals.
Enter the interest acquired when it is less than absolute ownership of 100%. Enter Y or N for each asset; the instructions say Y only if estate tax was generated and the asset contributed to it.
The valuation date is generally the date of death, or the alternate valuation date if the estate elected it. The instructions say column (h) shows the full fair market value, undiminished by debt.
Add column (h) on line 2, enter totals from extra Parts II on line 3 and add them on line 4. Duplicate page 2 for more entries; the instructions say not to complete lines 3 and 4 on a duplicate page 2.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to furnish each Schedule A only to the beneficiary named on it, in person, by email, or by U.S. mail or private delivery service to the beneficiary's last known address.
A copy of each Schedule A is attached to Form 8971, filed separately from other estate returns at Internal Revenue Service, Mail Stop 824G, 7940 Kentucky Drive, Florence, KY 41042.
The instructions say no later than the earlier of 30 days after Form 706 or Form 706-NA is required to be filed (including extensions) or 30 days after it is filed.
A change in value or beneficiary is reported on a supplemental Schedule A, generally 30 days after the information becomes available. Property acquired after the estate tax return's due date is reported by January 31 of the year after the beneficiary acquires it.
The instructions say an error in a dollar amount on Schedule A is de minimis if any single amount differs from the correct amount by not more than $100, unless the beneficiary elects to have that exception not apply.
The instructions say beneficiaries who report basis inconsistent with the amount on Schedule A may be liable for a 20% accuracy-related penalty under section 6662.
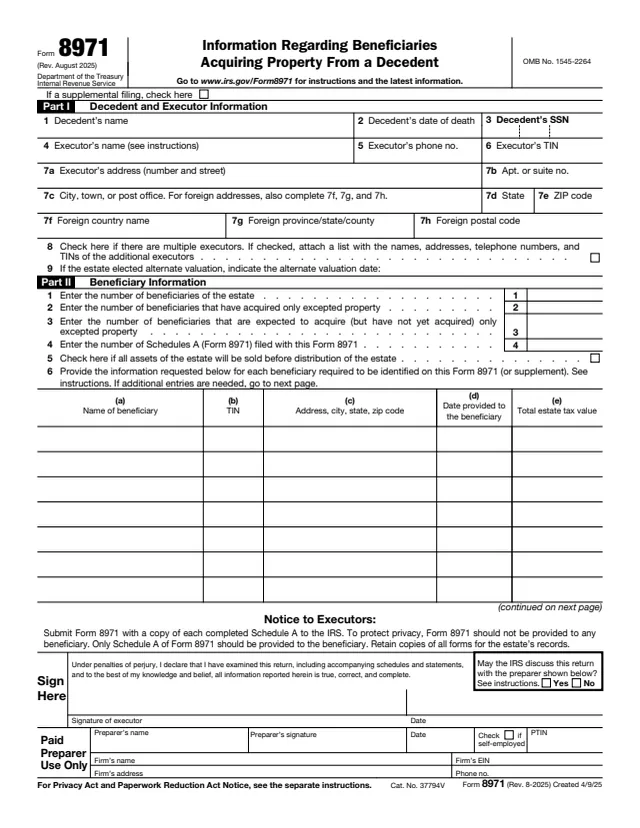
8971
196 fields, 2 pages

706
316 fields, 5 pages
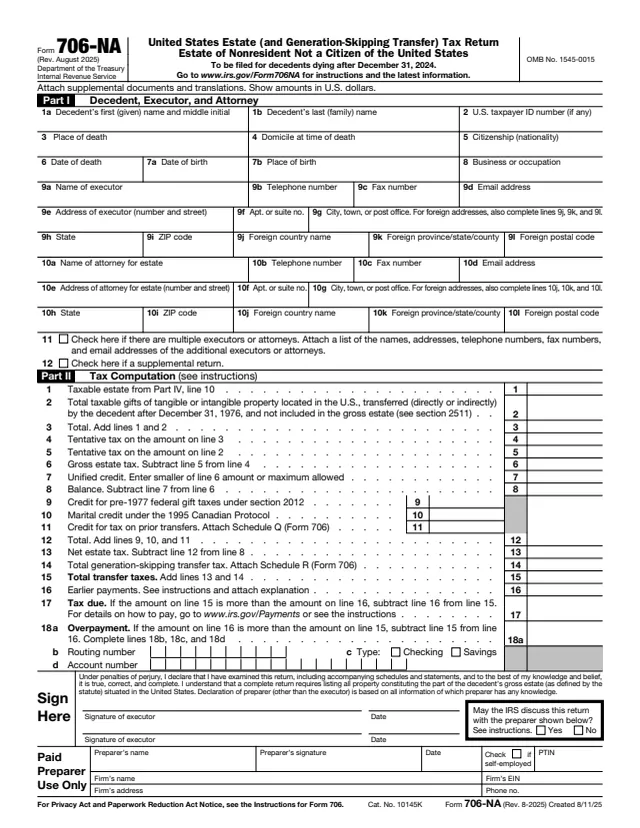
706-NA
259 fields, 3 pages

2848
92 fields, 2 pages
The executor of the estate completes Schedule A and furnishes it to the beneficiary. The notice on the form tells the beneficiary to retain it for tax reporting purposes.
No tool matches that search.
The executor. The instructions say an executor required to file Form 8971 completes and furnishes all required Schedules A to beneficiaries.
No. The instructions say to furnish each Schedule A only to the beneficiary named on it and not to provide a copy of Form 8971 to a beneficiary.
The estate tax value as reported on Form 706 or Form 706-NA, or the final value once it is determined. The instructions say to report the full fair market value, undiminished by debt.
It is furnished by the Form 8971 due date: the earlier of 30 days after the estate tax return is required to be filed, including extensions, or 30 days after it is filed.
The instructions say the executor files a supplement to Form 8971 and furnishes a supplemental Schedule A to each affected beneficiary, with the Supplemental filing box checked on line 8.
The notice on the form says to retain the schedule for tax reporting purposes, and that IRC section 1014(f) requires consistent reporting of basis if the property increased the estate tax liability.