Part I: Decedent, Executor, and Attorney
The decedent's name, U.S. taxpayer ID number, place of death, domicile, citizenship and dates, plus executor and attorney contact details, a box for multiple executors and a box for a supplemental return.
706-NA
United States Estate (and Generation-Skipping Transfer) Tax Return Estate of Nonresident Not a Citizen of the United States
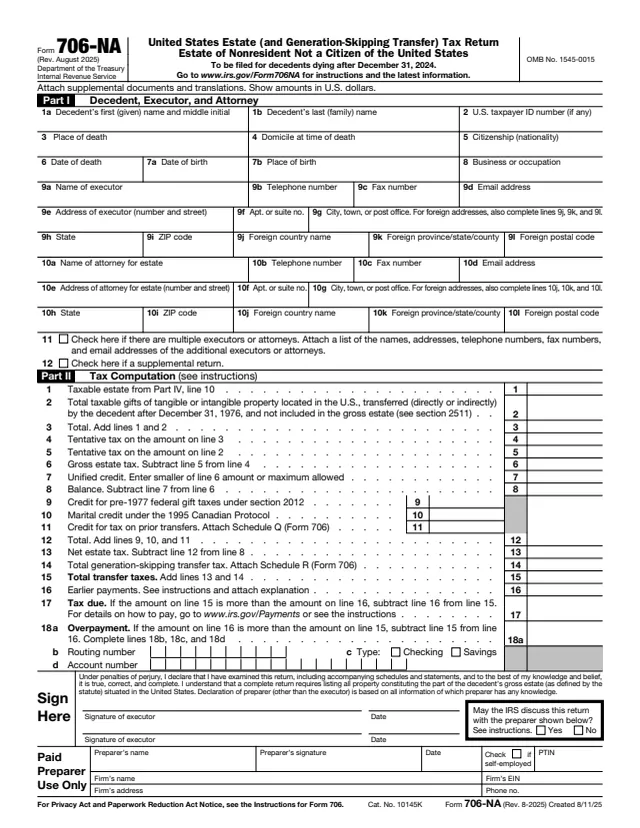
Form 706-NA, United States Estate (and Generation-Skipping Transfer) Tax Return, Estate of Nonresident Not a Citizen of the United States, is used to compute estate and generation-skipping transfer (GST) tax liability for nonresident not a citizen (NRNC) decedents. The IRS says the estate tax is imposed on the transfer of the decedent's taxable estate rather than on the receipt of any part of it.
The executor files it. The instructions say the executor files Form 706-NA if the date of death value of the decedent's U.S.-situated assets, together with the gift tax specific exemption and the amount of adjusted taxable gifts, exceeds the filing threshold of $60,000. The form says it is to be filed for decedents dying after December 31, 2024, with amounts shown in U.S. dollars.
The instructions say completing this return also calls for Form 706 and its instructions, since some Form 706 schedules are attached. You can fill out Form 706-NA free in your browser on this page and download it without an account.
The decedent's name, U.S. taxpayer ID number, place of death, domicile, citizenship and dates, plus executor and attorney contact details, a box for multiple executors and a box for a supplemental return.
Lines 1 to 18 run from the taxable estate through tentative tax, the unified credit and other credits, GST tax from Schedule R (Form 706), to tax due or an overpayment with direct deposit fields.
The executor's declaration under penalties of perjury, room for two executor signatures, a box allowing the IRS to discuss the return with the preparer, and the Paid Preparer Use Only area.
Yes or no questions on the will, U.S. real property, stock and debt, U.S. business, safe deposit boxes, joint property, past U.S. citizenship or residency, transfers, trusts, powers of appointment, gift tax returns and skip persons.
Lines 1 to 10 compare the gross estate in and outside the United States, prorate expenses, claims and losses, and subtract charitable, marital and state death tax deductions.
The section 2032 alternate valuation election and a table with item number, description, CUSIP number for securities, alternate valuation date and values in U.S. dollars.
On line 2, enter the decedent's SSN, or an ITIN only if it was used on other U.S. returns, or an IRSN already assigned. The instructions say to leave line 2 blank if there is none.
Answer each question. A Yes on lines 5, 7, 8, 9a, 9b or 11 points to Schedule E, G, H, R or R-1 (Form 706). A Yes on line 6a calls for a statement on citizenship history.
List only assets in the entire gross estate that are located in the United States. If line 1 is No, complete columns (a), (b), (c) and (f) and leave (d) and (e) blank.
Enter assets outside the United States on line 2 and deductible expenses on line 4. The instructions say lines 2 and 4 are documented, for example with a certified foreign death tax return and an itemized schedule.
Use Table A, Unified Rate Schedule, in the Form 706 instructions for the decedent's date of death on lines 4 and 5. The instructions say the maximum unified credit on line 7 is in general $13,000.
The executor verifies and signs under penalties of perjury. The instructions say it is sufficient for only one of several co-executors to sign.
The instructions say to complete the form in this order: Part I, Part III, Part V, Part IV and then Part II.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions give Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999. With a private delivery service: Internal Revenue Submission Processing Center, 333 W. Pershing, Kansas City, MO 64108.
The instructions say within 9 months after the date of death unless an extension was granted. Form 4768 applies for an automatic 6-month extension, with the "Form 706-NA" box checked in its Part II.
The instructions say tax due is paid within 9 months after death unless an extension to pay was granted. A check is payable to "United States Treasury" with the decedent's SSN (or ITIN) and "Form 706-NA" written on it.
A certified copy of the will if the decedent died testate, a copy of the death certificate, copies of available U.S. gift tax returns, and an English translation of all documents in other languages.
File another Form 706-NA, check line 12, explain what changed and attach a copy of the original. The instructions give Internal Revenue Service Center, Attn: E&G, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915.
The instructions say estates report the estate tax value of each asset to the IRS and the recipient on Form 8971 within 30 days of filing Form 706-NA, or earlier if the return is filed late.

706
316 fields, 5 pages
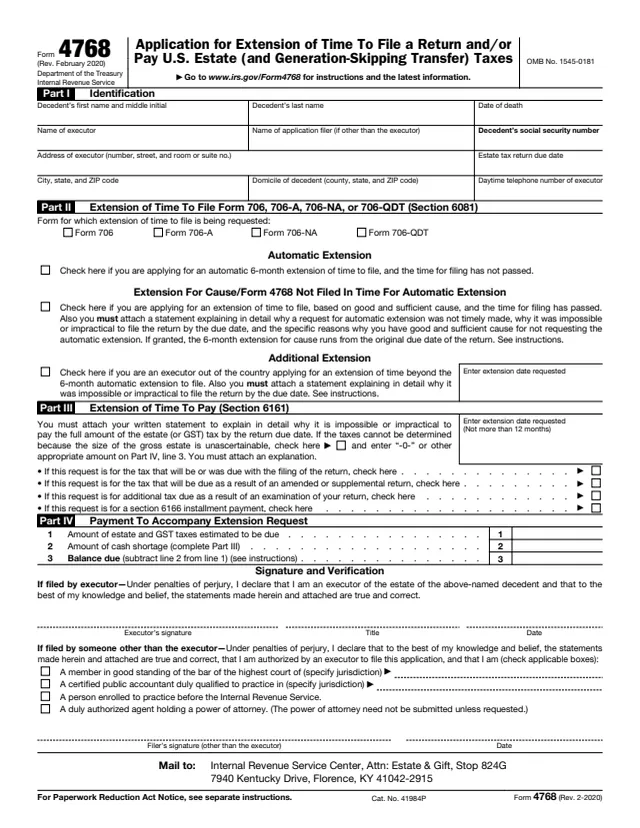
4768
35 fields, 1 page
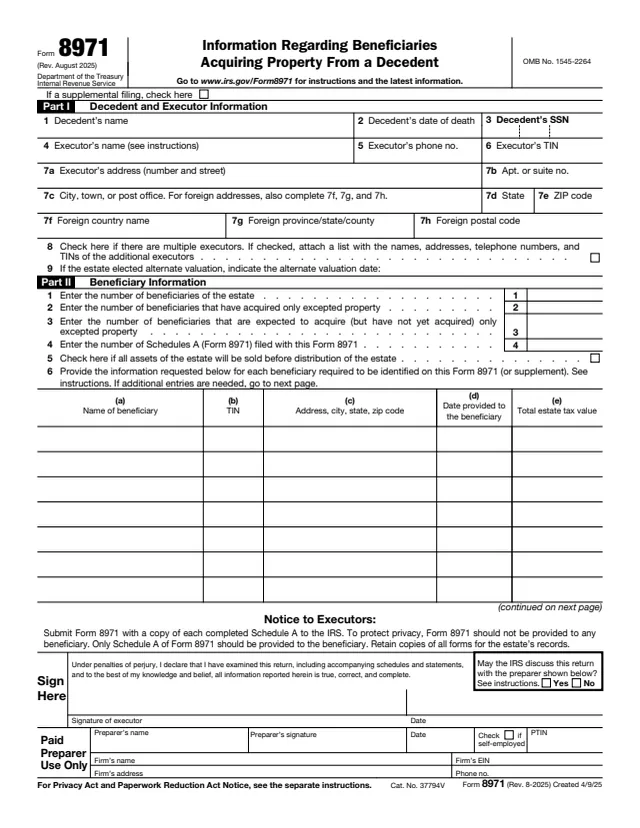
8971
196 fields, 2 pages
8854
208 fields, 5 pages

2848
92 fields, 2 pages
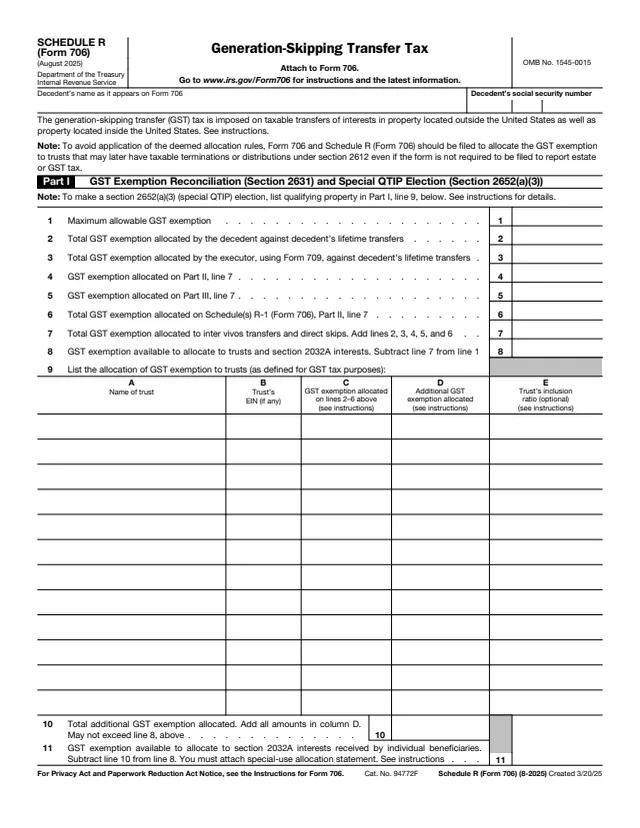
706 Sch. R
216 fields, 3 pages
The executor of the estate files Form 706-NA with the IRS and signs it under penalties of perjury.
No tool matches that search.
The executor of the estate of a nonresident not a citizen. The instructions say it is filed when U.S.-situated assets, plus the gift tax specific exemption and adjusted taxable gifts, exceed the filing threshold of $60,000.
The instructions say a decedent who was neither domiciled in nor a citizen of the United States at the time of death. A person acquires domicile by living in a place with no definite present intention of later moving.
The instructions say Form 706 and its instructions are needed to complete this return, and Form 706 schedules are attached for certain deductions, credits and Part III answers.
The instructions list Australia, Austria, Canada, Denmark, Finland, France, Germany, Greece, Ireland, Italy, Japan, the Netherlands, South Africa, Switzerland and the United Kingdom. A treaty-based position needs an attached statement.
The instructions say Part I, Part III, Part V, Part IV and then Part II.
The instructions say to file another Form 706-NA, check the line 12 box, include a statement of what changed with support, and attach a copy of the original return.
Only if the Yes box in the signature area is checked. The instructions say the authorization ends automatically 3 years from the date of filing Form 706-NA.