Heading and type of filer
Tax year, name, identifying number, address, the address of the service center where the tax return is filed, and boxes for individual, partnership, corporation, trust, estate or other.
5713
International Boycott Report
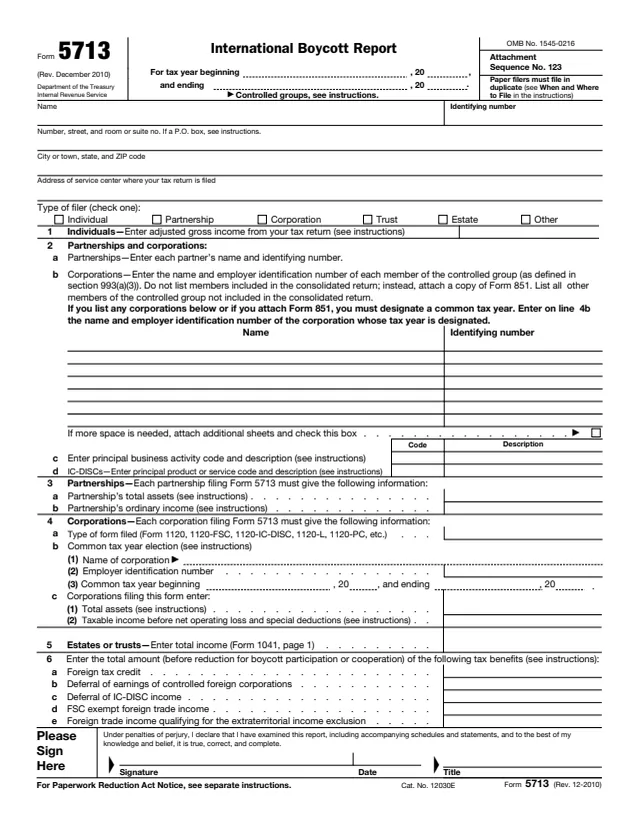
Form 5713, International Boycott Report, is filed with an income tax return. The IRS says U.S. persons file it to report operations in or related to boycotting countries, and the receipt of boycott requests and boycott agreements made.
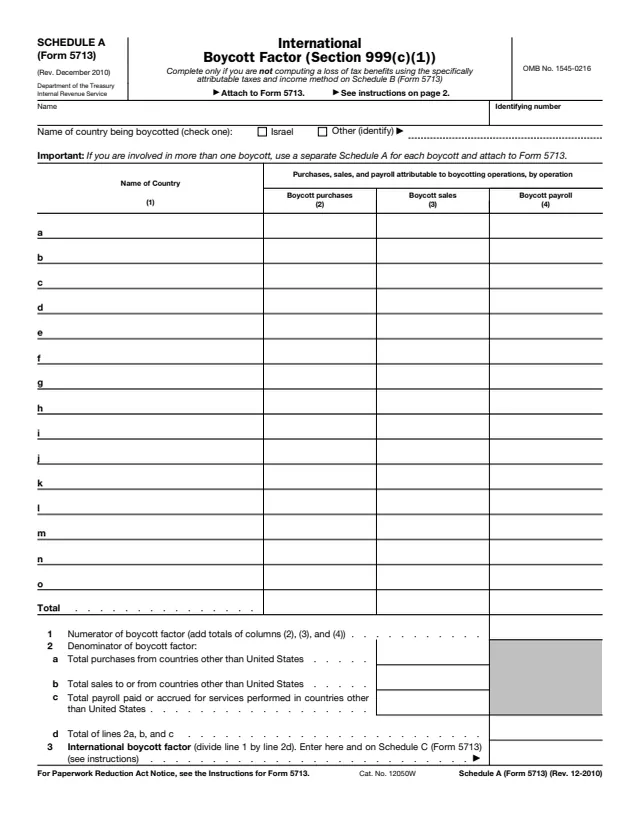
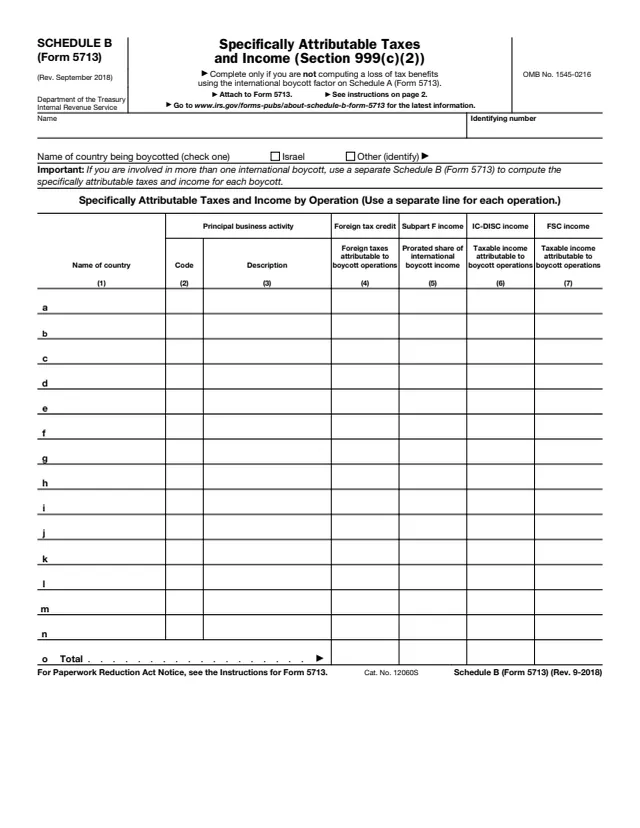
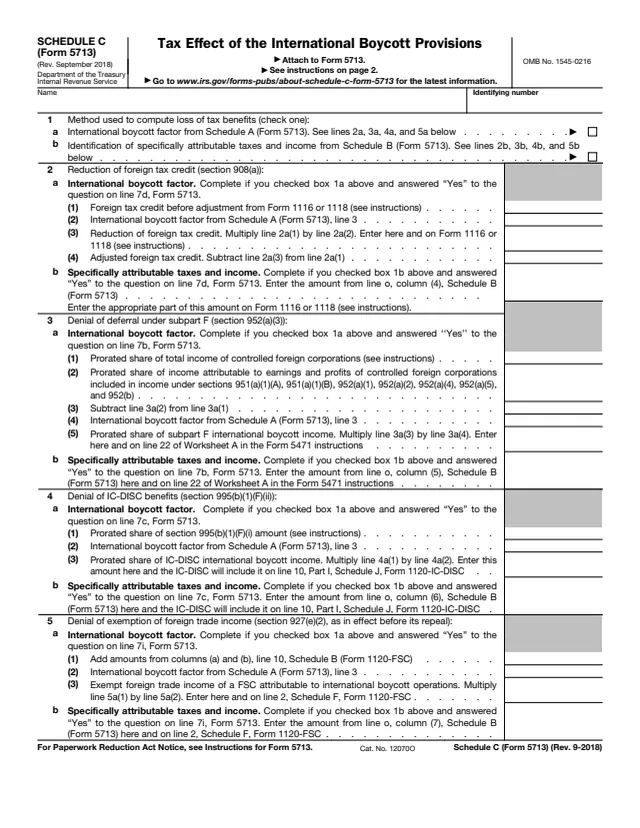
The instructions say it is filed by a U.S. person that has operations in or related to a boycotting country, or with the government, a company or a national of a boycotting country. Members of a controlled group, U.S. shareholders of a foreign corporation with operations, partners in a partnership with operations and owners of a trust with operations can also file it. The filer can be an individual, partnership, corporation, trust, estate or other. The report also lists tax benefits, such as the foreign tax credit, that the instructions say may be partly lost through participation in or cooperation with an international boycott, figured on Schedules A, B and C (Form 5713).
This page covers the December 2010 revision. You can fill it out free in your browser on this page and download the result without an account.
Tax year, name, identifying number, address, the address of the service center where the tax return is filed, and boxes for individual, partnership, corporation, trust, estate or other.
Adjusted gross income for individuals, partner and controlled group member lists, business activity codes, partnership assets and income, corporate return type, common tax year, and estate or trust total income.
Totals before reduction for boycott participation of the foreign tax credit, deferral of CFC earnings, deferral of IC-DISC income, FSC exempt foreign trade income and foreign trade income for the extraterritorial income exclusion.
Questions 7a to 7j on CFC ownership, IC-DISC stock, foreign tax credits, control relationships, trusts, partnerships, FSCs and excluded extraterritorial income.
Line 8 for the listed countries in the boycott of Israel, line 9 for nonlisted countries, line 10 for other boycotts, each with a country table, then line 11 on requests and line 12 on participation or cooperation.
Line 13a lists types of boycott requests and agreements. Line 13b is a table with the number of requests and agreements and a code for each type.
Enter the name, identifying number and address, and check one type of filer. For the service center address, the instructions say to enter "e-file" if the return was e-filed.
Complete the lines for the filer type, such as line 1 for an individual's adjusted gross income or line 4 for a corporation, then enter the line 6 tax benefit totals.
Answer each question. For a Yes on lines 8 to 10, the instructions say to use a separate line for each country or each person having operations in that country.
For a Yes, the form says to attach a copy in English of the requests received or the boycott clauses agreed to. The instructions allow one sample and a statement when there are many similar ones.
Enter counts and codes 01 to 05 on line 13b. The form notes that a Yes on question 12 leads to Schedules A and C or B and C (Form 5713).
Sign, date and enter a title under the penalties of perjury statement on page 1. The instructions say not to sign the copy attached to the income tax return.
The Instructions for Form 5713 give directions for each line.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 5713 is due when the income tax return is due, including extensions. The original copy, with Schedules A, B and C if applicable, is attached to the income tax return.
The form says paper filers file in duplicate. The instructions say a filer who files the original electronically, attached to an e-filed income tax return, is not required to file a duplicate.
The instructions say willful failure to file Form 5713 may result in a $25,000 fine, imprisonment for no more than 1 year, or both.
The foreign tax credit, deferral of CFC earnings, deferral of IC-DISC income, FSC exempt foreign trade income and the extraterritorial income exclusion. The loss is figured on Schedules A and C or B and C.
The instructions cite the Treasury list dated May 4, 2018: Iraq, Kuwait, Lebanon, Libya, Qatar, Saudi Arabia, Syria, United Arab Emirates and Yemen. They say the list is updated quarterly at FEDERALREGISTER.gov.
The form is the December 2010 revision. The Instructions for Form 5713 that cover it are revised 09/2018.
5713
74 fields, 2 pages
5713
107 fields, 2 pages
5713
26 fields, 2 pages
8873
152 fields, 2 pages
1118
1,263 fields, 12 pages
1116
118 fields, 2 pages
The instructions define who files it, with several exceptions. The report is signed under penalties of perjury.
No tool matches that search.
The instructions name U.S. persons with operations in or related to a boycotting country, plus certain controlled group members, U.S. shareholders of foreign corporations, partners and trust owners whose entity has operations.
No. The instructions say to attach the original to the income tax return, due when that return is due, including extensions.
Countries on the list kept by the Secretary of the Treasury under section 999(a)(3), plus any other country where the filer knows or has reason to know a boycott is required. The instructions say the list is updated quarterly.
No. The instructions say not to report boycotts approved by U.S. law, regulations or an Executive order on Form 5713.
The instructions say a partner does not file if the partner has no separate boycott operations, the partnership files Form 5713 with Form 1065, and the partnership did not cooperate with or participate in a boycott.
The instructions say willful failure to file may result in a $25,000 fine, imprisonment for no more than 1 year, or both.